EPF Retirement Investment: रिटायरमेंट के बाद नियमित कमाई के लिए EPF का पैसा कहां लगाएं? एक्सपर्ट्स से जानिए

EPF Retirement Investment: कई सैलरीड कर्मचारी रिटायरमेंट के समय Employees’ Provident Fund (EPF) में काफी अच्छा खासा पासा जमा कर लेते हैं। लेकिन जैसे ही सैलरी बंद होती है, असली चुनौती शुरू होती है। सवाल यह होता है कि इस पैसे को लंबे समय तक कैसे चलाया जाए। क्या पूरा पैसा EPF में ही रखा जाए या महंगाई से बचने के लिए कुछ हिस्सा बाजार से जुड़े निवेश में लगाया जाए? कितना जोखिम लेना सही होगा? और एकमुश्त रकम से नियमित आय कैसे बनाई जाए?

अगर आपके पास EPF में बड़ा कॉर्पस है, तो रिटायरमेंट के बाद लक्ष्य सिर्फ पैसे को सुरक्षित रखना नहीं होता। जरूरी यह भी है कि यह पैसा आने वाले वर्षों में आपके खर्चों को पूरा करने के लिए काम करता रहे।

रिटायरमेंट के बाद EPF पर ब्याज कैसे मिलता है

रिटायरमेंट के बाद EPF पर मिलने वाले ब्याज को लेकर अक्सर उलझन रहती है। Kustodian Life के फाउंडर कुणाल काबरा बताते हैं कि EPF नियमों के मुताबिक- 58 साल को आधिकारिक रिटायरमेंट उम्र माना जाता है। रिटायरमेंट के बाद EPF में योगदान बंद हो जाता है, लेकिन बैलेंस पर कुछ समय तक ब्याज मिलता रहता है।

नियम दो तरह से लागू होते हैं। अगर कोई व्यक्ति 58 साल की उम्र में रिटायर होता है, तो उसके EPF बैलेंस पर तीन साल तक यानी 61 साल की उम्र तक ब्याज मिलता है। लेकिन अगर कोई 58 साल से पहले रिटायर होता है, तो उसे ब्याज सिर्फ 58 साल की उम्र तक ही मिलेगा। इसका मतलब है कि 58 साल एक तरह से कट-ऑफ उम्र है। तीन साल तक ब्याज मिलने का फायदा तभी मिलता है, जब रिटायरमेंट आधिकारिक उम्र यानी 58 साल पर हो।

इसे उदाहरण से समझिए

अब मान लीजिए कि अगर कोई 57 साल में रिटायर होता है, तो उसे ब्याज 60 साल तक मिलेगा। अगर कोई 55 साल में रिटायर होता है, तो ब्याज 58 साल तक मिलेगा। यहां तक कि अगर कोई 45 साल में रिटायर होता है, तब भी ब्याज केवल 58 साल तक ही मिलेगा।

आमतौर पर EPF पर मिलने वाली ब्याज दर करीब 8 प्रतिशत के आसपास रहती है, लेकिन यह ब्याज इन्हीं तय सीमाओं के भीतर मिलता है। यहां तक कि अगर कोई व्यक्ति 58 के बाद भी काम करता रहे, तब भी नए EPF योगदान आम तौर पर बंद हो जाते हैं। ब्याज 61 साल की उम्र तक ही सीमित रहता है। इसी वजह से एक्सपर्ट मानते हैं कि रिटायरमेंट के बाद केवल EPF पर निर्भर रहना पर्याप्त नहीं होता।

फिक्स्ड इनकम का इंतजाम जरूरी

रिटायरमेंट के बाद सुरक्षित निवेश वाले हिस्से में भी केवल एक साधन पर निर्भर रहना सही नहीं माना जाता। Master Capital Services में वेल्थ मैनेजमेंट की AVP आकांक्षा शुक्ला कहती हैं कि EPF मुख्य रूप से बचत जमा करने का साधन है, न कि रिटायरमेंट में नियमित आय देने वाला साधन।

इसलिए रिटायरमेंट के बाद बचत को इस तरह व्यवस्थित करना जरूरी होता है कि उससे नियमित आय मिलती रहे। उदाहरण के तौर पर Senior Citizens’ Savings Scheme (SCSS) अपेक्षाकृत ज्यादा और स्थिर आय दे सकती है। वहीं बैंक फिक्स्ड डिपॉजिट भी अपनी सादगी और तय रिटर्न की वजह से कई लोगों की पसंद बने रहते हैं, खासकर उन लोगों के लिए जो मासिक आय चाहते हैं।

इसके अलावा डेट म्यूचुअल फंड पोर्टफोलियो में लचीलापन और लिक्विडिटी जोड़ सकते हैं। एक्सपर्ट्स के मुताबिक, इनके जरिए जरूरत के मुताबिक समय-समय पर पैसे निकालना आसान हो सकता है।

रिटायरमेंट में भी इक्विटी की भूमिका

कई रिटायर्ड लोगों को लगता है कि इक्विटी से पूरी तरह दूर रहना सुरक्षित रहेगा। लेकिन ऐसा करने से एक और जोखिम पैदा हो सकता है। समय के साथ महंगाई आपकी खरीद क्षमता को कम कर सकती है।

आकांक्षा शुक्ला के मुताबिक, बढ़ती औसत उम्र और महंगाई को देखते हुए रिटायरमेंट पोर्टफोलियो में इक्विटी की भूमिका अब धीरे धीरे जरूरी होती जा रही है।

आमतौर पर 15 से 20 प्रतिशत तक इक्विटी निवेश, खासकर लार्ज-कैप, इंडेक्स या हाइब्रिड फंड के जरिए, पोर्टफोलियो को लंबे समय में बढ़ने में मदद कर सकता है। यहां मकसद बहुत ज्यादा रिटर्न कमाना नहीं होता, बल्कि यह सुनिश्चित करना होता है कि आपका कॉर्पस समय के साथ खत्म न हो।

सही एसेट एलोकेशन क्यों जरूरी है

रिटायरमेंट के बाद पोर्टफोलियो का संतुलन बहुत महत्वपूर्ण होता है। इससे एक तरफ नियमित आय मिलती रहती है और दूसरी तरफ महंगाई से भी बचाव होता है।

आकांक्षा शुक्ला के अनुसार अगर किसी के पास करीब 3 करोड़ रुपये का कॉर्पस है, तो निवेश को चार हिस्सों में बांटना एक सामान्य रणनीति हो सकती है। इसमें EPF और अन्य फिक्स्ड इनकम साधन, डेट निवेश, इक्विटी और एक छोटा इमरजेंसी फंड शामिल हो सकता है। असल में यह डिस्ट्रीब्यूशन कुछ इस तरह हो सकता है:

  • 40 से 50 प्रतिशत फिक्स्ड इनकम
  • 30 से 35 प्रतिशत डेट निवेश
  • 15 से 20 प्रतिशत इक्विटी
  • और एक छोटा इमरजेंसी फंड

एकमुश्त रकम से नियमित आय कैसे बनाएं

रिटायरमेंट के समय मिलने वाली बड़ी रकम को सही तरीके से निवेश करना जरूरी होता है। Arihant Capital Markets की CEO Wealth स्वाति जैन के अनुसार, पूरी रकम एक साथ निवेश करने की बजाय Systematic Transfer Plan (STP) का इस्तेमाल किया जा सकता है।

इसमें पैसा पहले कम जोखिम वाले डेट या लिक्विड फंड में रखा जाता है और फिर 6 से 12 महीनों के दौरान धीरे धीरे इक्विटी या हाइब्रिड फंड में ट्रांसफर किया जाता है। इससे बाजार के उतार चढ़ाव का जोखिम कम हो जाता है।

नियमित आय के लिए Systematic Withdrawal Plan (SWP) भी बेहतर तरीका हो सकता है। इसमें निवेश से तय अंतराल पर एक निश्चित रकम निकाली जाती है, जिससे नियमित कैश फ्लो बना रहता है।

एक्सपर्ट्स सलाह देते हैं कि एक से दो साल के खर्च के बराबर रकम सुरक्षित निवेश में रखी जाए, ताकि बाजार गिरने के समय मजबूरी में पैसे निकालने की जरूरत न पड़े। इसके बाद SWP के जरिए नियमित आय बनाई जा सकती है।

रिटायरमेंट में सुरक्षित निकासी कितनी हो

स्वाति जैन के मुताबिक, इसके लिए बकेट रणनीति अपनाना इस्तेमाल हो सकता है। इसमें छोटे समय की जरूरतों के लिए डेट निवेश से SWP किया जाता है और लंबी अवधि की ग्रोथ के लिए इक्विटी में निवेश रखा जाता है।

एक्सपर्ट्स आम तौर पर 4 से 5 प्रतिशत सालाना निकासी को सुरक्षित मानते हैं। यानी अगर किसी के पास 3 करोड़ रुपये का कॉर्पस है, तो वह सालाना लगभग 12 से 15 लाख रुपये निकाल सकता है। यह दर आम तौर पर 20 से 25 साल तक टिकाऊ मानी जाती है, बशर्ते पोर्टफोलियो संतुलित बना रहे। अगर शुरुआती वर्षों में इससे ज्यादा पैसा निकाला जाए, तो भविष्य में कॉर्पस जल्दी खत्म होने का खतरा बढ़ सकता है।

PPF Maturity Rules: 15 साल पूरे होने पर भी मत निकालें पीपीएफ का पैसा! अपनाए ये आसान ट्रिक

Disclaimer: मनीकंट्रोल.कॉम पर दिए गए सलाह या विचार एक्सपर्ट/ब्रोकरेज फर्म के अपने निजी विचार होते हैं। वेबसाइट या मैनेजमेंट इसके लिए उत्तरदायी नहीं है। यूजर्स को मनीकंट्रोल की सलाह है कि कोई भी निवेश निर्णय लेने से पहले हमेशा सर्टिफाइड एक्सपर्ट की सलाह लें।
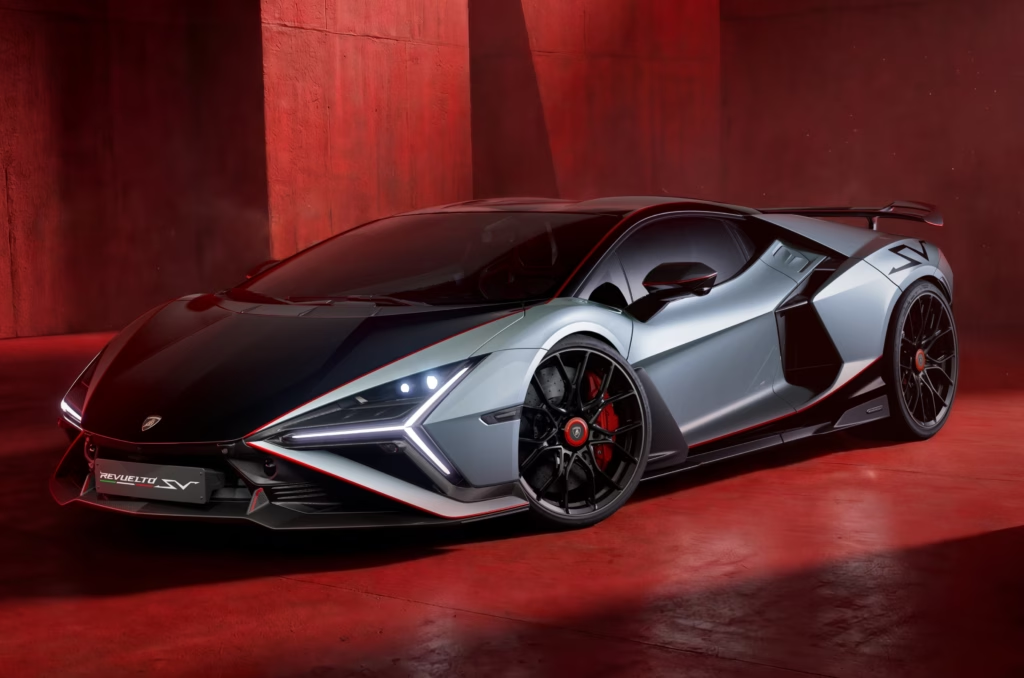
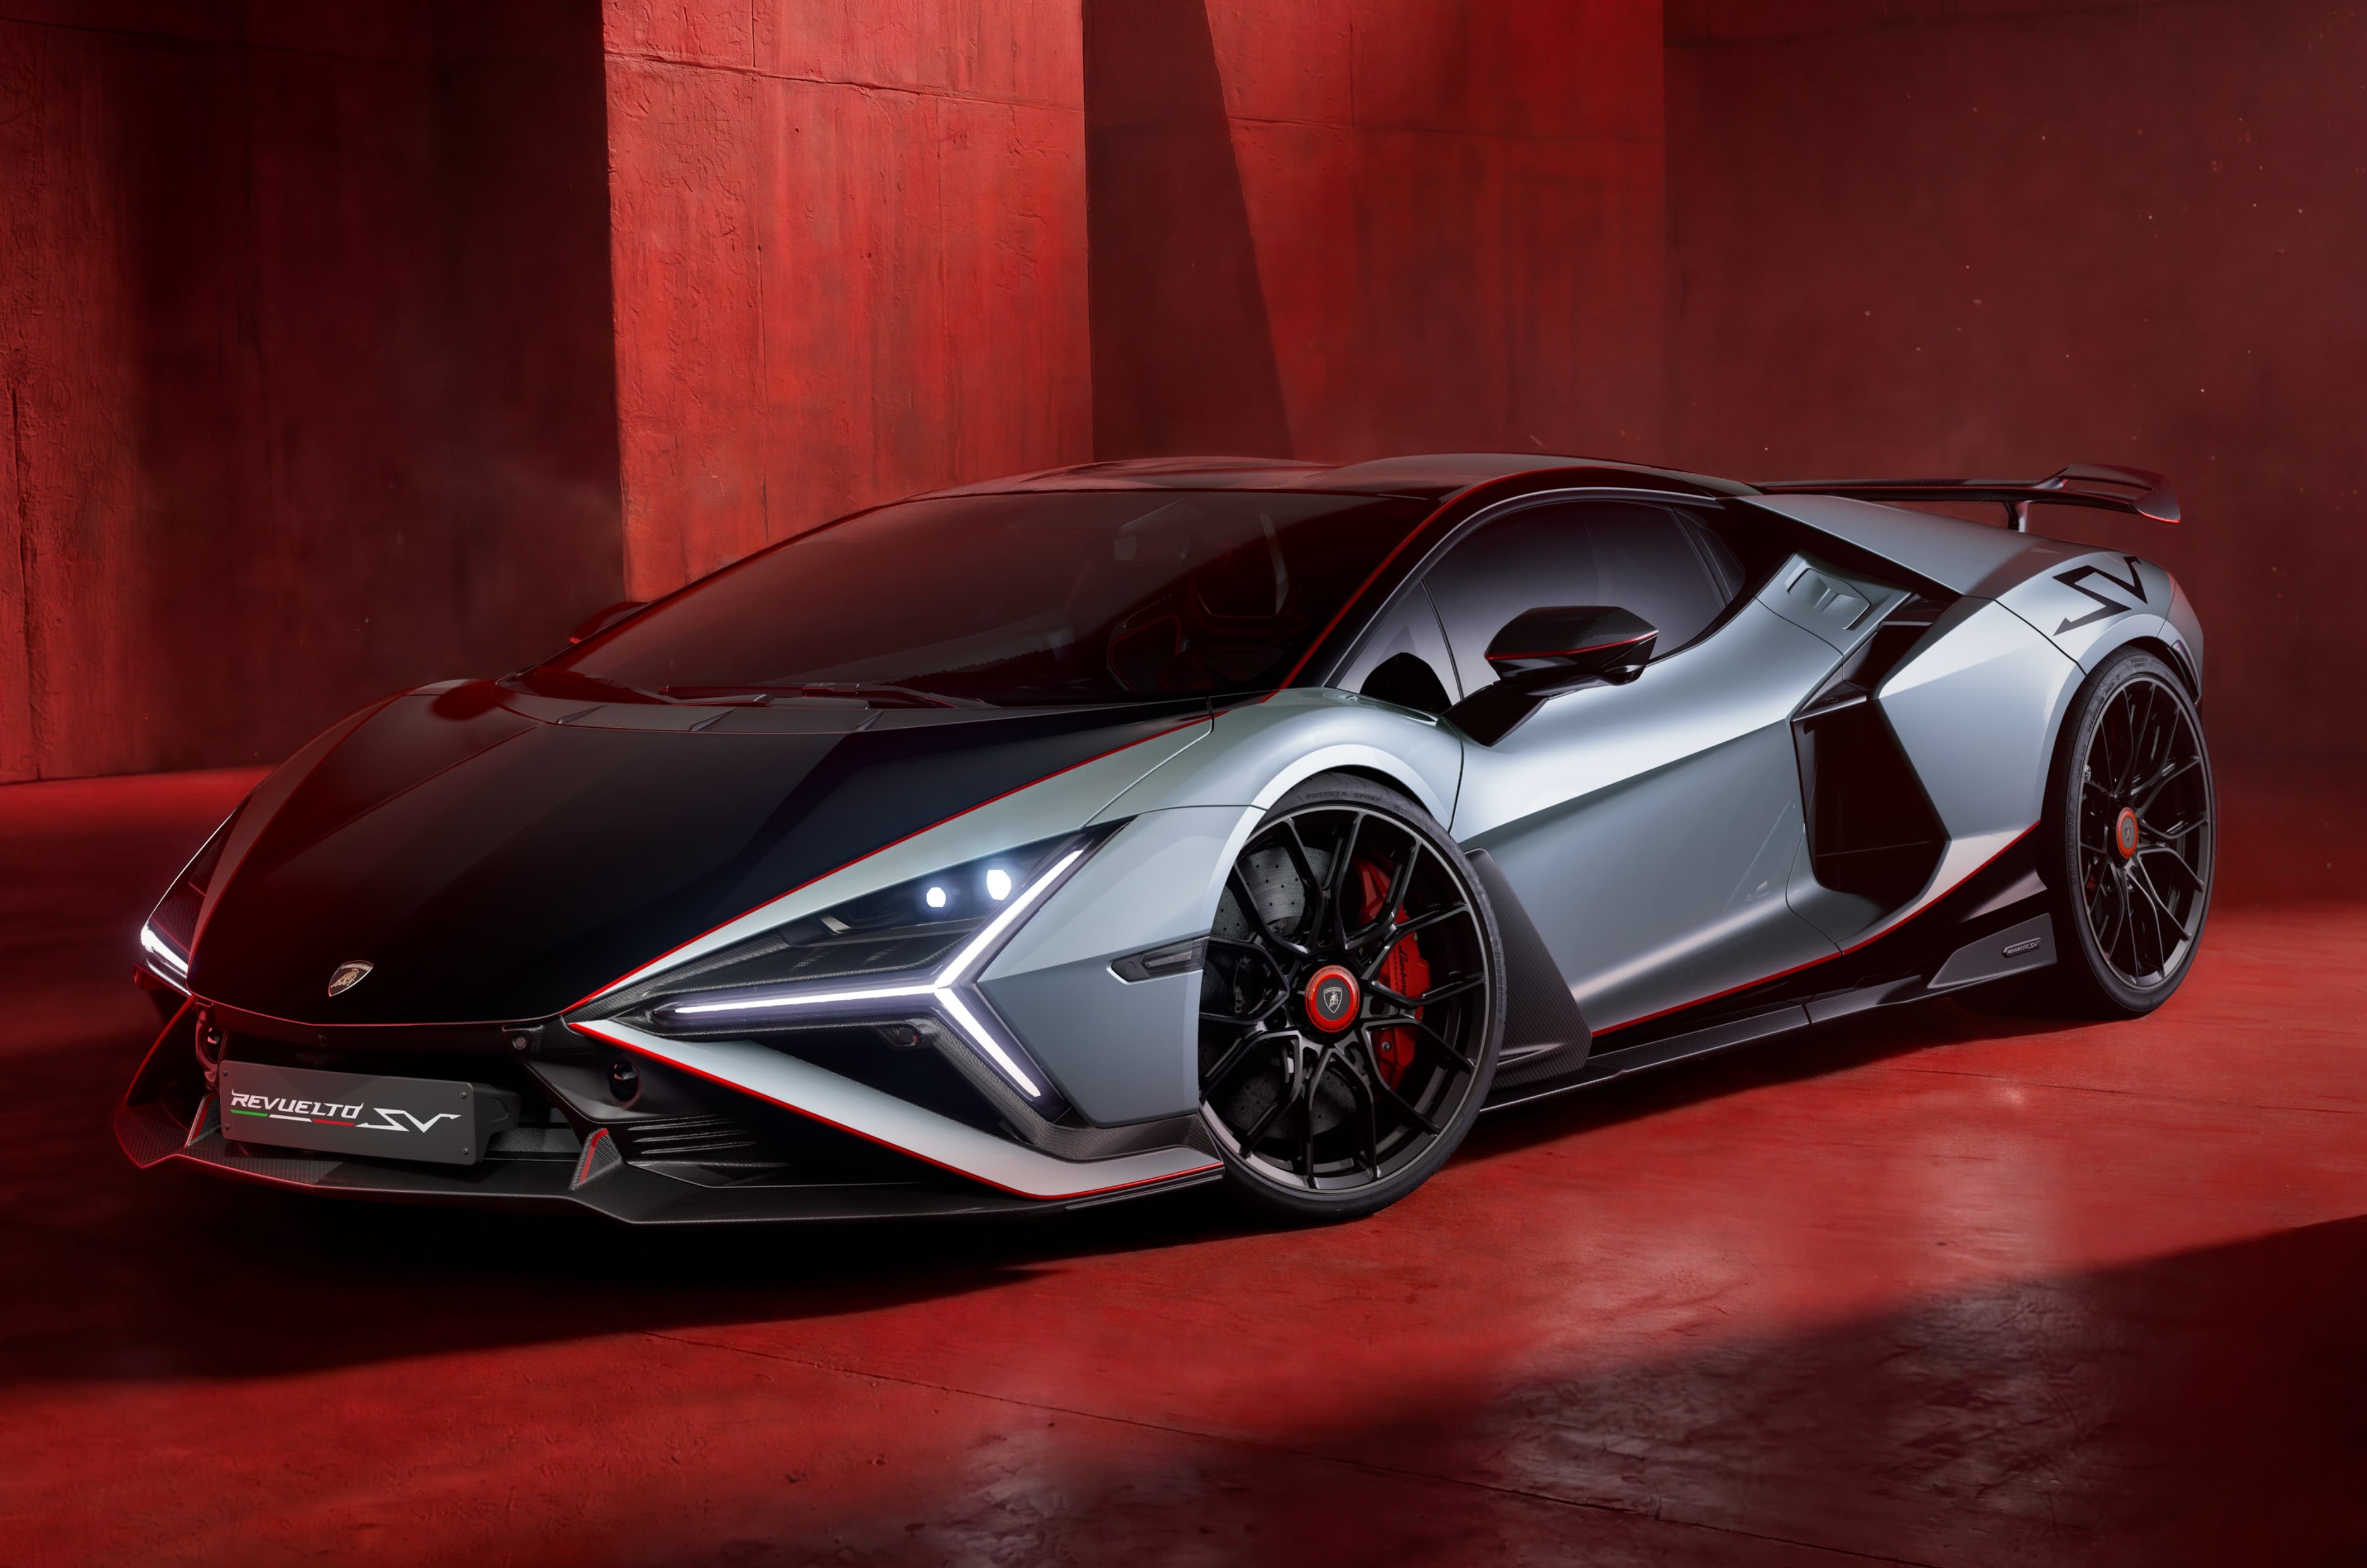
Lamborghini Revuelto SV debuts as supercar’s track-focused version

Lamborghini Revuelto SV debuts as supercar's track-focused version
Lamborghini Revuelto SV in studio

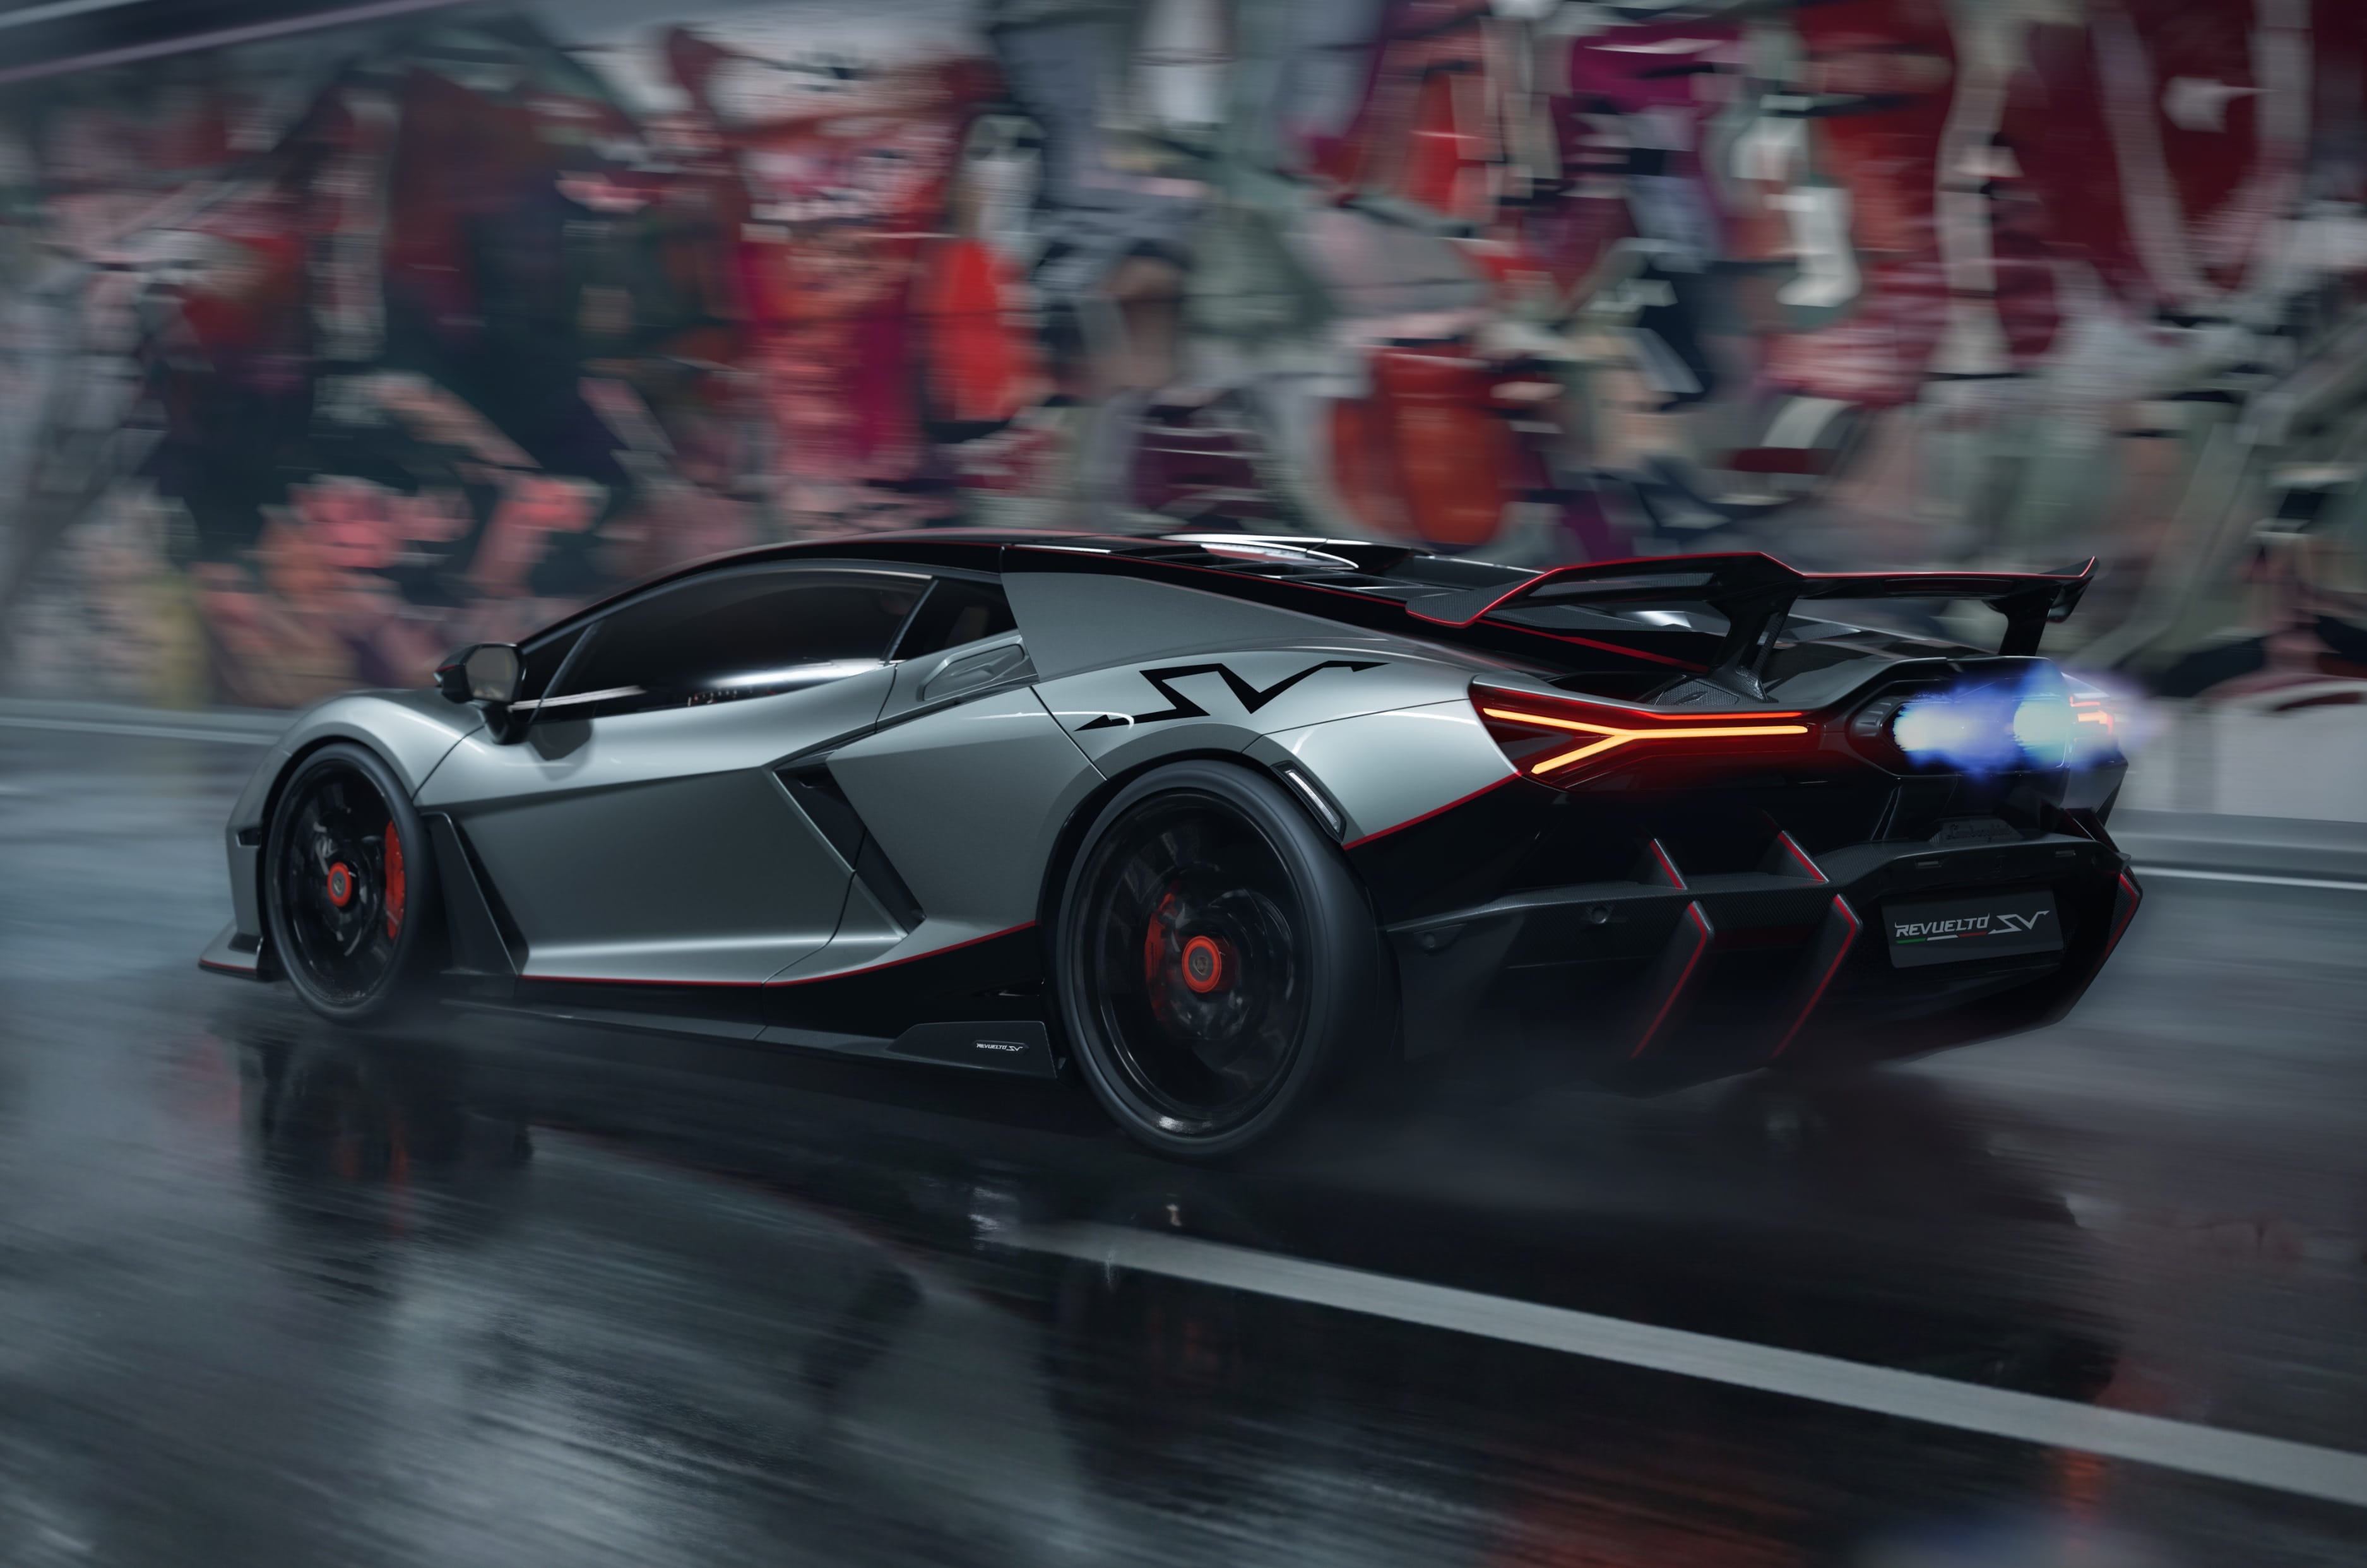
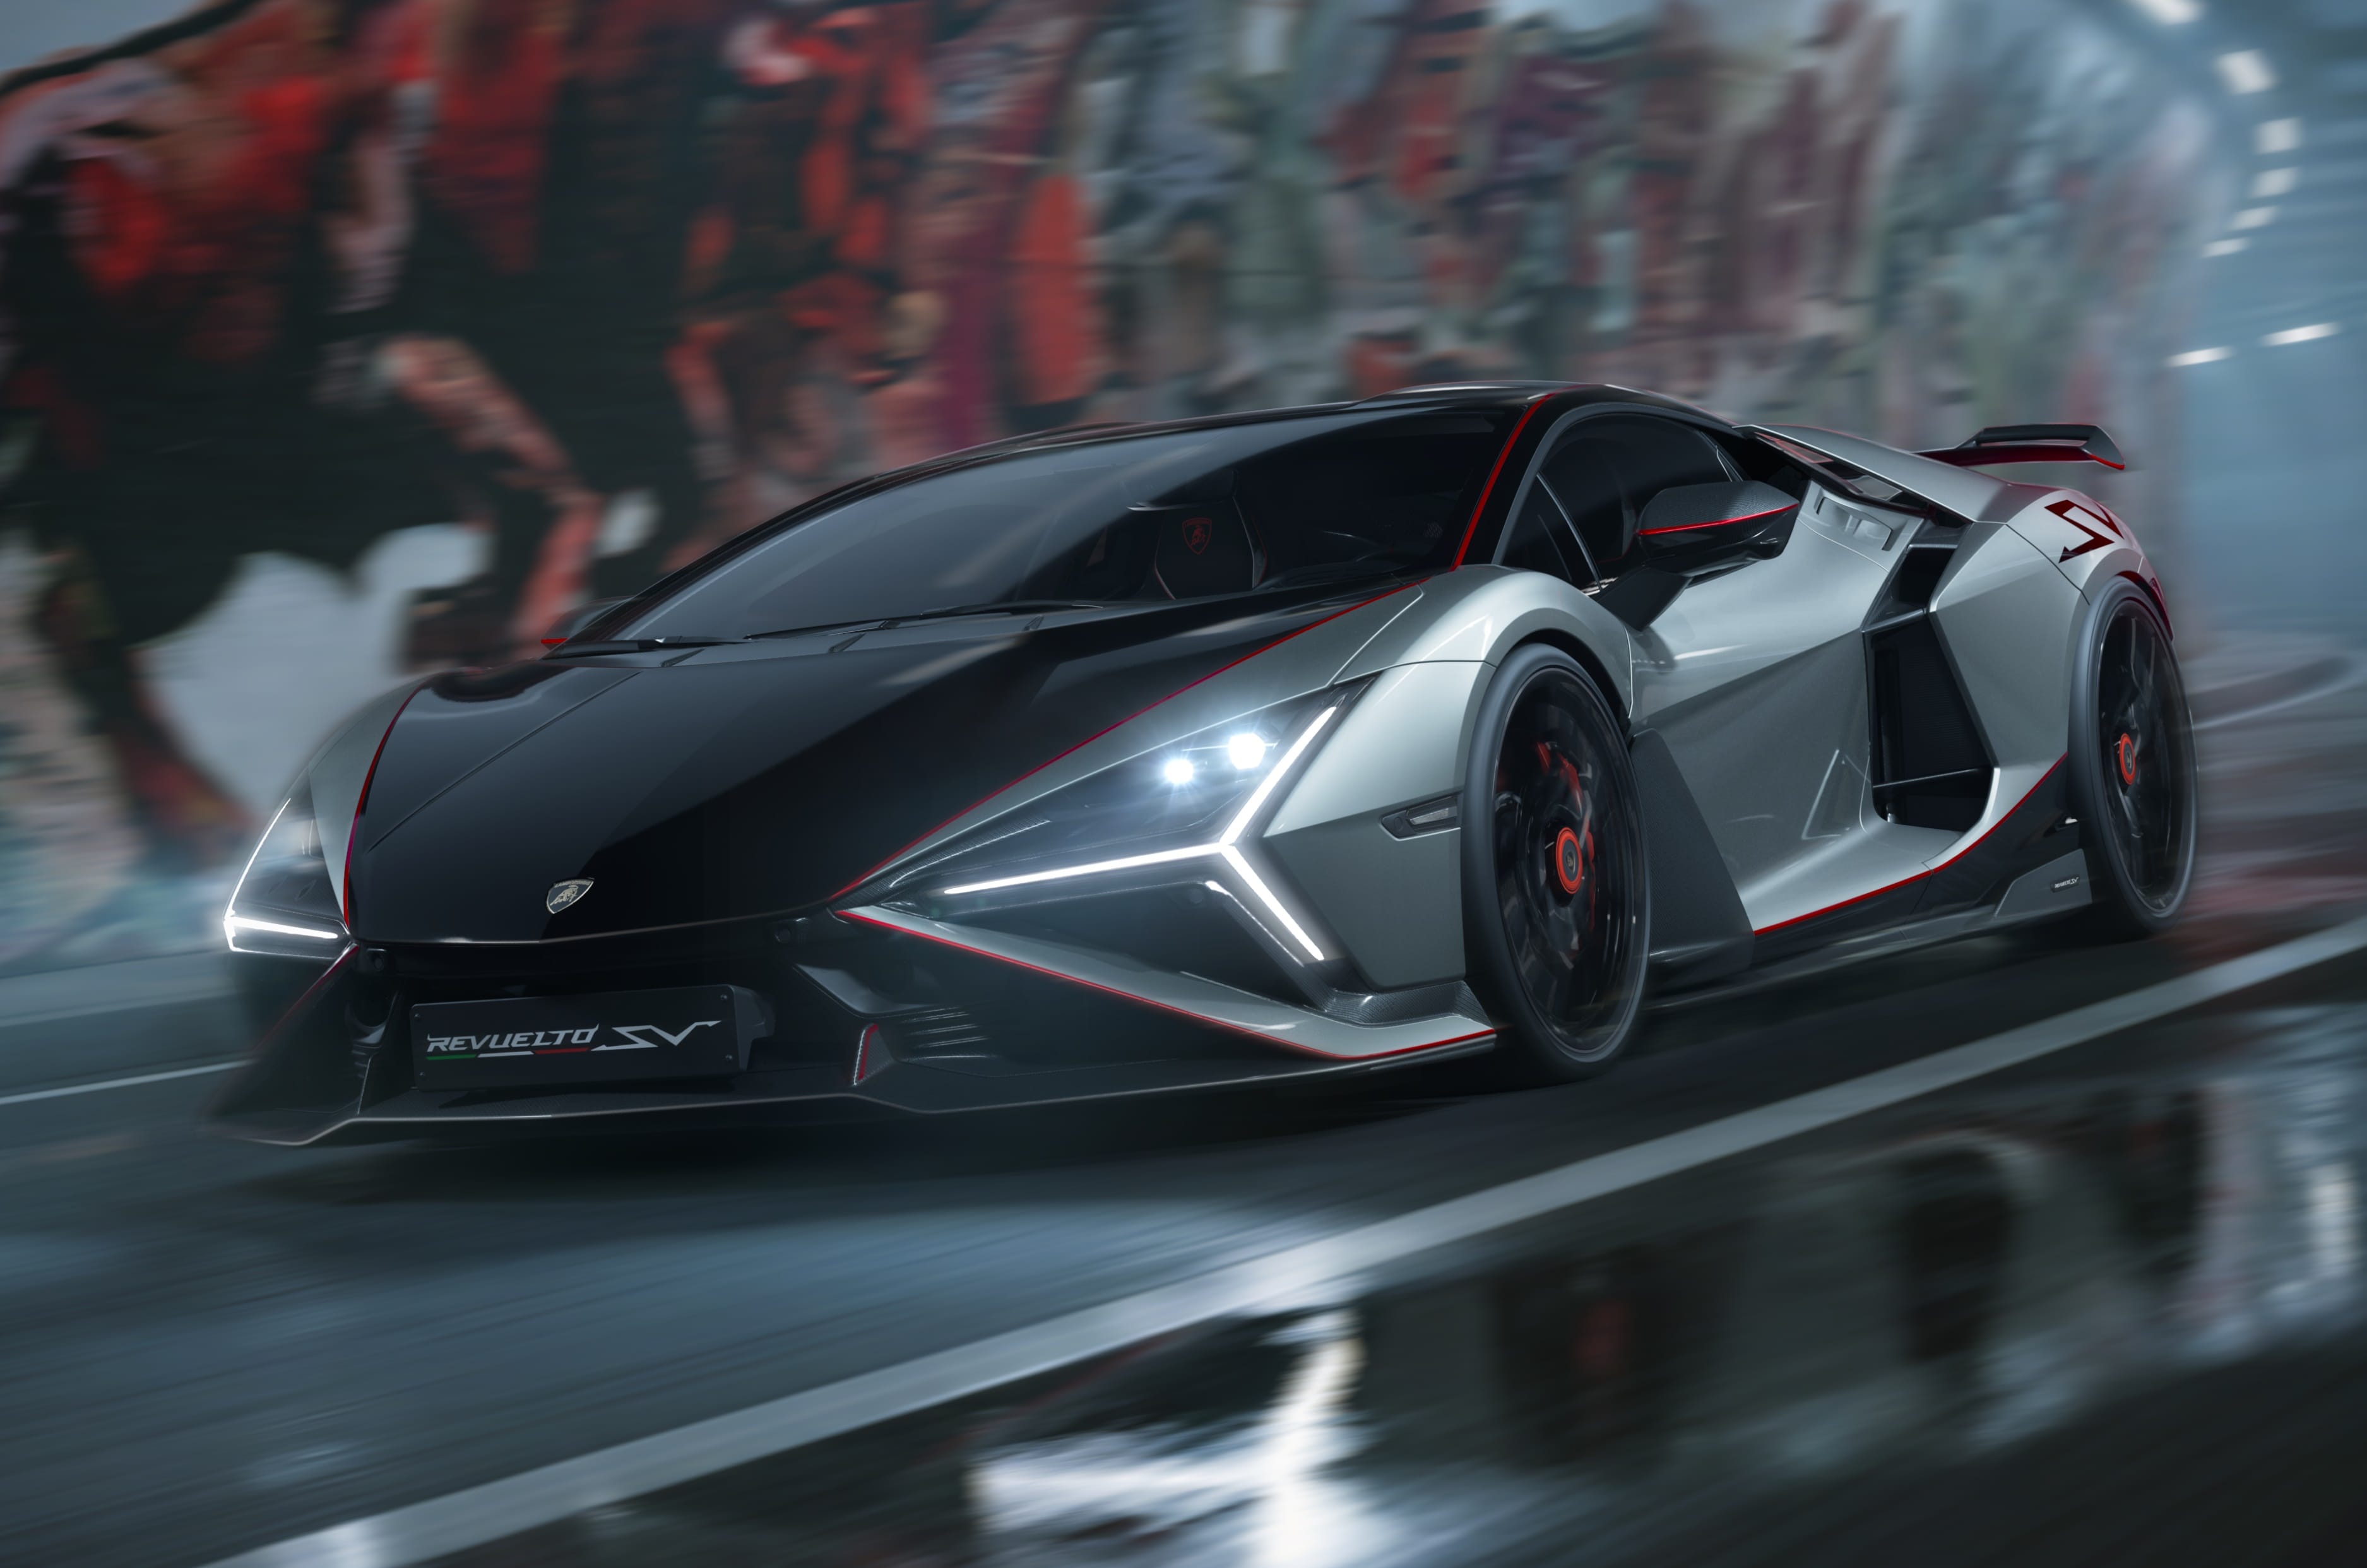
Lamborghini has unveiled the Revuelto Super Veloce (SV), a more extreme version of the Italian marque’s flagship series-production supercar. Only 1,963 units of the Revuelto SV will be built – a reference to Lamborghini’s founding year – and that too for the brand’s “most loyal customers and collectors.” Pricing has not been disclosed yet, but the SV is expected to command a significant premium over the vanilla Revuelto, which costs Rs 8.89 crore before options. 

Lamborghini Revuelto SV powertrain and performance

Makes 50hp more than the standard Revuelto

The Revuelto SV carries forward the standard model’s 825hp 6.5-litre naturally aspirated V12 (which revs to a wailing 9,500rpm), 7.3kWh battery pack, and trio of electric motors, but the latter’s output has been uprated from 190hp to 299hp. Combined output for the Revuelto SV’s V12 PHEV powertrain stands at 1,065hp – up 50hp over the standard version. The 8-speed dual-clutch automatic gearbox and AWD layout remain unchanged.

0-100kph flashes by in a brisk 2.4 seconds (claimed) for the Revuelto SV, with 0-200kph taking just 6.7 seconds. The top speed, meanwhile, remains in excess of 345kph. A new sports exhaust system is part of the package, and thanks to weight savings, the Revuelto SV boasts a power-to-weight ratio of 602.4hp/tonne, which is up from the standard version’s 571.4hp/tonne. A new ‘Pilota’ drive mode has been introduced too, unlocking a custom motorsport-derived state of tune built around a bespoke five-stage traction control system that adapts to track conditions and tyre wear.

Enhanced suspension damping and braking system

On the dynamics front, Lamborghini has upgraded the Revuelto SV’s suspension with manually adjustable dampers derived from GT3 racing, which promise a 17 percent increase in agility and a 10 percent bump in lateral grip over the Revuelto. The SV also packs a revised braking control system and new CCM-R carbon-ceramic brake discs (420mm up front, 410mm at the rear), claiming an 11 percent higher peak deceleration, 23 percent better heat dissipation, and a 12 percent drop in brake disc temperatures.

Thanks to all of the aforementioned mechanical improvements, the Revuelto SV clocked a lap time of 1:41.6 around Hockenheimring, making it the second-fastest car to be officially timed at the German circuit.

Lamborghini Revuelto SV exterior updates

More menacing body kit

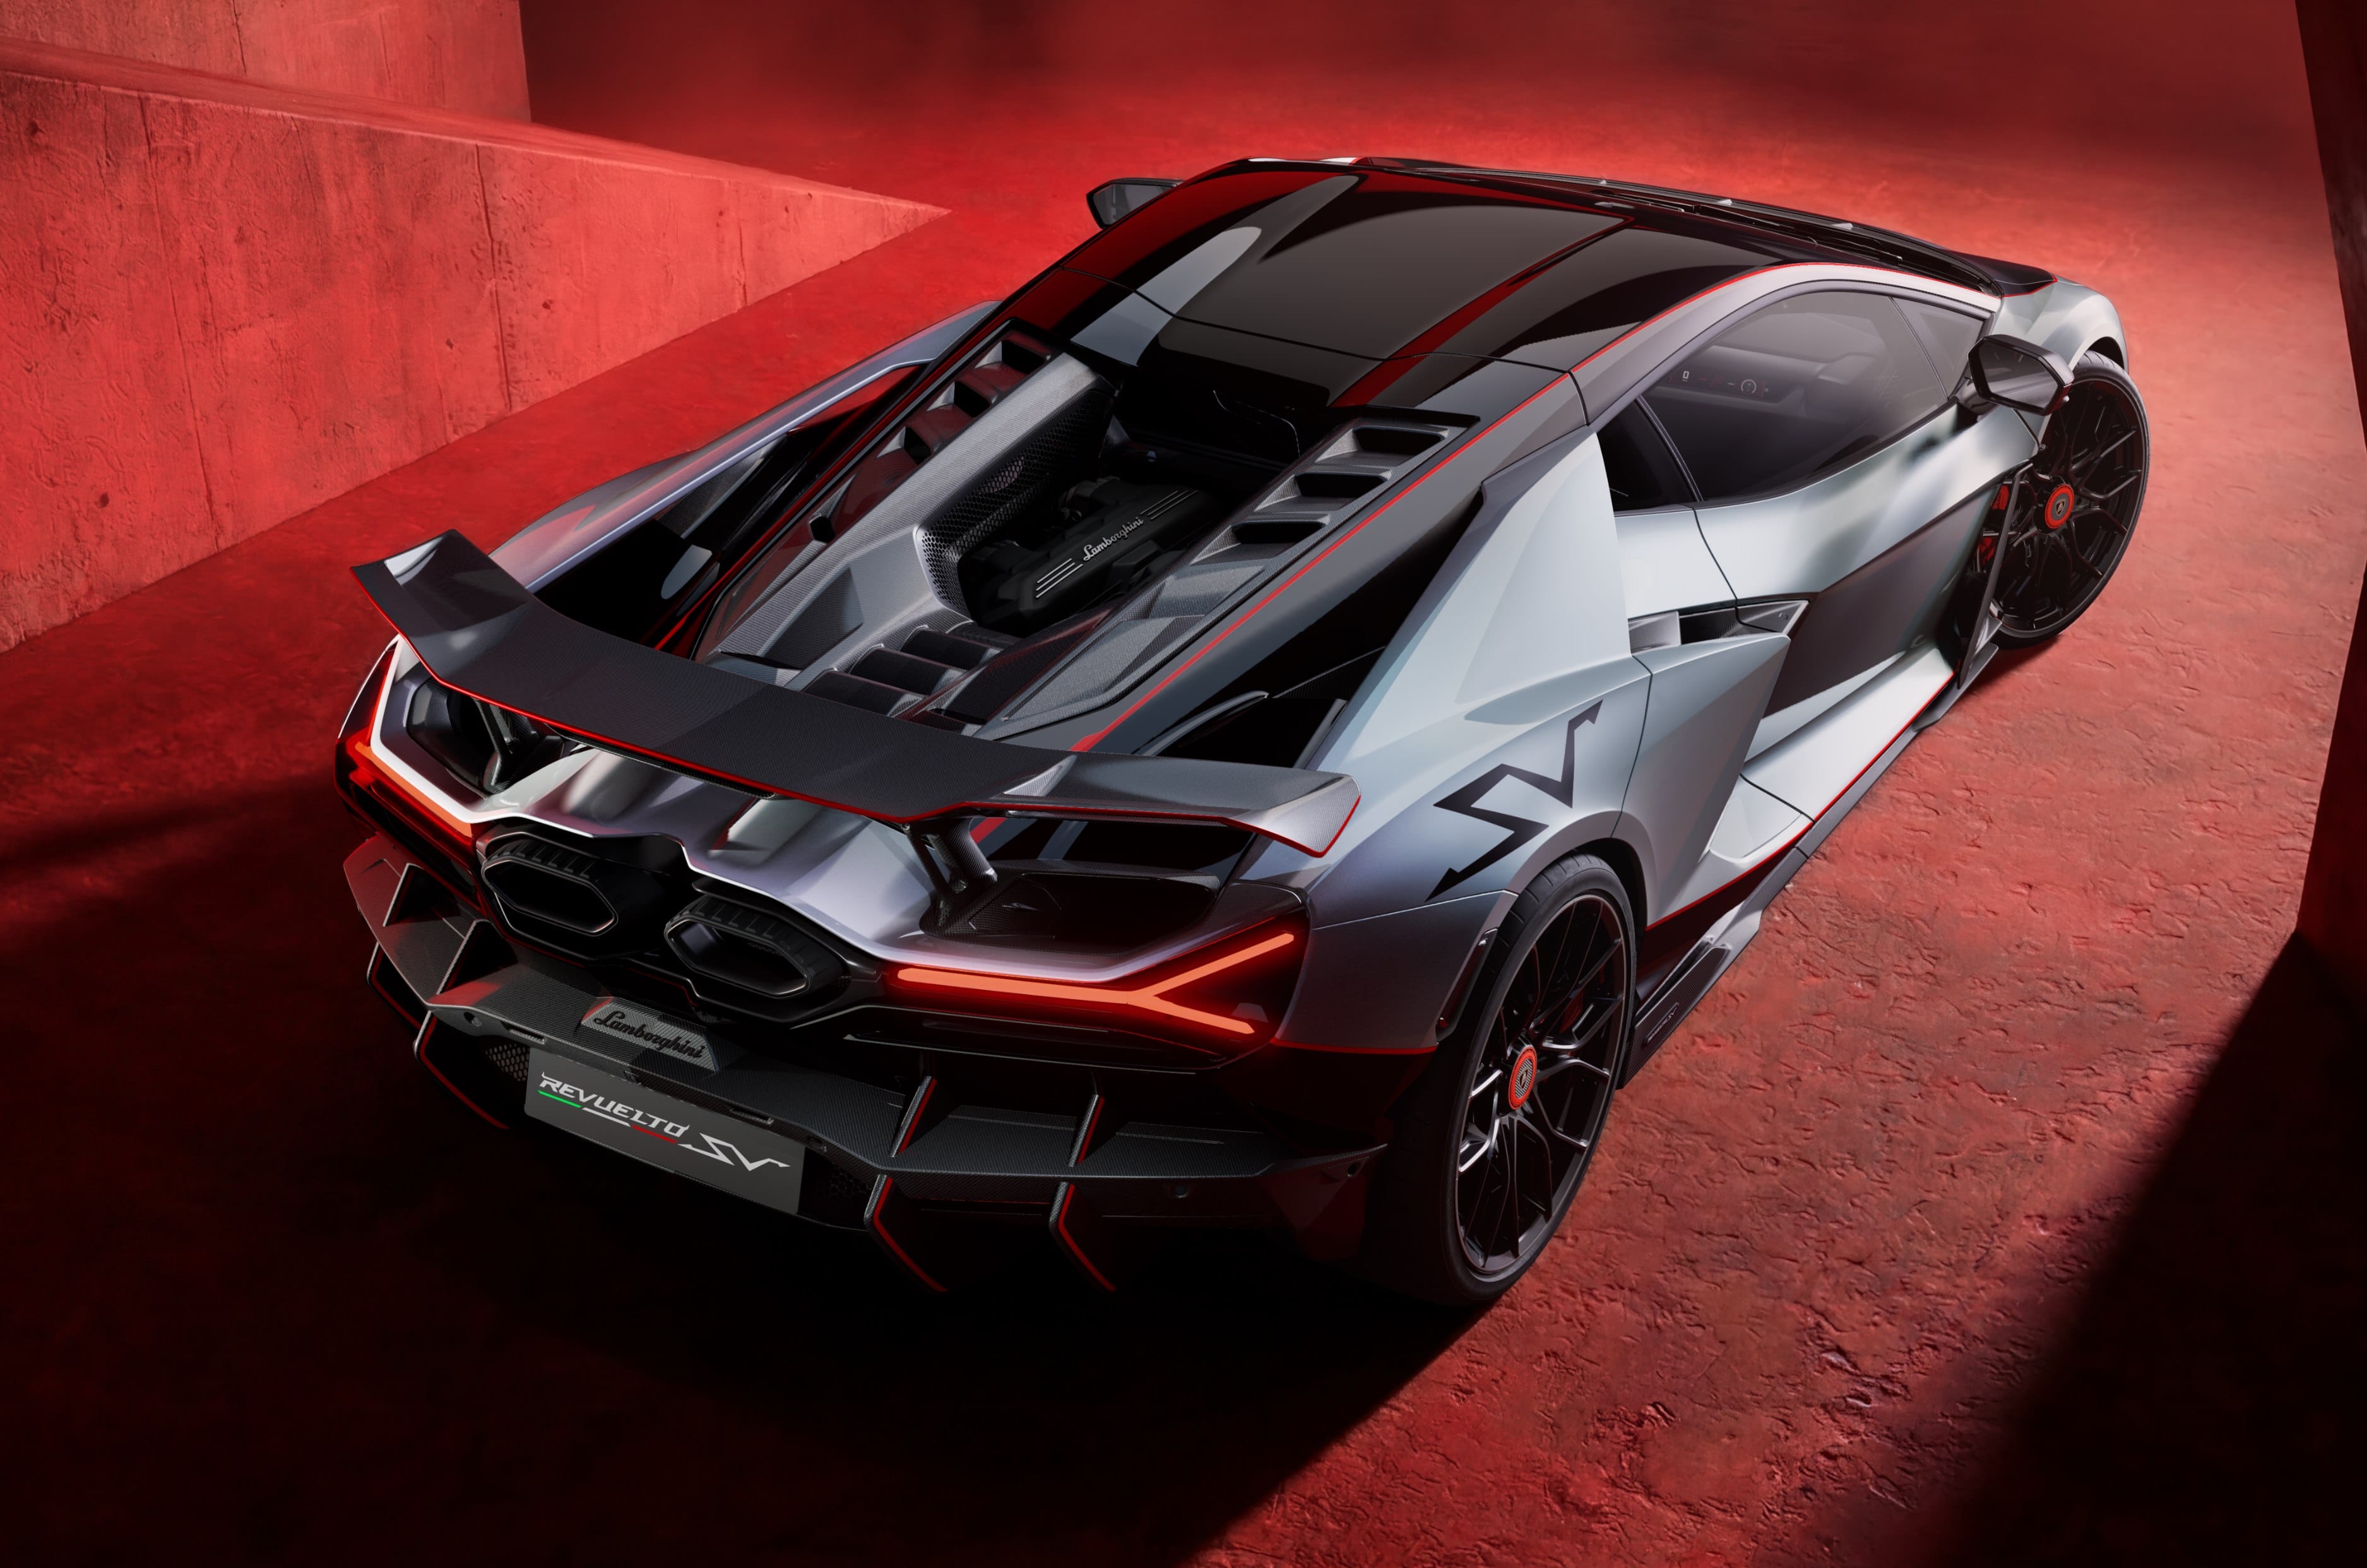
On the outside, the Revuelto SV looks much more aggressive than the standard version, courtesy of a new front diffuser with red accents, a revised rear diffuser, a massive rear wing, exclusive SV liveries and badging, contrast accents, and extensive use of carbon-fibre trim pieces. It also features a fresh set of lightweight centre-lock alloy wheels (20 inches front, 21 inches rear) shod in bespoke Bridgestone Potenza Race R tyres.

Lamborghini Revuelto SV interior updates

Bucket seats and new interior finishes

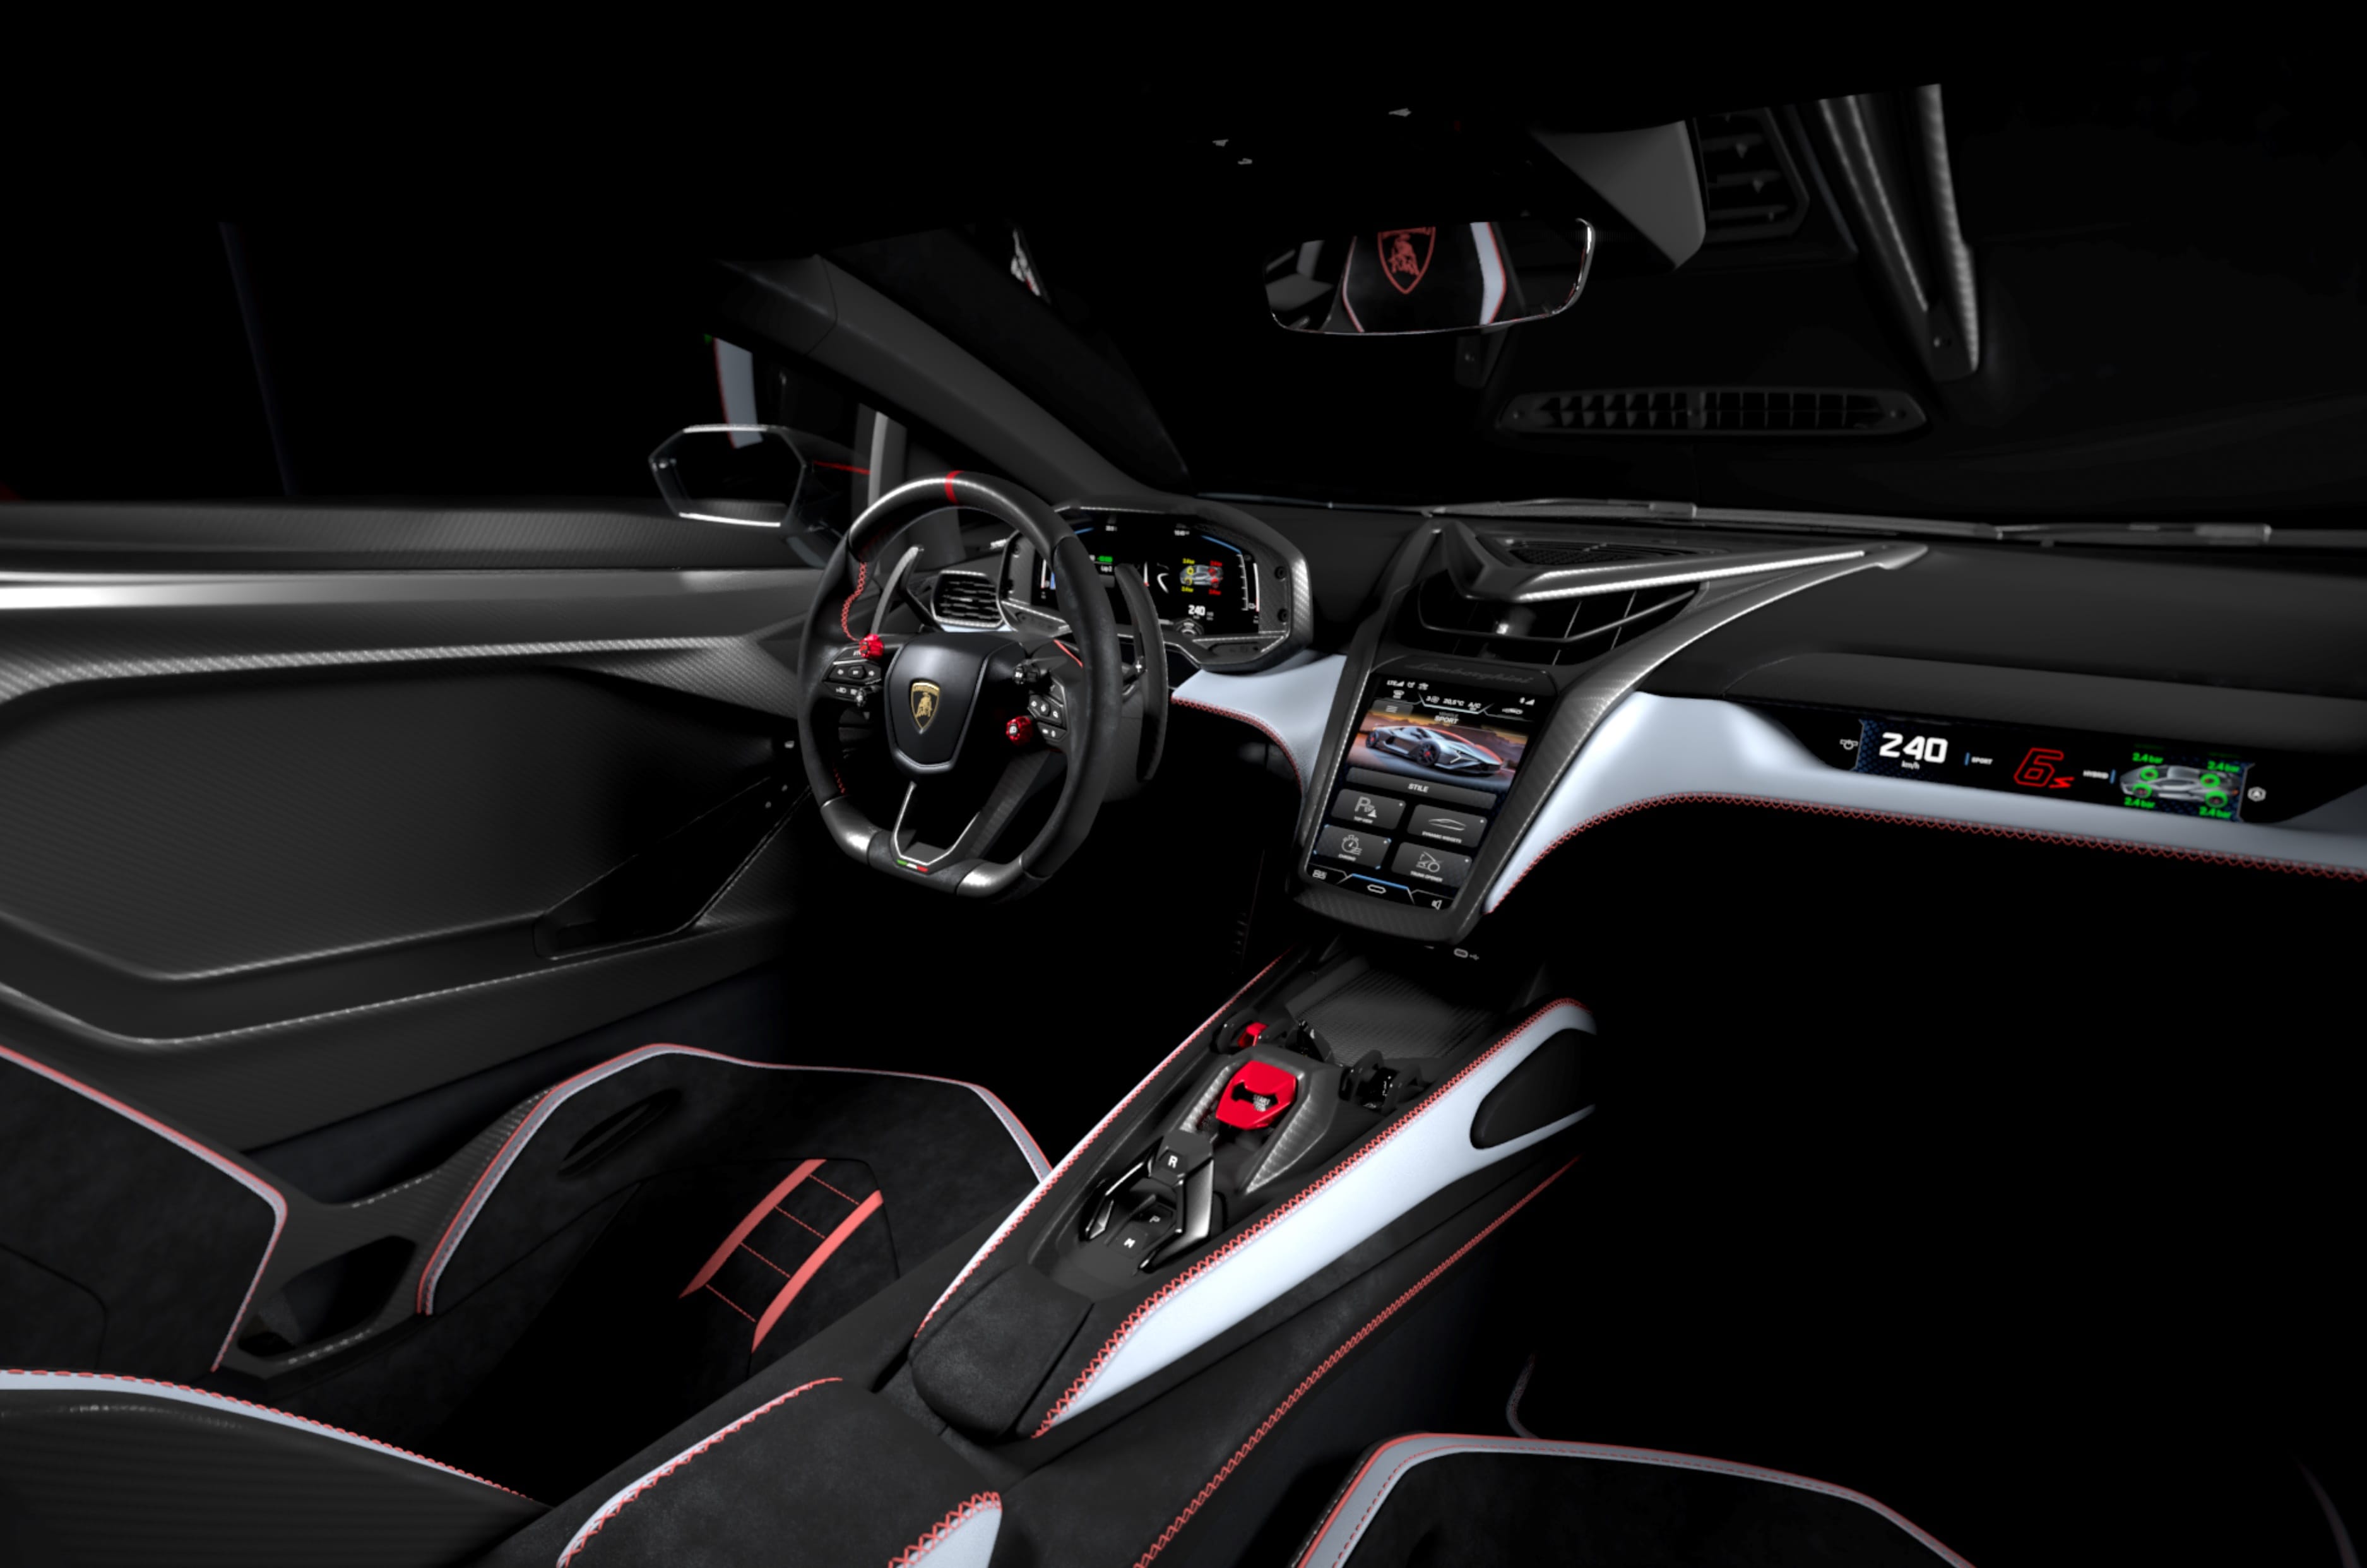
The Revuelto SV’s interior layout is largely unchanged from that of the standard version, but you do get new racing bucket seats, SV badging, and an expanded roster of upholsteries and colour options.

38 साल की उम्र में पुणे के इस कपल ने बनाया अपना रिटायरमेंट प्लान, इस एक चीज ने डिसाइड किया इनका FIRE फॉर्म्युला

पुणे के रहने वाले 38 साल के एक कपल ने कुल मिलाकर लगभग 11.5 करोड़ रुपये की संपत्ति जमा कर ली है। वे अगले दो-तीन साल और काम करने के बाद जल्दी रिटायर होने के बारे में सोच रहे हैं, क्योंकि काम का बढ़ता दबाव और सेहत की चिंताएं उन्हें अपनी फाइनेंशियल प्राथमिकताओं पर फिर से सोचने के लिए मजबूर कर रही हैं।

इस कपल की कोई संतान नहीं है और वे अभी अपनी जीवनशैली पर सालाना लगभग 22 लाख रुपये खर्च करते हैं। उनकी संपत्ति रियल एस्टेट, भारतीय इक्विटी और म्यूचुअल फंड, अमेरिकी स्टॉक, कैश और रिटायरमेंट सेविंग्स में बंटी हुई है। उनकी मौजूदा संपत्ति के बंटवारे में रियल एस्टेट में लगभग 3.2 करोड़ रुपये, भारतीय स्टॉक और म्यूचुअल फंड में 1.8 करोड़ रुपये, अमेरिकी स्टॉक में 5 करोड़ रुपये और कैश व रिटायरमेंट सेविंग्स में 1.5 करोड़ रुपये शामिल हैं।

कपल रिटायरमेंट का फैसला लेने से पहले अगले दो-तीन साल तक काम जारी रखने की योजना बना रहा है। 30 के दशक के आखिर में होने वाले कई अन्य जोड़ों के विपरीत, उन्हें बच्चों की उच्च शिक्षा, शादी या परिवार पालने से जुड़े अन्य बड़े खर्चों के लिए रिटायरमेंट फंड नहीं बनाना है।

हालांकि, उनकी फाइनेंशियल जिम्मेदारियां खत्म नहीं हुई हैं। उनके माता-पिता रिटायर हो चुके हैं और उन पर निर्भर हैं, जिसका मतलब है कि कपल इतनी फाइनेंशियल सिक्योरिटी बनाए रखना चाहता है कि अगर वे जल्दी काम करना छोड़ भी दें, तो भी वे अपने माता-पिता की आराम से मदद कर सकें।

X पर शेयर की गई जानकारी के अनुसार, सबसे बड़ी चिंता उनकी अपनी सेहत है। उनकी नौकरियों में लंबे समय तक काम करना, लगातार दबाव और काम से बहुत कम छुट्टी मिलना शामिल हो गया है। इस कपल को अपनी जीवनशैली के कारण सेहत पर असर भी दिखने लगा है, जिससे वे यह सोचने पर मजबूर हो गए हैं कि क्या इतनी तेज़ी से और ज़्यादा पैसा कमाते रहना सही है।

अब चर्चा इस बात पर हो रही है कि “हम और कितना कमा सकते हैं?” के बजाय “कितना पैसा काफ़ी है?” पत्नी की बात को पोस्ट में इस तरह बताया गया- “हमने अपनी जवानी का समय पैसा बनाने में बिताया। शायद अब समय आ गया है कि हम इसमें से कुछ पैसा अपनी ज़िंदगी पर खर्च करें।”

यह जानकारी X पर अमित अरोड़ा नाम के यूज़र ने शेयर की। उन्होंने कपल की आर्थिक स्थिति को तो शानदार बताया, लेकिन सवाल उठाया कि क्या उनका असली मकसद ज़्यादा नेट वर्थ (कुल संपत्ति) बनाना होना चाहिए या ज़्यादा आज़ादी पाना।

“38 साल की उम्र में ऐसी स्थिति में होना शानदार है। दिलचस्प बात यह है कि वे आज़ादी चाहते हैं या ज़्यादा पैसा। ऐसी क्या चीज़ है जो उन्हें रिटायरमेंट में देरी करने पर मजबूर कर सकती है?” इस पोस्ट ने एक बहस छेड़ दी है कि क्या 11.5 करोड़ रुपये का फंड इस कपल के लिए 30 के दशक के आखिर में काम बंद करने के लिए काफ़ी है, खासकर उनके सालाना खर्च, माता-पिता की मदद करने की संभावना और निवेश के कई दशकों तक चलने की ज़रूरत को देखते हुए।

एक कमेंट करने वाले ने कपल की लोकेशन के हिसाब से उनके जमा किए गए पैसे (कॉर्पस) के साइज़ पर सवाल उठाया और उनकी इनकम के बारे में पूछा- “38 साल की उम्र में 11.5 करोड़ की नेट वर्थ बहुत बड़ी बात है… वो भी पुणे में… वहां की सैलरी देखकर सुखद आश्चर्य हुआ… क्या उनकी सालाना इनकम पता चल सकती है ताकि मैं यह देख सकूं कि मेरा बेंचमार्क कितना खराब रहा है?”

दूसरों ने कपल के बच्चे न करने के फ़ैसले और आगे चलकर उनकी ज़िंदगी कैसी होगी, इस पर ध्यान दिया। एक कमेंट में लिखा था- “जब वे बूढ़े हो जाएंगे, तो उनसे बात करने के लिए कुत्ते होंगे।” एक और कमेंट करने वाले ने सवाल उठाया कि क्या कपल की मौजूदा फाइनेंशियल स्थिति उन्हें बिना नौकरी के अगले चार दशकों तक सहारा देने के लिए काफ़ी होगी और उनकी इन्वेस्टमेंट स्ट्रेटेजी पर चिंता जताई।

“मौजूदा आंकड़े बिना काम किए अगले 40 साल गुज़ारने के लिए ठीक नहीं हैं और एसेट एलोकेशन वेटेज और एस्टेट प्लानिंग पर फिर से काम करने की ज़रूरत है।” एक ज़्यादा आलोचनात्मक प्रतिक्रिया में सवाल उठाया गया कि क्या कपल को बाद में बच्चे न होने का पछतावा हो सकता है और तर्क दिया गया कि उन्हें जल्दी रिटायर होने के बजाय काम करते रहना चाहिए। “रिटायर होने के बाद वे क्या करेंगे? बच्चे न होने का पछतावा? जितना कम समय इसके लिए होगा, उतना ही अच्छा है। इसलिए उन्हें कड़ी मेहनत करते रहना चाहिए ताकि वे अपने उस भयानक फ़ैसले के बारे में न सोचें।” यह बहस FIRE (फाइनेंशियल इंडिपेंडेंस, रिटायर अर्ली) अप्रोच से जुड़े एक बड़े सवाल को सामने लाती है, जिसमें लोग इतनी संपत्ति और इन्वेस्टमेंट इनकम जमा करने का लक्ष्य रखते हैं कि पेड एम्प्लॉयमेंट (नौकरी) ज़रूरी न रहे।

Mercedes-Benz India unveils AI-powered car scanner for servicing

Mercedes-Benz India unveils AI-powered car scanner for servicing

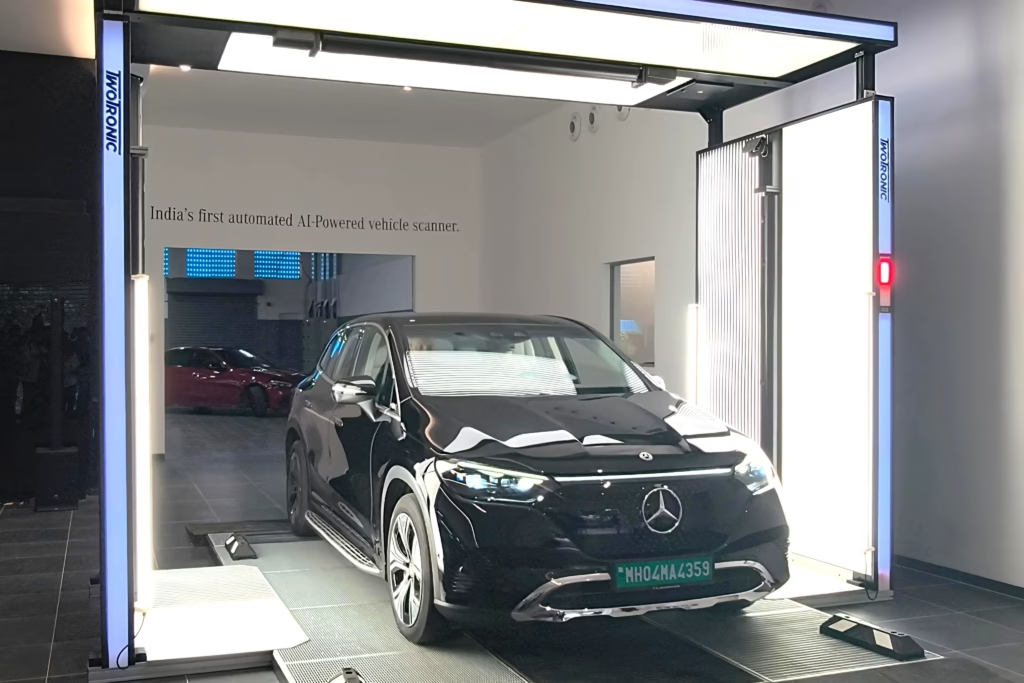
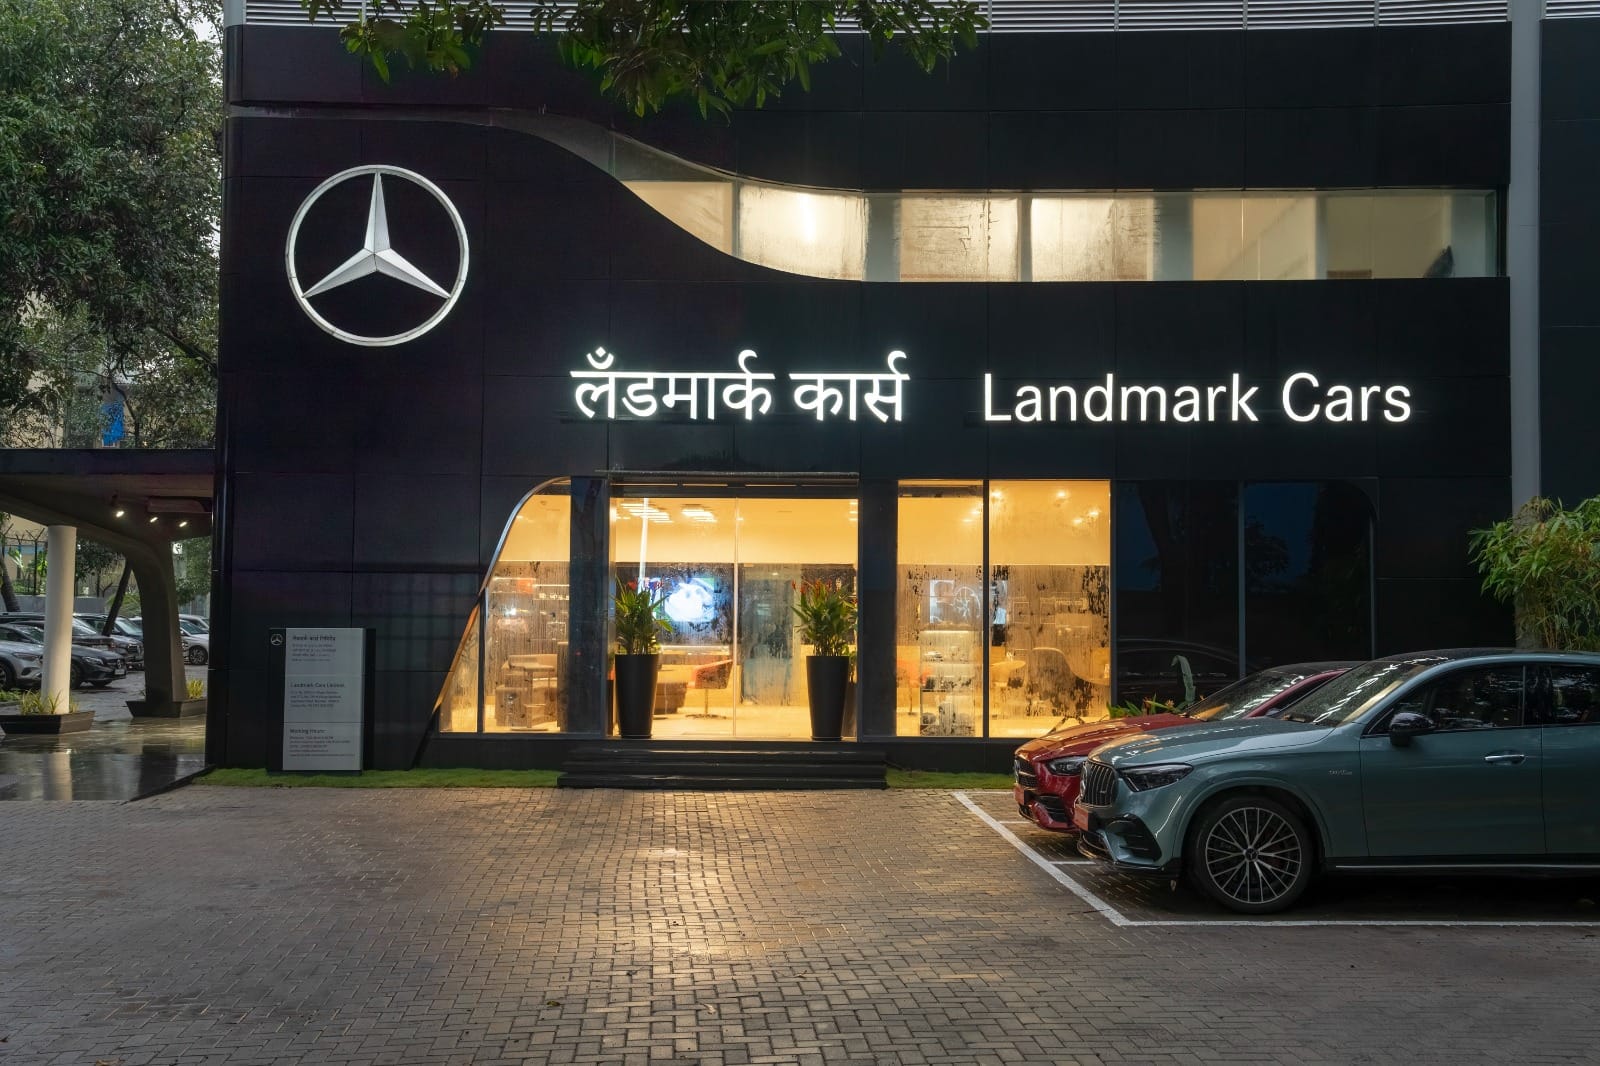
Mercedes-Benz India has revealed an AI-powered device that enables quicker vehicle inspection upon entry to its service centre. Dubbed the XENTRY Scanner, the service debuted at the brand’s newly established centre by Landmark Cars in Jogeshwari, Mumbai.

  1. Mercedes’ first AI-powered car scanning system arrives at its largest workshop in Mumbai.
  2. Uses a 360-degree camera system to identify damage on a car’s exterior.
  3. Service Select debuts as a new scheme for older Mercedes vehicles.

Currently, the scanner is the only one of its kind in India at this service centre, which spans around 58,000 sq. ft., making it the brand’s largest in Mumbai. This facility consists of 16 preventive maintenance and general repair bays, 9 body and paint bays and 9 supporting bays, supported by a dedicated 6,000 sq. ft. spare-parts area.

How does Mercedes’ XENTRY Car Scanner work?

The brand calls it an MRI scanner for its cars

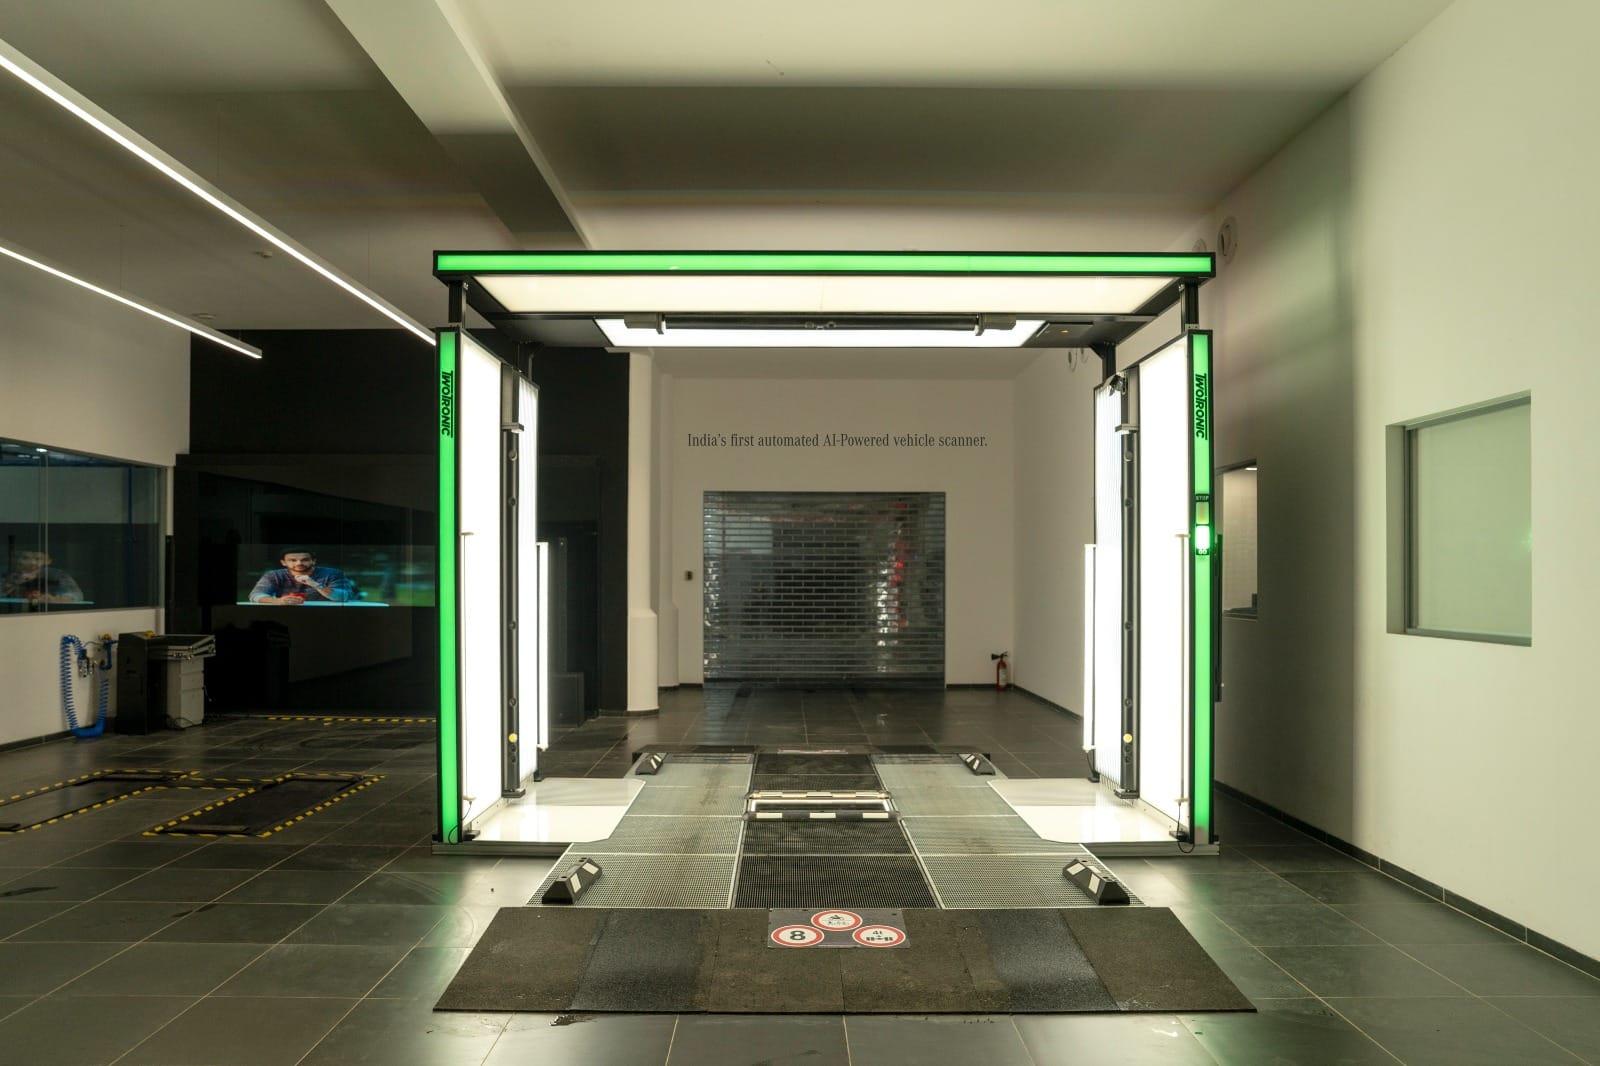
Mercedes-Benz’s XENTRY car scanner.

As the car enters the workshop, it is made to pass through the XENTRY scanner. The scanner utilises a 360-degree high-resolution camera system comprising 13 cameras and a LiDAR sensor. Images of the car are captured and analysed across four categories: body, underbody, windshield and tyres. The system captures 150 images within 3 to 5 seconds and then transmits the data to the Mercedes-Benz cloud.

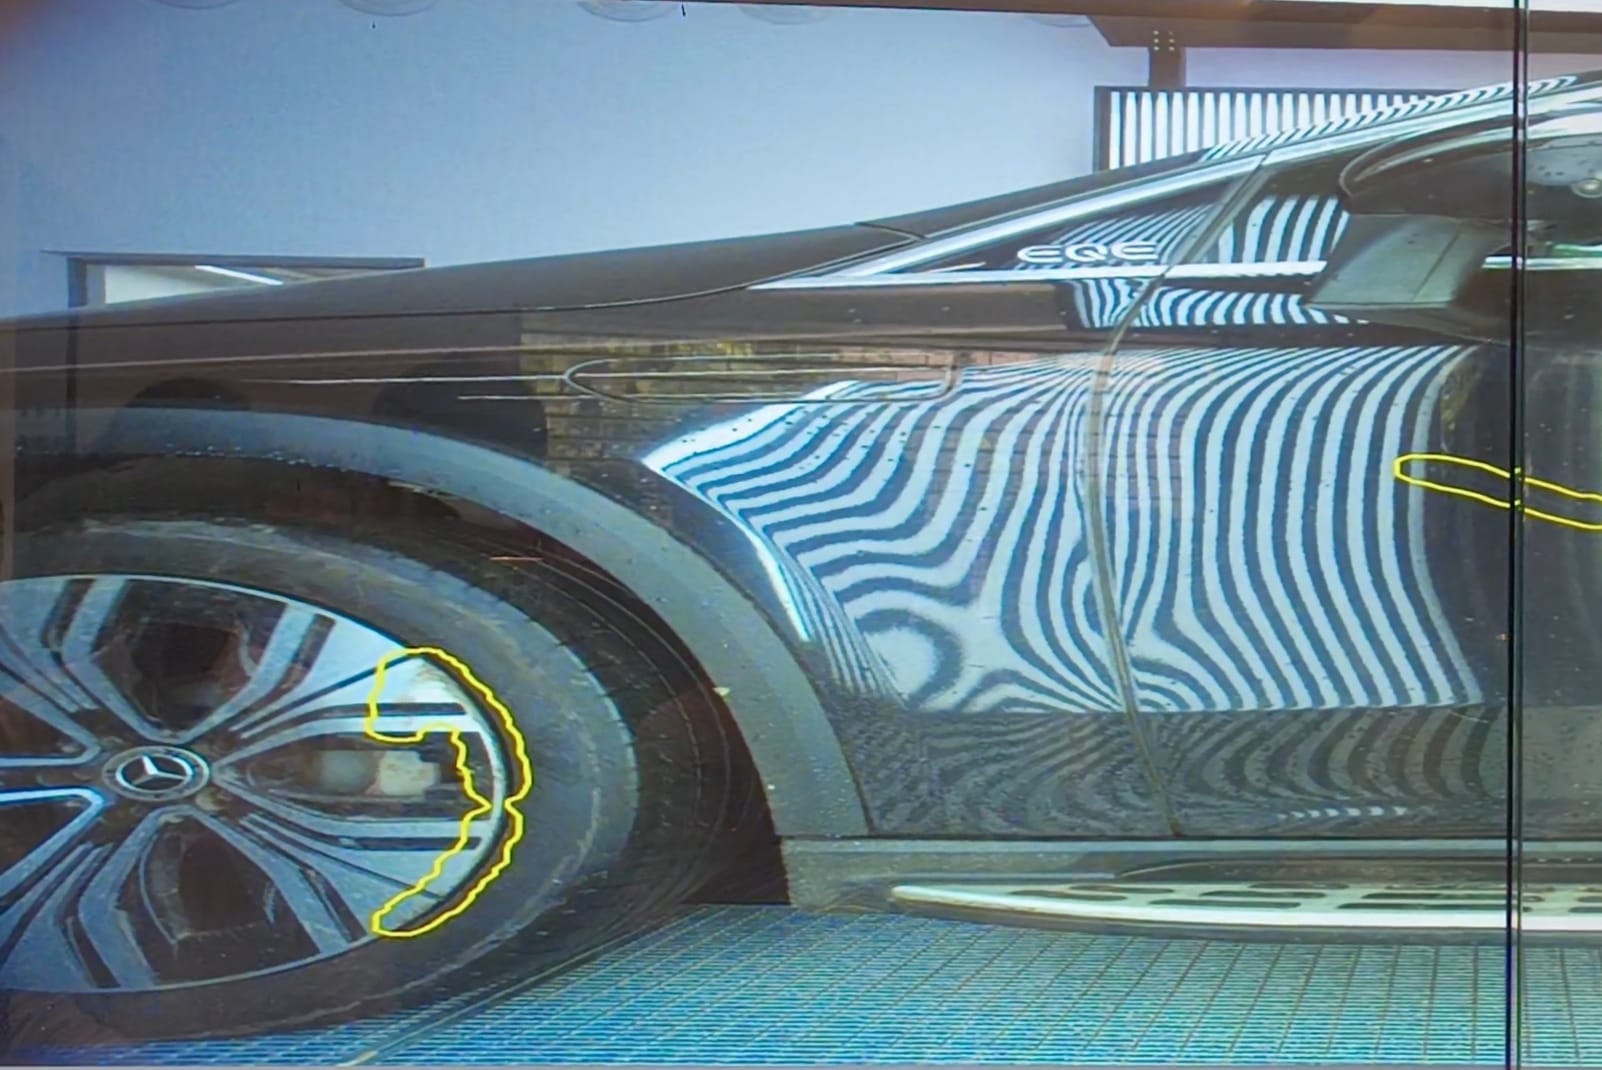
Artificial intelligence then comes into play, identifying every kind of damage on the car’s exterior, even the ones that aren’t visible to the naked eye. It also provides in-depth tyre information, including their health, tread depth and braking performance. To maintain privacy, the system does not capture images of the driver. The findings are added directly to the job card of the particular car without manual entry, enabling better co-ordinated workshop processes. Mercedes says the process is entirely paperless, reducing walking distances, waiting times and paperwork that traditionally accompanied service reception.

Speaking about the thinking behind such initiatives, Mr Santosh Iyer, MD and CEO, Mercedes-Benz India said, “Productivity has to be the core. Reason being, from a real estate perspective, you need to turn cars around faster, while initiatives like the car scanner are more of a productivity enhancement. But on the customer side too, they expect the car to be turned around quickly, which is a pure mobility requirement for the customer.”

Through AI, external wear and tear is automatically detected by the XENTRY car scanner.

Next, a service advisor receives all the information on a tablet and informs the customer of a detailed list of vehicle wear and tear. It is then up to the customer to approve servicing of the concerned parts on the spot. The brand claims that a digital record of service status eliminates the need for manual inspections by the customer.

Interestingly, Landmark’s own internal research points to a shift in service revenue coming from EV adoption growth. “Landmark did a study of the service cost of EV versus ICE. Over the last six months, they’ve seen that the cost is the same in terms of maintenance. But this isn’t coming from maintenance; it’s coming from the body shop. More of the latter is done on EVs compared to ICE cars, said Mr Iyer.

At around 58,000 sq ft, the Landmark Cars workshop in Jogeshwari is the brand’s largest in Mumbai.

India now adds to the list of countries to offer Mercedes’ XENTRY scanner. Previously, the tech was available in international markets like Germany, Italy, Korea, the Netherlands, Switzerland, and Turkey. Furthermore, Mercedes-Benz plans to expand to more than 20 ‘world-class’ luxury outlets in 2026 in India, supported by an investment of more than Rs 450 crore by franchise partners over the next two years.

Mercedes Service Select: A service plan for older Mercedes vehicles

While Mercedes-Benz provides a standard 3-year warranty on new cars, it has also introduced a new service scheme for older vehicles. Called ‘Service Select’, Mercedes cars 7 years or older are eligible for this service. The scheme enables up to 25 percent savings for periodic service and brake care, a 2-year warranty on spare parts, benefits of its ‘Mobilio Lite’ service facility, and residual value protection of the vehicle.

With inputs from Hormazd Sorabjee

Marc Philipp Gemballa Marsien GT revealed with over 830hp

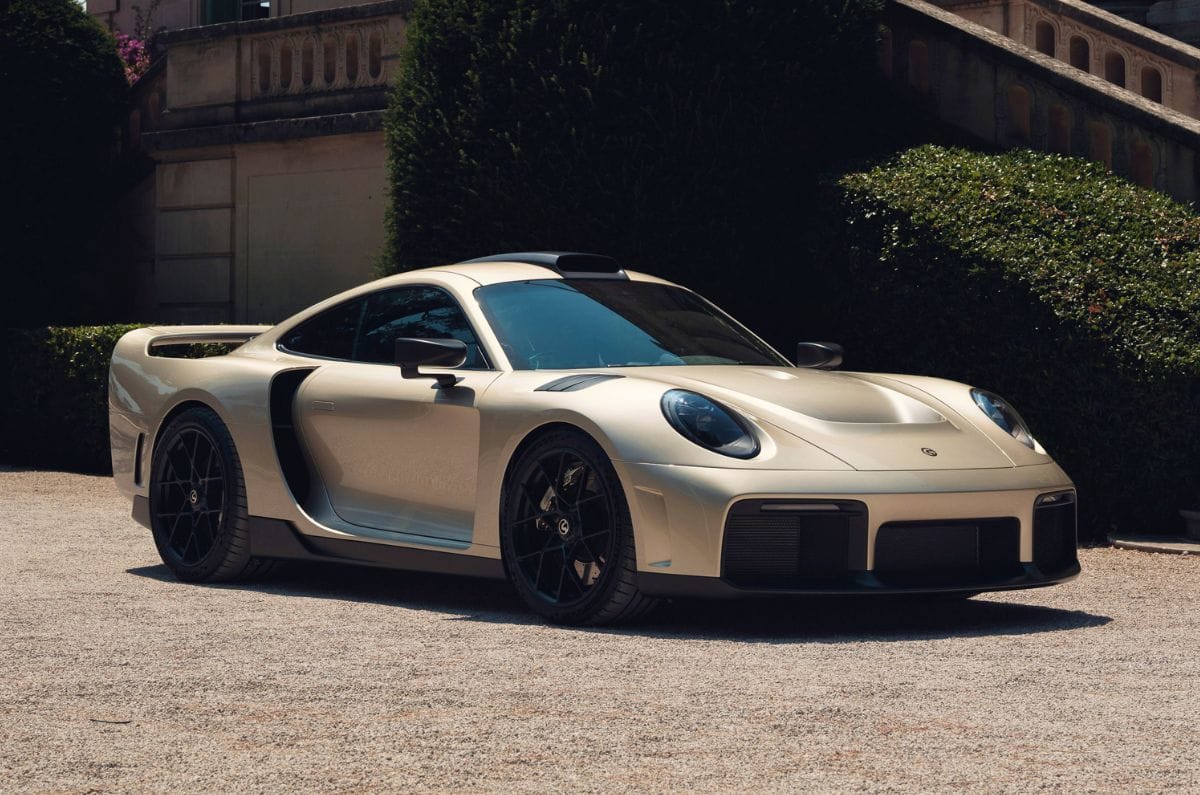
Marsien GT front quarter

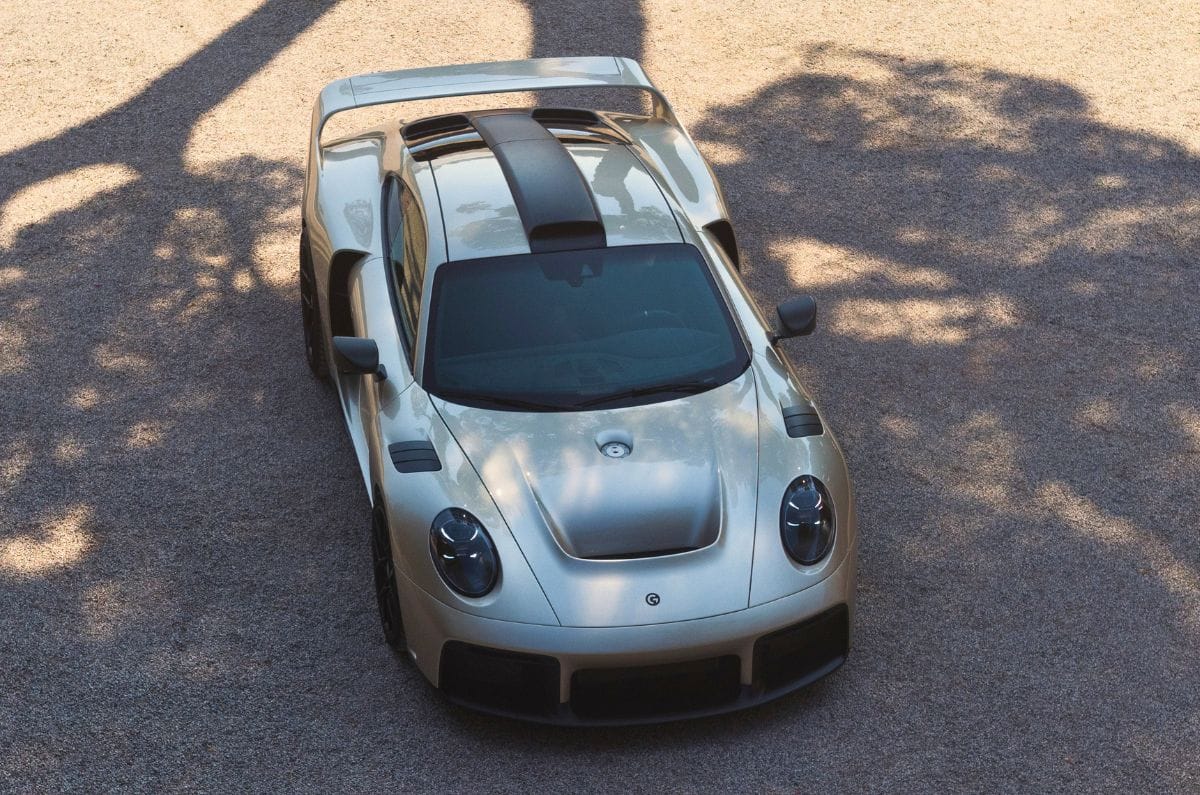
Based on the 992-series Porsche 911 Turbo S, the Marsien GT has been revealed ahead of its global premiere at the Pebble Beach Concours d’Elegance on August 13, 2026. Produced by Marc Philipp Gemballa GmbH, the Marsien GT is the company’s second limited-edition model – the first was the desert-focused Marsien of 2021. Including 40 units of the latter and another 30 examples of the grand tourer (GT), there’ll be a total of 70 Marsiens produced. The 70-unit combined production run honours the 70th anniversary of Uwe Gemballa, Marc Philipp Gemballa’s father, the marque stated.

  • Has a carbon-fibre exterior, active aero and custom colour options
  • Gets Michelin Pilot Sport Cup 2 tyres and an Akrapovic titanium exhaust system
  • Revised six-cylinder boxer engine outputs over 830hp and 930Nm

Marsien GT design and interior

Marsien GT front

The exterior styling of the Marsien GT is the work of French automotive designer Alan Derosier. It features a one-off four-layer metallic colour called Anniversary Liquid Champagne Gold, in honour of the 70th anniversary of Uwe Gemballa. The colour is applied at a paint studio that the brand claims can “fulfil the most daring customer colour requests.” The brand also says that the Marsien GT has a full carbon-fibre exterior, consisting of over a hundred individual carbon-fibre components. The front axle-lift system has been retained from the 911 Turbo S, though.

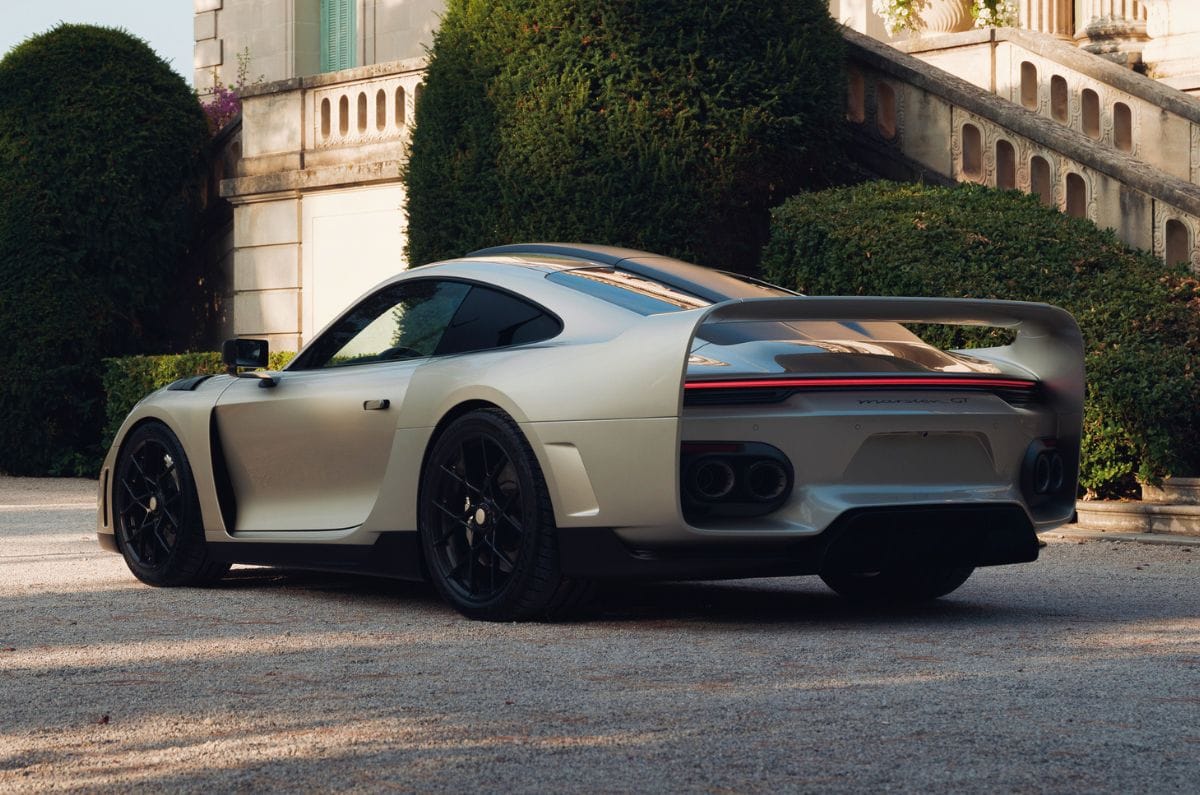
Marsien GT rear quarter

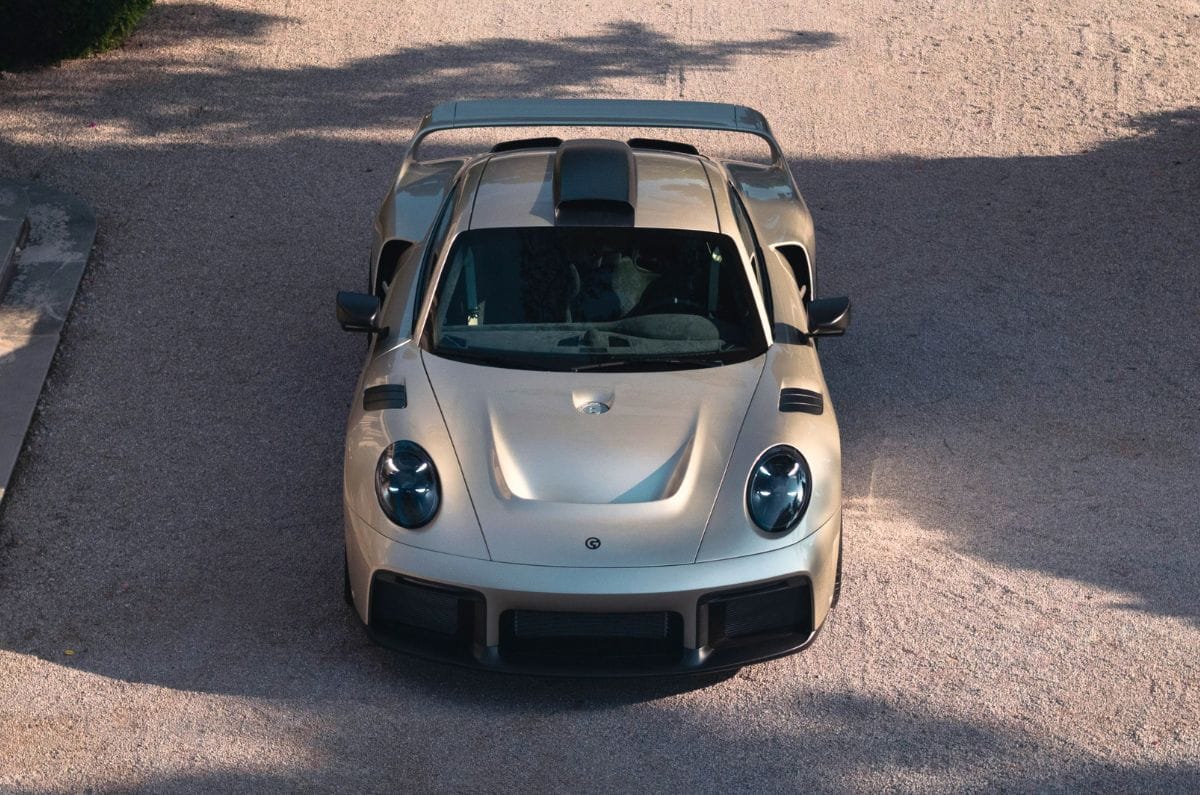
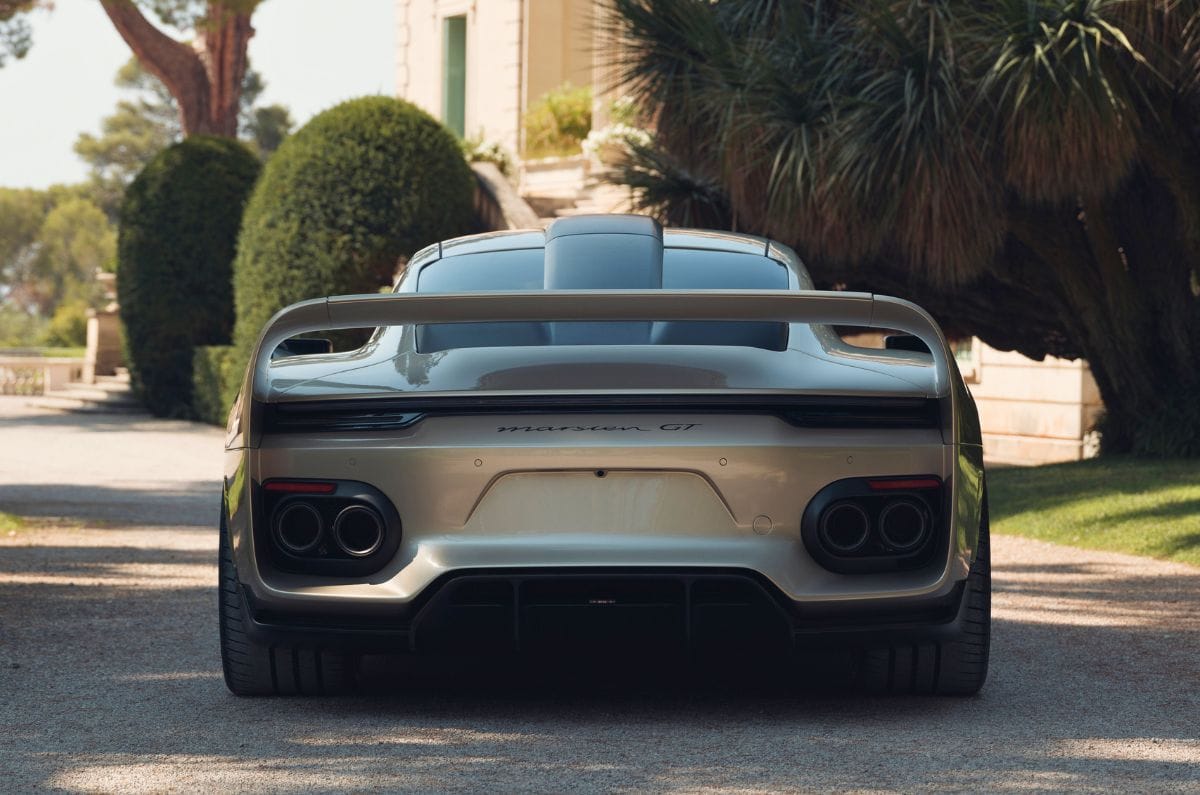
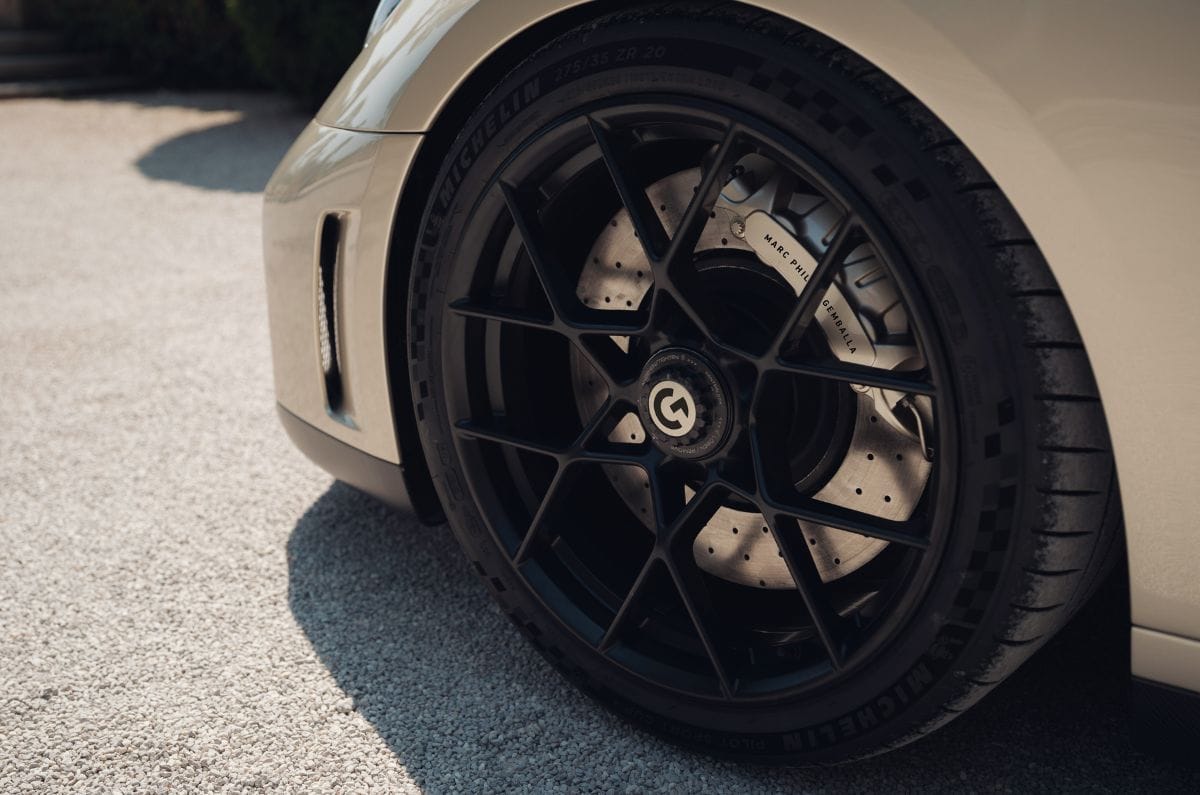
Noticeably different elements over the donor vehicle include the uniquely shaped outside rearview mirrors (ORVMs), a top-mounted scoop, active air flaps on the front fenders, ram-air intakes, side skirts with integrated air channels, and a large active rear wing whose design is reminiscent of the Porsche 959’s. Adding to these are the forged aluminium wheels wrapped in Michelin Pilot Sport Cup 2 tyres, an Akrapovic titanium exhaust system, and a carbon-fibre underfloor. All these lightweight measures ensure weight savings of 75kg over the donor vehicle, whilst the active aero features cool the brakes and reduce turbulence from the wheel arches, as per the brand.

Marsien GT interior

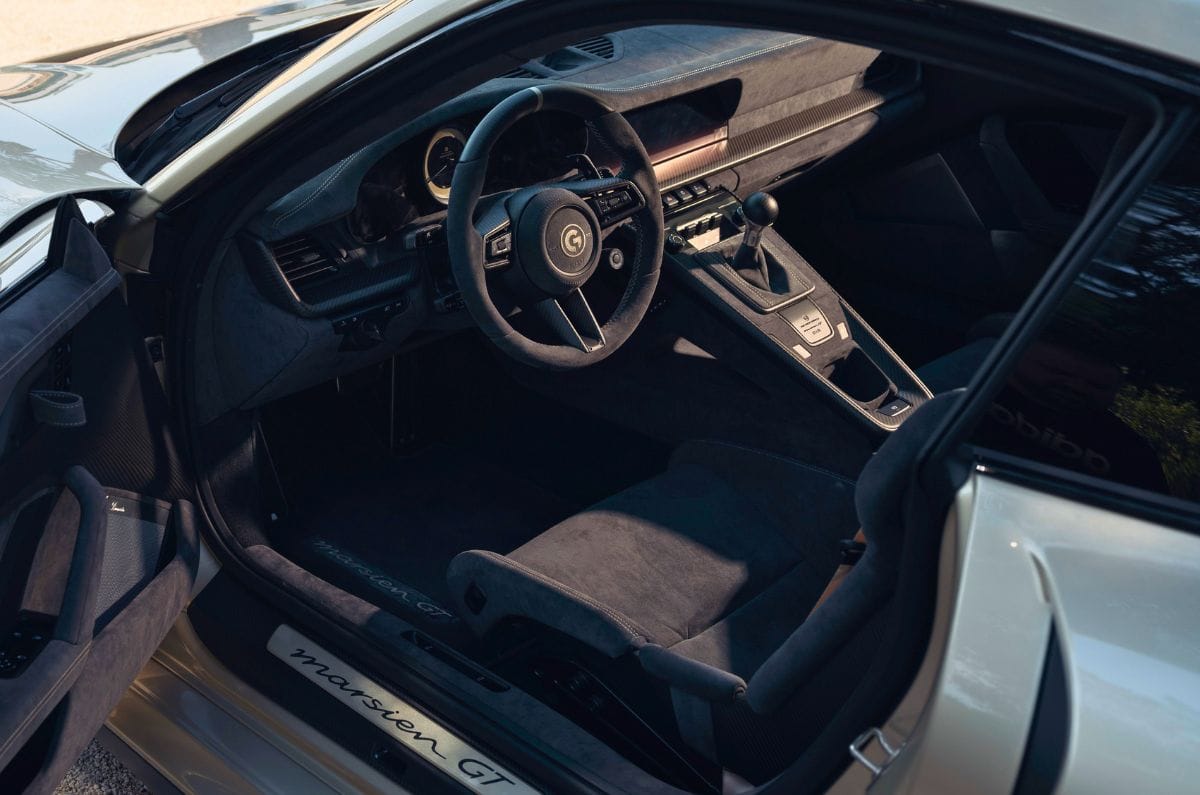
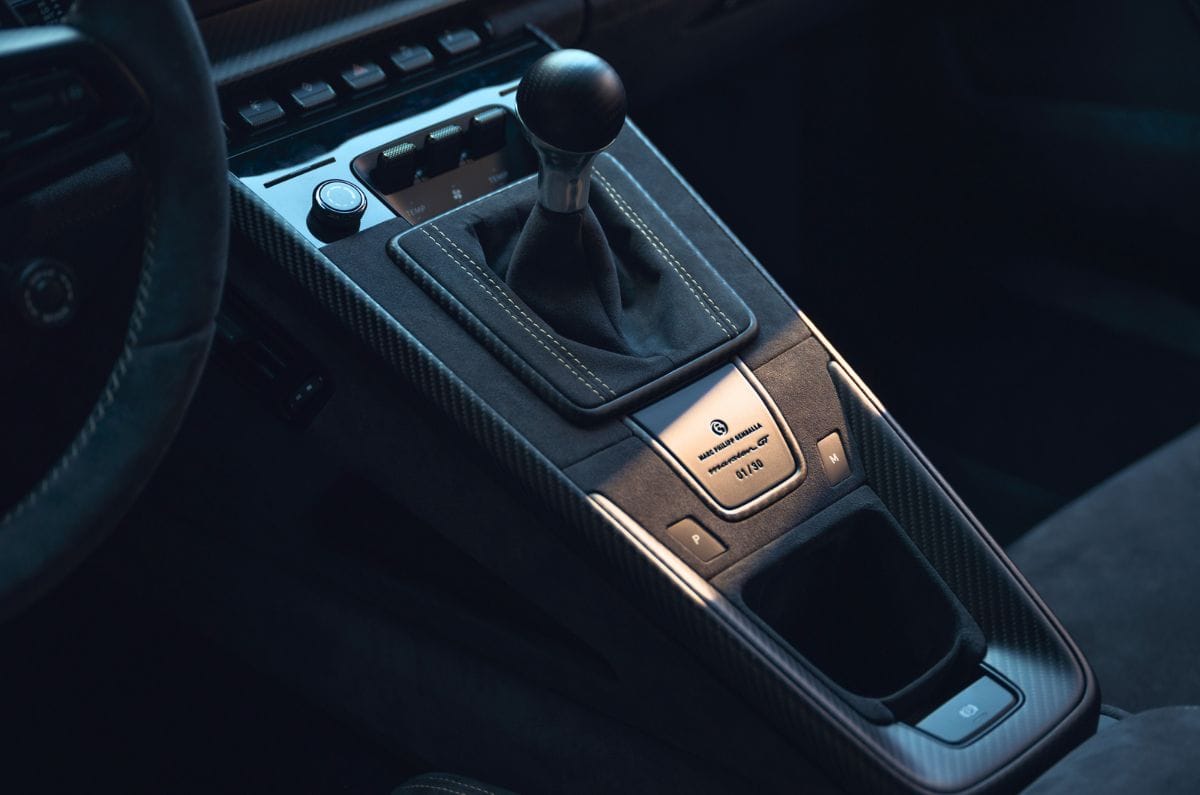
Some of the stand-out design elements inside the Marsien GT are visible along the centre console, which itself is raised over what’s seen in the standard 911 Turbo S, but there’s also an aluminium gear lever that’s inspired by the unit found in the Carrera GT. Customers can opt this gear lever to be covered in either exposed carbon or mahogany wood, instead of softer materials like leather or Alcantara. The interior also features hand-stitched brand logo on the steering wheel, headrests, armrest and floor mats.

Marsien GT gear lever

The centre console also sports a metal badge displaying the individual production number of each vehicle. Apart from the carbon bucket seats and dark grey Alcantara, the interior of this launch-ready example features champagne accents for much of the stitching, plus on the seatbelts and within the instrument cluster. There are also matte carbon-fibre accents and an Alcantara-trimmed roll bar. According to the brand, customers can purchase a carbon-fibre interior package that adds even more exposed carbon-fibre elements.

Marsien GT powertrain and suspension

Marsien GT rear

Porsche engine specialist RUF Automobile is key behind the powertrain of the Marsien GT. Uwe Gemballa and RUF Automobile have collaborated to produce powertrains for various vehicles in the 1980s, said Marc Philipp Gemballa GmbH. Compared to the 911 Turbo S, the six-cylinder boxer engine of the Marsien GT features a remapped ECU (engine control unit) and enhanced variable-geometry turbochargers – this results in a claimed output of over 830hp and 930Nm of torque. The 8-speed dual-clutch automatic transmission (DCT) has also been revised to handle the extra power and torque.

The brand is currently working on a second-stage engine upgrade option, which will take the output to over 900hp. Even in its current avatar, the Marsien GT has a claimed top speed of 330kph and a 0-97kph sprint time of 2.4 seconds. That said, the Marsien GT retains the all-wheel-drive (AWD) system of the Porsche 911 Turbo S.

Marsien GT wheels

However, Marc Philipp Gemballa GmbH has partnered with KW Automotive for its car’s suspension needs. It claims that the new double-wishbone front setup has been specifically developed for the Marsien GT, with its electronically controlled dampers capable of adjusting and responding to changing road conditions within just 20 milliseconds. This suspension setup ensures that the Marsien GT offers precise control without sacrificing ride comfort that’s expected of a grand tourer, according to the brand.

Marsien GT price

Marsien GT exterior top-down

The Marc Philipp Gemballa Marsien GT will be making its world premiere during the upcoming 2026 Monterey Car Week at the Pebble Beach Concours d‘Elegance in California, USA. Production will begin in 2027, with first customer deliveries commencing later the same year. The starting price of the Marsien GT will be EUR 770,000, not including the cost of the donor vehicle, i.e., the 992 Porsche 911 Turbo S. For reference, the latter starts at EUR 271,000 in Germany.

Also read

Mahindra BE 6 Sporteq teased with new triple screen setup

What to expect from Mahindra’s 2026 Independence Day event

Maruti Victoris gets up to Rs 1.35 lakh discount in August 2026

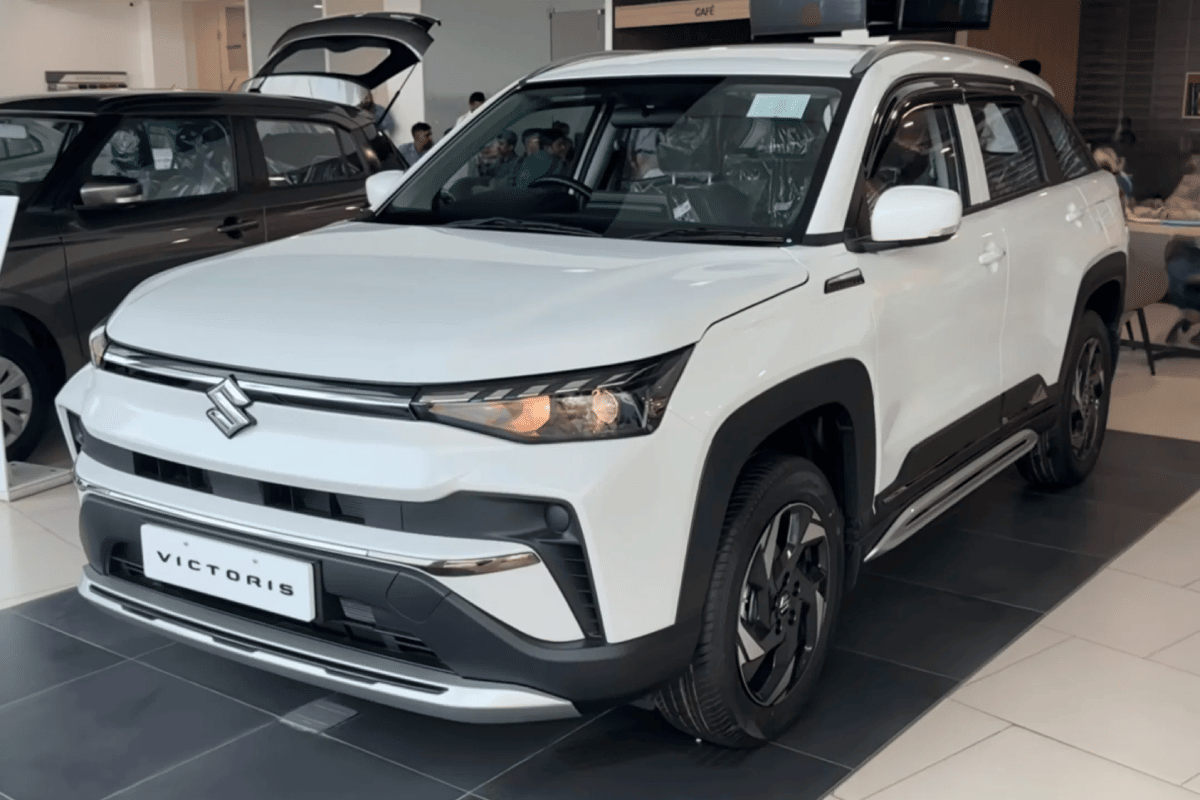
Maruti Victoris

Maruti Suzuki is offering discounts across much of its Arena line-up, including the Victoris, Swift, Wagon R, Alto K10, Celerio, S-Presso and Eeco, in August 2026. The highest benefits are available on the Victoris, with savings of up to Rs 1.35 lakh. These offers comprise cash discounts, exchange or scrappage bonuses, loyalty benefits and institutional discounts, depending on the variant.

Disclaimer: Offers may vary by city and are subject to stock availability. Check with your nearest dealer for exact details.

Maruti Victoris discounts in August 2026

Up to Rs 1.35 lakh off

The Victoris strong hybrid attracts the highest benefits this month, with total discounts of up to Rs 1.35 lakh. These include a Rs 20,000 cash discount, an exchange bonus of up to Rs 75,000 or a Rs 45,000 scrappage bonus, a Rs 30,000 loyalty upgrade bonus and a Rs 10,000 institutional discount.

Petrol and CNG variants, meanwhile, are available with benefits of up to Rs 85,000. Both are eligible for an exchange bonus of up to Rs 55,000, while customers opting for the scrappage scheme can avail of benefits of up to Rs 25,000 on petrol variants and Rs 20,000 on CNG variants. These variants also receive a Rs 20,000 loyalty upgrade bonus and a Rs 10,000 institutional discount.

Priced between Rs 10.50 lakh and Rs 19.99 lakh, the Victoris rivals the Hyundai Creta, Kia Seltos, Tata Sierra and Honda Elevate.

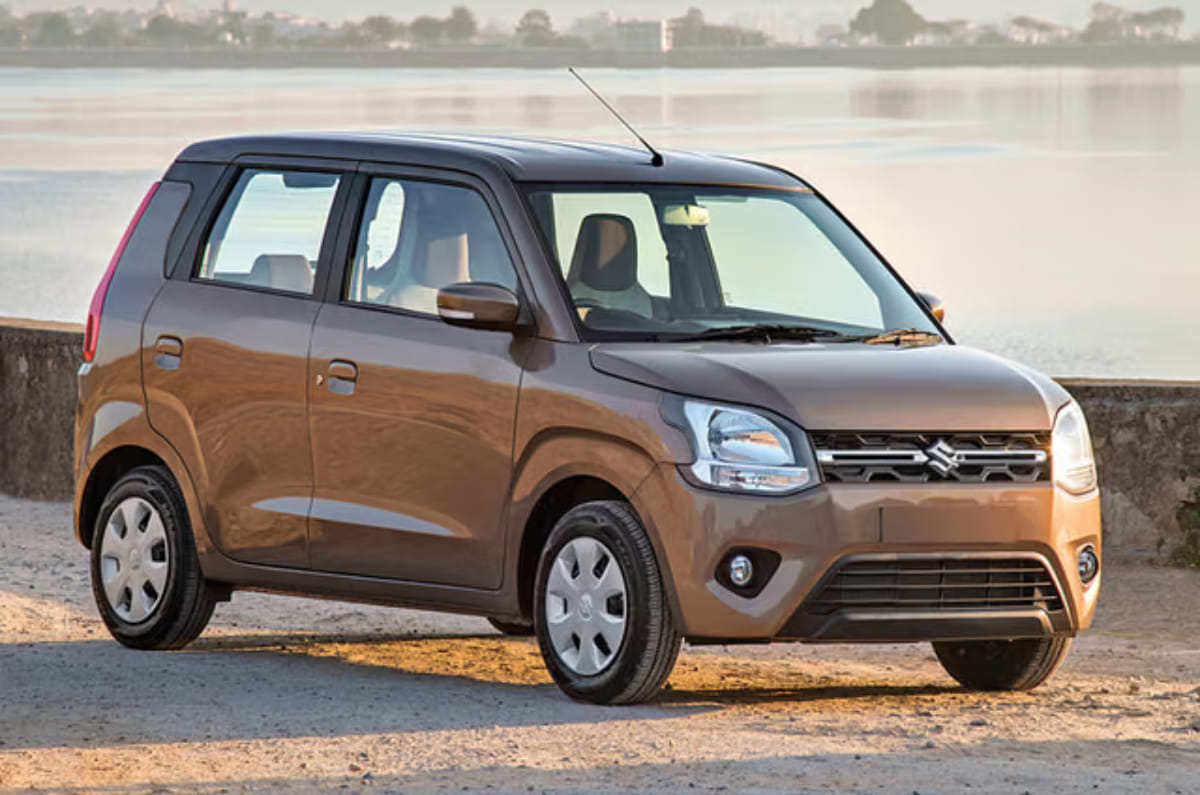
Maruti Wagon R discounts in August 2026

Up to Rs 52,500 off

The Wagon R is available with benefits of up to Rs 52,500 across its petrol and CNG range. Buyers can avail of a Rs 25,000 cash discount, an exchange bonus of up to Rs 25,000 or a Rs 10,000 scrappage bonus, along with a Rs 2,500 institutional discount.

Priced between Rs 4.99 lakh and Rs 7.24 lakh, the Wagon R rivals the Tata Tiago and Citroen C3.

Maruti Alto K10 discounts in August 2026

Up to Rs 52,500 off

In the Alto K10 line-up, the LXi petrol variant gets the highest benefits of Rs 52,500, while other petrol variants are available with discounts of up to Rs 42,500. Benefits on CNG variants are capped at Rs 37,500.

Depending on the variant, buyers can avail of a cash discount of up to Rs 25,000, an exchange bonus of up to Rs 25,000 or a Rs 10,000 scrappage bonus, and a Rs 2,500 institutional discount. This rival to the Renault Kwid is priced between Rs 3.70 lakh and Rs 5.45 lakh.

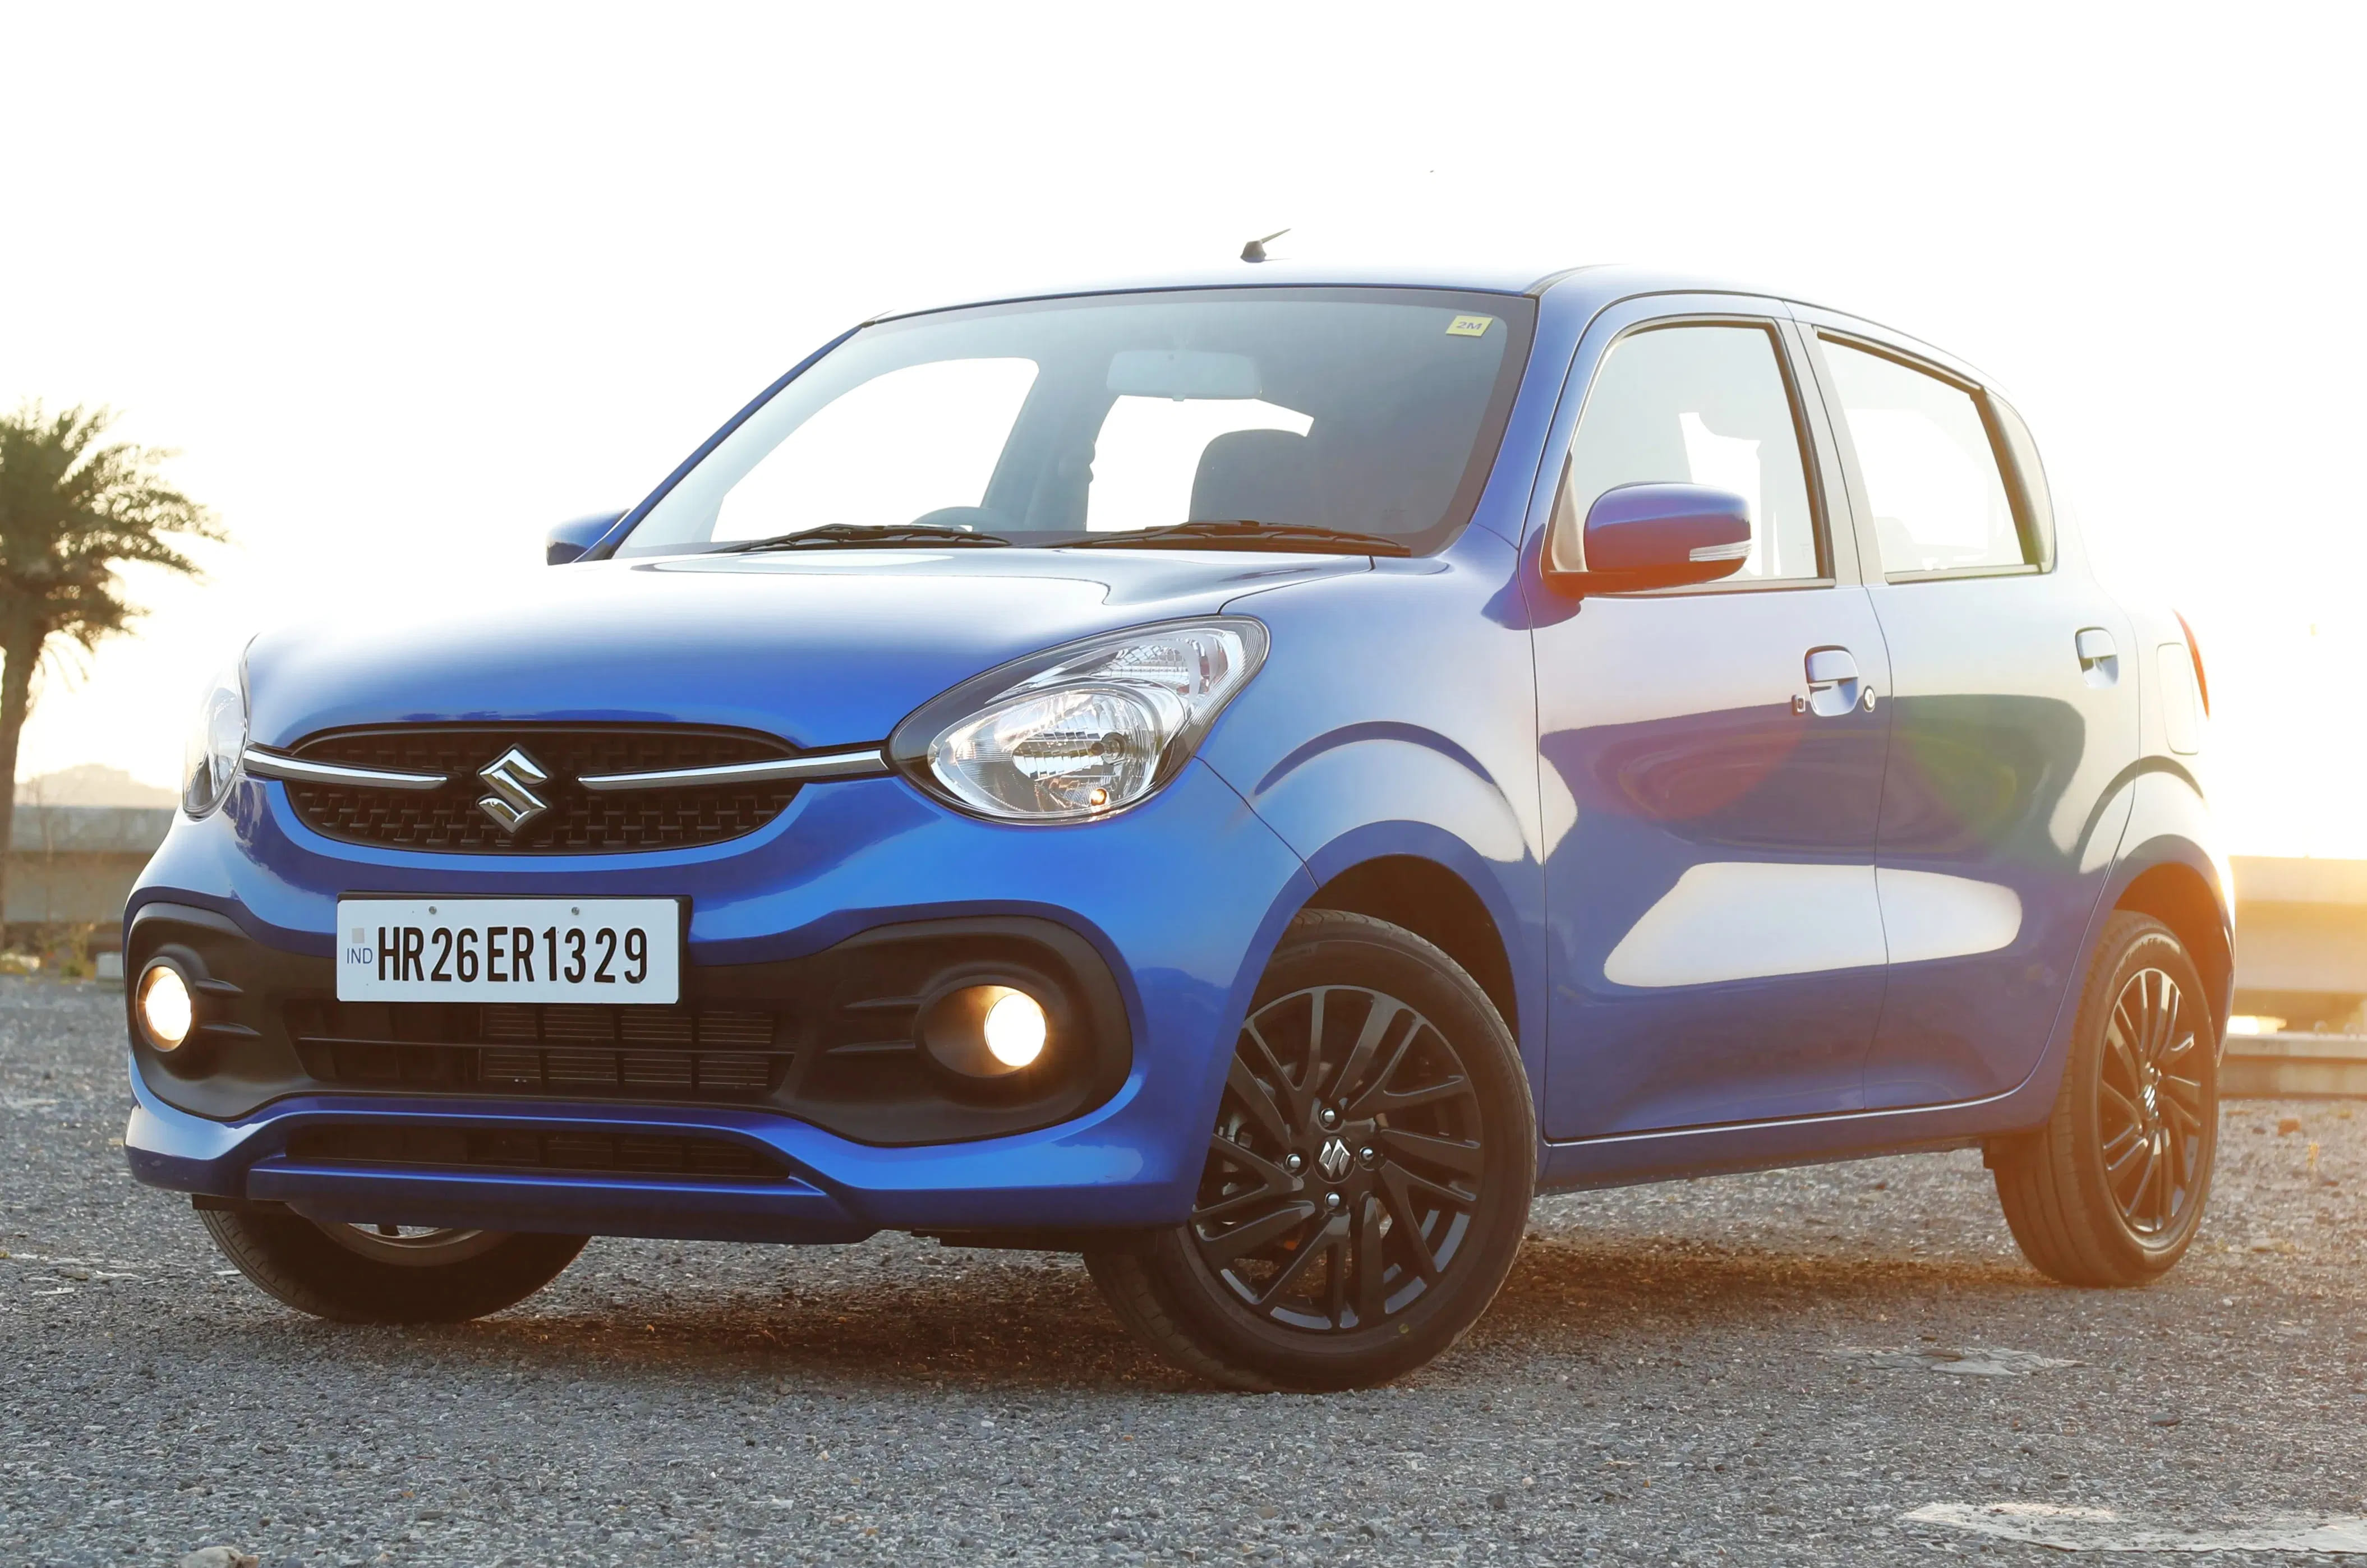
Maruti Celerio discounts in August 2026

Up to Rs 42,500 off

Benefits of up to Rs 42,500 are available across the Celerio range this month. The offer includes a Rs 15,000 cash discount, an exchange bonus of up to Rs 25,000 or a Rs 10,000 scrappage bonus, along with a Rs 2,500 institutional discount. A rival to the Tata Tiago and Renault Kwid, the Celerio has a starting price of Rs 4.70 lakh and costs Rs 6.73 lakh for the top-spec variant.

Maruti Eeco discounts in August 2026

Up to Rs 42,500 off

Petrol variants of the Eeco receive benefits of up to Rs 42,500, while CNG versions are eligible for discounts of up to Rs 32,500. Petrol models get a Rs 15,000 cash discount, whereas CNG variants receive Rs 5,000. Both are offered with an exchange bonus of up to Rs 25,000, along with a Rs 2,500 institutional discount. The Eeco is priced between Rs 5.23 lakh and Rs 6.41 lakh.

Maruti Swift discounts in August 2026

Up to Rs 40,000 off

Petrol variants of the Swift are available with benefits of up to Rs 40,000, including a Rs 10,000 cash discount, an exchange bonus of up to Rs 25,000 or a Rs 10,000 scrappage bonus, and a Rs 5,000 institutional discount. CNG variants receive lower benefits of up to Rs 30,000, as they are not eligible for a cash discount this month.

The Swift is priced between Rs 5.79 lakh and Rs 8.69 lakh and rivals the Hyundai Grand i10 Nios and Tata Tiago.

Maruti S-Presso discounts in August 2026

Up to Rs 37,500 off

All variants of the S-Presso are being offered with benefits of up to Rs 37,500. Buyers can avail of a Rs 10,000 cash discount, an exchange bonus of up to Rs 25,000 or a Rs 10,000 scrappage bonus, and a Rs 2,500 institutional discount. Maruti’s most affordable offering currently, the S-Presso is priced from Rs 3.50 lakh to Rs 5.25 lakh and rivals the Renault Kwid and its stablemate Alto K10.

All prices are ex-showroom, India.

सैलरी नहीं, ये 5 आदतें खाली कर रही हैं आपकी जेब! बेंगलुरु के क्रिएटर ने बताया बचत का तरीका

बेंगलुरु के कंटेंट क्रिएटर अक्षय सीएन ने लोगों का ध्यान बचत से जुड़ी एक अहम समस्या की ओर दिलाया है। उनका कहना है कि कम सैलरी नहीं, बल्कि रोजाना होने वाले छोटे-छोटे खर्च कई बार आर्थिक स्थिति को प्रभावित करते हैं। उन्होंने सोशल मीडिया पर एक वीडियो शेयर कर बताया कि फूड डिलीवरी, कैब राइड, गैरजरूरी शॉपिंग, बेकार सब्सक्रिप्शन और बिना प्लानिंग के वीकेंड खर्च जैसी आदतें धीरे-धीरे बड़ी रकम में बदल जाती हैं।

अक्षय के मुताबिक, ज्यादा कमाई करने वाले लोग भी अगर खर्चों पर नजर नहीं रखते तो बचत नहीं कर पाते। वहीं सीमित आय वाले लोग सही प्लानिंग के जरिए पैसे बचा सकते हैं। उनकी पोस्ट ने सोशल मीडिया पर लोगों के बीच खर्च करने की आदतों और बेहतर वित्तीय प्रबंधन को लेकर चर्चा शुरू कर दी है।

वायरल वीडियो में बताए पैसे खत्म करने वाले कारण

Instagram पेज @bangalore_viral चलाने वाले अक्षय सीएन ने एक वीडियो शेयर कर ऐसी 5 आदतों के बारे में बताया, जो धीरे-धीरे हर महीने की बचत को कम कर देती हैं। इनमें बार-बार ऑनलाइन फूड ऑर्डर करना, कैब पर ज्यादा खर्च, बेवजह खरीदारी, बिना इस्तेमाल वाले सब्सक्रिप्शन और बिना बजट के वीकेंड प्लान शामिल हैं।

‘समस्या सैलरी नहीं, अनदेखे खर्च हैं’

अक्षय ने पोस्ट के कैप्शन में लिखा कि कई लोग सोचते हैं कि सैलरी बढ़ने के बाद बचत शुरू करेंगे। लेकिन उनके मुताबिक, असली फर्क कमाई से ज्यादा पैसों को लेकर जागरूकता का होता है। उन्होंने बताया कि कुछ लोग 40 हजार रुपये कमाकर भी बचत कर लेते हैं, जबकि लाखों की आय वाले लोग भी महीने के अंत में परेशान रहते हैं।

छोटे खर्च कैसे बन जाते हैं बड़ा बोझ

अक्षय ने उदाहरण देते हुए बताया कि एक बार का ₹300 का कैब राइड ज्यादा बड़ा खर्च नहीं लगता, लेकिन महीने में 20 बार लेने पर यही रकम काफी बढ़ जाती है। इसी तरह रोजाना फूड डिलीवरी, सेल के नाम पर खरीदारी और छोटे-छोटे डिजिटल पेमेंट लंबे समय में जेब पर भारी असर डाल सकते हैं।

सब्सक्रिप्शन और वीकेंड खर्च पर भी दी चेतावनी

उन्होंने कहा कि कई लोग ऐसे ऐप्स और सेवाओं के लिए पैसे देते रहते हैं, जिनका इस्तेमाल तक नहीं करते। वहीं हर वीकेंड बाहर जाने की आदत भी बिना प्लानिंग के बजट बिगाड़ सकती है। उनके अनुसार, समस्या बाहर जाने में नहीं बल्कि बिना हिसाब के खर्च करने में है।

30 दिन वाला सवाल बदल सकता है खर्च की आदत

अक्षय ने पैसे बचाने का एक आसान तरीका भी साझा किया। उन्होंने बताया कि कोई भी चीज खरीदने से पहले वह खुद से पूछते हैं,”क्या मैं 30 दिन बाद भी इस खरीदारी से खुश रहूंगा?” उनके मुताबिक, इस एक सवाल ने उन्हें बेहतर वित्तीय फैसले लेने में मदद की है।

सोशल मीडिया पर लोगों ने दी प्रतिक्रिया

अक्षय की पोस्ट पर कई यूजर्स ने सहमति जताई। कुछ लोगों ने कहा कि रोजमर्रा के खर्चों की वजह से महीने के अंत तक पैसे बचाना मुश्किल हो जाता है। वहीं कई यूजर्स ने माना कि बचत के लिए ज्यादा कमाई से ज्यादा खर्चों पर नियंत्रण जरूरी है।

बारिश में समोसे खाने की हुई इच्छा, Swiggy से ऑर्डर किया तो 104 रुपये का बिल देख रह गई हैरान, वायरल पोस्ट पर लोगों ने दिए मजेदार रिएक्शन

ITR Filing 2026 Deadline: 31 जुलाई से पहले ऐसे भरें आयकर रिटर्न, पेनल्टी से बचें

income tax

अगर आपने वित्तीय वर्ष 2025-26 के लिए अपना आयकर रिटर्न (ITR) अभी तक दाखिल नहीं किया है, तो तुरंत सावधान हो जाएं! व्यक्तिगत करदाताओं और वेतनभोगियों के लिए बिना  किसी लेट फीस के ITR फाइल करने की अंतिम तिथि 31 जुलाई 2026 है।


अंतिम समय में इनकम टैक्स पोर्टल पर ट्रैफिक का दबाव बढ़ने से सर्वर स्लो होने या पेमेंट अटकने की समस्या हो सकती है। यदि आप 31 जुलाई की समय सीमा चूक जाते हैं, तो आपको  भारी लेट फीस, ब्याज और कई वित्तीय नुकसान उठाने पड़ सकते हैं।
 

धारा 234F के तहत पेनल्टी (Late Fee Slabs) 

आयकर कानून की धारा 234F के अनुसार, नियत तारीख के बाद रिटर्न (Belated Return) दाखिल करने पर निम्नलिखित जुर्माना लागू होता है:


कुल वार्षिक आय (Total Income) 31 जुलाई के बाद ITR फाइल करने पर लेट फीस

2.5 लाख तक रुपए (मूल छूट सीमा) कोई पेनल्टी नहीं

2.5 लाख से 5 लाख रुपए तक 1,000 रुपए अधिकतम लेट फीस

5 लाख रुपए से अधिक 5,000 रुपए लेट फीस


समय पर ITR न भरने के 4 बड़े नुकसान

1. धारा 234A के तहत ब्याज : यदि आपका कोई टैक्स बकाया है, तो समय सीमा समाप्त होने के बाद आपको बकाए टैक्स पर 1% प्रति माह की दर से ब्याज देना होगा। 
 

2. नुकसान (Losses) को कैरी फॉरवर्ड न कर पाना : शेयर बाजार, फ्यूचर्स एंड ऑप्शंस (F&O) या बिजनेस से हुए नुकसान को अगले वर्षों के मुनाफे से एडजस्ट (Carry Forward) करने का विकल्प समाप्त हो जाता है।
 

3. ओल्ड टैक्स रिजीम का विकल्प बंद: यदि आप पुरानी कर व्यवस्था (Old Tax Regime) चुनना चाहते थे, तो समय सीमा बीत जाने के बाद आप केवल न्यू टैक्स  रिजीम (New Tax Regime) के तहत ही बेलैटेड रिटर्न भर पाएंगे।

4. रिफंड में देरी : यदि आपका TDS कटा है और आप रिफंड के हकदार हैं, तो देर से फाइल करने पर आपका रिफंड अटक सकता है या उसमें काफी देरी हो सकती है।


पोर्टल पर ऑनलाइन ITR फाइल करने की चरणबद्ध प्रक्रिया

समय सीमा समाप्त होने से पहले घर बैठे आधिकारिक पोर्टल (incometax.gov.in) पर आसानी से ITR फाइल करने के लिए इन स्टेप्स का पालन करें:
 

1.ई-फाइलिंग पोर्टल पर लॉगिन करें: PAN और पासवर्ड तैयार रखें।

आधिकारिक वेबसाइट incometax.gov.in पर जाएं। अपनी यूजर आईडी (PAN) और पासवर्ड का उपयोग करके लॉगिन करें।
 

2.File Income Tax Return चुनें:

लॉगिन के बाद मुख्य डैशबोर्ड पर e-File > Income Tax Returns > File Income Tax Return विकल्प पर क्लिक करें।
 

3.आकलन वर्ष (Assessment Year) का चयन करें:

आकलन वर्ष में AY 2026-27 का चयन करें। इसके बाद ऑनलाइन फाइलिंग (Online Mode) चुनें और 'Start New Filing' पर क्लिक करें।
 

4.करदाता स्थिति एवं सही ITR फॉर्म का चुनाव करें:

अपनी स्थिति Individual चुनें। यदि आपकी केवल वेतन, एक मकान संपत्ति या ब्याज से आय है, तो ITR-1 (Sahaj) चुनें।
 

5.AIS और Form 26AS से आंकड़ों का मिलान करें:

अपने फॉर्म 16, AIS (Annual Information Statement) और Form 26AS के आंकड़ों की जांच करें। यदि कोई टैक्स बकाया दिखता है, तो e-Pay Tax  के माध्यम से तुरंत भुगतान करें।
 

6.समीक्षा करें और e-Verify पूरा करें:

अपनी सभी जानकारियों की दोबारा समीक्षा करके Submit पर क्लिक करें। इसके बाद अपने आधार OTP या नेट बैंकिंग का उपयोग करके e-Verification प्रक्रिया तुरंत पूरी  करें (बिना ई-वेरिफिकेशन के ITR अमान्य माना जाता है)।
 

ITR सबमिट करने से पहले अंतिम चेकलिस्ट 

– AIS/TIS की जांच: अपने पोर्टल पर जाकर AIS जरूर डाउनलोड करें और उसमें दर्ज ब्याज, डिविडेंड या शेयर ट्रेडिंग की जानकारी अपने रिकॉर्ड से मिलाएं।

– बैंक खाता वैलिडेट करें: सुनिश्चित करें कि आपका बैंक खाता पोर्टल पर पूर्व-सत्यापित (Pre-validated) है ताकि रिफंड सीधे आपके खाते में आ सके।

– ई-वेरिफिकेशन न भूलें: ITR फाइल करने के 30 दिनों के भीतर ई-वेरिफिकेशन करना अनिवार्य है।

सलाह: यदि पोर्टल पर अत्यधिक लोड के कारण तकनीकी समस्या आए, तो स्क्रीनशॉट लेकर रखें और थोड़ा रुककर पुनः प्रयास करें। 31 जुलाई की मध्यरात्रि से पहले अपनी प्रक्रिया पूरी कर लें। 


आयकर रिटर्न (ITR) भरते समय सही फॉर्म चुनना सबसे महत्वपूर्ण चरण है। गलत फॉर्म चुनने पर इनकम टैक्स डिपार्टमेंट आपके रिटर्न को 'Defective Return' (धारा  139(9)) करार दे सकता है। 

व्यक्तिगत करदाताओं (Individuals) के लिए ITR-1 (Sahaj) और ITR-2 सबसे आम फॉर्म हैं। 

ITR-1 (Sahaj) और ITR-2 में मुख्य अंतर 

विषय ITR-1 (Sahaj) ITR-2

पात्रता (Eligibility) केवल भारत के निवासी (Resident Individuals) निवासी (Resident), अनिवासी (NRI) और HUF

कुल आय सीमा ₹50 लाख तक ₹50 लाख से अधिक (कोई सीमा नहीं)

मकान संपत्ति (House Property) केवल 1 मकान संपत्ति से आय 1 से अधिक मकान संपत्तियों से आय

कैपिटल गेन्स (शेयर, MF, प्रॉपर्टी) केवल Section 112A के तहत ₹1.25 लाख तक LTCG सभी प्रकार के Capital Gains (STCG/LTCG,  प्रॉपर्टी, सोना आदि)

विदेशी संपत्ति / आय (Foreign Assets) अनुमति नहीं है विदेश में संपत्ति, शेयर (RSUs/ESOPs) या आय होने पर अनिवार्य

कृषि आय (Agricultural Income) ₹5,000 तक ₹5,000 से अधिक होने पर

डायरेक्टर / अनलिस्टेड शेयर कंपनी में डायरेक्टर या अनलिस्टेड शेयरधारक फाइल नहीं कर सकते कंपनी के डायरेक्टर या अनलिस्टेड शेयरधारक फाइल कर सकते हैं

आपके लिए कौन सा फॉर्म सही है?

1. आपको ITR-1 (Sahaj) चुनना चाहिए यदि:
 

• आपकी कुल वार्षिक आय ₹50 लाख तक है। 

• आपकी आय का मुख्य स्रोत वेतन (Salary), पेंशन (Pension) या ब्याज/डिविडेंड (Other Sources) है। 

• आपके पास केवल 1 मकान संपत्ति (Single House Property) है। 

• आपकी कृषि आय (Agricultural Income) ₹5,000 या उससे कम है। 

• आपने शेयर या म्यूचुअल फंड बेचे हैं, लेकिन आपका कुल लॉन्ग-टर्म कैपिटल गेन (Section 112A u/s) ₹1.25 लाख के अंदर है और कोई अन्य कैपिटल गेन  या लॉस नहीं है। 

2. आपको ITR-2 चुनना चाहिए यदि: 

• आपकी कुल वार्षिक आय ₹50 लाख से अधिक है। 

• आपने शेयर, म्यूचुअल फंड, जमीन, मकान या सोना बेचा है और आपको Short-Term Capital Gain (STCG) या अधिक LTCG हुआ है। 

• आपके पास 2 या उससे अधिक मकान हैं जिनसे किराया या आय आती है। 

• आपकी विदेशी आय है या विदेश में कोई बैंक खाता/कंपनी शेयर (जैसे MNCs से मिले US Stocks/ESOPs) हैं। 

• आपकी कृषि आय ₹5,000 से अधिक है। 

• आप किसी कंपनी में डायरेक्टर (Director) हैं या आपके पास अनलिस्टेड कंपनियों के शेयर हैं। 

• आपका आवासीय दर्जा NRI (Non-Resident Indian) या RNOR है। 

ध्यान दें: बिजनेस या प्रोफेशन से आय (जैसे फ्रीलांसिंग, कंसल्टेंसी, ट्रेडिंग या बिज़नेस प्रॉफिट) कमाने वाले व्यक्ति ITR-1 या ITR-2 का उपयोग नहीं कर सकते। उनके लिए ITR-3  या ITR-4 लागू होता है। 


आयकर पोर्टल (Income Tax Portal) से AIS (Annual Information Statement) डाउनलोड करना और उसका Form 16 से मिलान  (Reconciliation) करना आयकर रिटर्न (ITR) फाइल करने का सबसे महत्वपूर्ण चरण है। इससे आपके ITR में किसी प्रकार के मिसमैच की संभावना खत्म हो जाती है।
 

1. AIS कैसे डाउनलोड करें? (Step-by-Step Guide) 
 

1.इ-फाइलिंग पोर्टल पर लॉगिन करें:

आयकर विभाग की आधिकारिक वेबसाइट incometax.gov.in पर जाएं। अपने PAN (यूजर ID) और पासवर्ड से लॉगिन करें।

2.Services मेनू में जाएं:

लॉगिन के बाद मुख्य मेनू बार पर Services टैब पर क्लिक करें और ड्रॉपडाउन से Annual Information Statement (AIS) चुनें।

3.AIS पोर्टल पर रिडायरेक्ट हों:

स्क्रीन पर एक पॉप-अप मैसेज आएगा, वहां Proceed पर क्लिक करें। यह आपको एक नए Compliance Portal पर ले जाएगा।

4.असेसमेंट ईयर और फाइल फॉर्मेट चुनें:

Compliance Portal पर AIS टैब पर क्लिक करें। ऊपर से सही असेसमेंट ईयर (जैसे AY 2026-27) चुनें।

5.PDF या Excel में डाउनलोड करें:PDF खोलने के लिए पासवर्ड डालें.

आप पूरे विवरण को PDF या JSON/Excel फॉर्मेट में डाउनलोड करने के लिए Download बटन पर क्लिक करें।
 

PDF खोलने का पासवर्ड Format: 

AIS की PDF फाइल पासवर्ड प्रोटेक्टेड होती है। इसका पासवर्ड आपका PAN (स्मॉल लेटर्स में) + आपकी जन्मतिथि (DDMMYYYY) होता है। 

उदाहरण: यदि आपका PAN ABCDE1234F और DOB 15/08/1990 है, तो पासवर्ड होगा: abcde1234f15081990।

2. Form 16 और AIS का मिलान (Reconciliation) कैसे करें? 

Form 16 आपके एम्प्लॉयर (कंपनी) द्वारा दी गई सैलरी और काटे गए TDS का प्रमाण है, जबकि AIS में आपकी सैलरी के अलावा बैंक ब्याज, डिविडेंड, शेयर ट्रेडिंग आदि की भी  जानकारी होती है। 

दोनों का मिलान करते समय निम्नलिखित बिंदुओं को क्रमानुसार जांचें:

1. ग्रॉस सैलरी (Gross Salary) का मिलान 

• Form 16 (Part B): अपनी कुल ग्रॉस सैलरी और एम्प्लॉयर द्वारा काटे गए कुल TDS की जांच करें। 

• AIS (Part B – TDS/TCS section): सैलरी कोड (192) के सामने दिख रही रकम और काटे गए TDS का मिलान Form 16 के Part A से  करें। 

• ध्यान दें: यदि आपने साल के दौरान नौकरी बदली है, तो दोनों एम्प्लॉयर्स के Form 16 की कुल रकम का जोड़ AIS की कुल सैलरी से मिलना चाहिए। 

2. TDS और Form 26AS से क्रॉस-चेक 

• Form 16 में दर्ज कुल TDS कटौती, AIS के TDS/TCS टैब और आपके Form 26AS में दिख रहे टैक्स क्रेडिट से पूरी तरह मैच होनी चाहिए। 

3. अन्य आय (Other Income) की पहचान 

AIS में सैलरी के अलावा कई ऐसी आय दर्ज होती हैं जो Form 16 में नहीं होतीं: 

• बैंक ब्याज (Savings/FD Interest): पासबुक और बैंक से मिले इंटरेस्ट सर्टिफिकेट से इसका मिलान करें। 

• डिविडेंड (Dividend Income): शेयर या म्यूचुअल फंड से मिले डिविडेंड को क्रॉस-चेक करें। 

• कैपिटल गेन्स (Shares/MF Sale): शेयर या प्रॉपर्टी बिक्री से हुई कमाई AIS के SFT Information में दिखती है।
 

यदि AIS में गलत जानकारी या अंतर दिखाई दे तो क्या करें? 
 

अगर AIS में कोई ऐसी इनकम दर्ज दिख रही है जो आपकी नहीं है या कोई आंकड़ा दो बार (Duplicate) दर्ज हो गया है, तो आप पोर्टल पर Feedback दे सकते हैं: 

1. AIS Portal पर उस गलत एंट्री/लाइन आइटम पर क्लिक करें। 

2. Optional / Feedback बटन चुनें।

3. उपयुक्त विकल्प चुनें (जैसे: Information is not correct, Income is not taxable, या Information relates to  other PAN/Year)।

4. इसे सबमिट कर दें। सबमिट करने के बाद आपकी TIS (Taxpayer Information Summary) अपने आप अपडेट हो जाएगी।

LIC’s Micro Bachat Plan: ₹1000 महीने वाली एलआईसी पॉलिसी, रिटर्न भी धांसू

LIC’s Micro Bachat Plan: एलआईसी के कुछ प्लान ऐसे हैं, जिनमें इंश्योरेंस कवरेज के साथ-साथ रिटर्न भी बेहतर मिलता है। इसमें से एक माइक्रो बचत प्लान है। इसमें सालाना करीब ₹12 हजार में यानी हर महीने महज ₹1000 के प्रीमियम में ही 15 साल तक का इंश्योरेंस कवरेज हासिल किया जा सकता है। इसमें पॉलिसीहोल्डर्स को शर्तों के हिसाब से लॉयल्टी एडीशंस मिलता है और मौजूदा लॉयल्टी एडीशंस के हिसाब से करीब 6% तक का रिटर्न बन सकता है। हालांकि इस प्लान की कुछ सीमाएं भी हैं जैसे कि इसमें अधिकतम ₹2 लाख तक की ही पॉलिसी खरीदी जा सकती है। इस

LIC’s Micro Bachat Plan: खास बातें

एलआईसी का माइक्रो बचत प्लान एक नॉन-लिंक्ड, पार्टिसिपेटिंग, इंडिविजुअल लाइफ, माइक्रो-इंश्योरेंस, सेविंग्स प्लान है।

इसमें 18-55 वर्ष की उम्र में ₹1-₹2 लाख तक की पॉलिसी ली जा सकती है।

प्रीमियम भरने के लिए 10 से लेकर 15 वर्षों तक का पीरियड चुना जा सकता है और प्रीमियम पेमेंट टर्म (PPT) खत्म होने के बाद मेच्योरिटी पर पैसा मिलेगा।

मेच्योरिटी पर कितना पैसा मिलेगा, यह निर्भर करता है कि पॉलिसी कितने साल के लिए ली है क्योंकि जितने समय के लिए पॉलिसी लेंगे, उतने समय तक का लॉयल्टी एडीशन (LA) मिलेगा। लॉयल्टी एडीशन 5 साल के बाद ही जुड़ने शुरू होते हैं यानी कि इससे पहले सरेंडर करने पर लॉयल्टी एडीशन नहीं मिलेगा।

अब डेथ बेनेफिट की बात करें तो पॉलिसीहोल्डर्स की मौत के मामले में अगर पॉलिसी के पहले पांच साल में मृत्यु हुई है तो नॉमिनी को सम एश्योर्ड के बराबर पैसा मिलेगा और 5 साल के बाद मौत होने पर सम एश्योर्ड के साथ लॉयल्टी एडीशन जोड़कर मिलेगा। सम एश्योर्ड का मतलब बेसिक सम एश्योर्ड या सालाना प्रीमियम के सात गुने में जो अधिक हो, वह है।

इसमें किए गए निवेश पर ओल्ड टैक्स रिजीम में सेक्शन 80सी के तहत टैक्स डिडक्शन मिलता है तो मेच्योरिटी का पैसा सेक्शन 10(10डी) के तहत टैक्स-फ्री है।

इसमें ADDB (एक्सीडेंटल डेट एंड डिजेबिलिटी बेनेफिट), AB, AB (दो गुना), AB (3 गुना) जैसे राइडर्स उपलब्ध हैं।

उदाहरण से समझें

मान लिया कि 55 साल के किसी शख्स ने इस प्लान के तहत ₹2 लाख की पॉलिसी खरीदी। उनका सालाना प्रीमियम ₹12066, छमाही ₹6096, तिमाही ₹3080 या मासिक ₹1027 बनेगा। 15 साल तक प्रीमियम पेमेंट करने के बाद मौजूदा लॉयल्टी एडीशन के हिसाब से रिटर्न में ₹2.65 लाख मिलेंगे। अभी सम एश्योर्ड के हर ₹1000 पर एलआईसी ₹325 लॉयल्टी एडीशन दे रही है। इसमें सालाना 5.1% का रिटर्न बनता दिख रहा है। ध्यान दें कि इसमें प्रीमियम कैलकुलेशन ADDB राइडर्स को मिलाकर किया गया है।

अब मान लेते हैं कि किसी शख्स ने 18 साल की उम्र में पॉलिसी ली। ADDB राइडर्स के साथ सालाना प्रीमियम ₹10360, छमाही ₹5235, तिमाही ₹2645 या मासिक ₹882 बनेगा। 15 साल तक प्रीमियम पेमेंट करने के बाद मौजूदा लॉयल्टी एडीशन के हिसाब से रिटर्न में ₹2.65 लाख मिलेंगे। इसमें सालाना 6.7% तक ेका रिटर्न बनता दिख रहा है।

LIC का बड़ा दांव! पति-पत्नी के लिए लॉन्च किए दो नए इंश्योरेंस प्लान, एक पॉलिसी में मिलेगा सेविंग और लाइफ कवर

Small Savings Schemes: शेयर मार्केट में उठा-पटक की टेंशन दूर, 8.2% तक का रिटर्न, पोस्ट ऑफिस की ये स्कीम शानदा

डिस्क्लेमर: निवेश या बीमा से जुड़ा कोई भी फैसला लेने से पहले अपने सलाहकार से जरूर संपर्क करें। मनीकंट्रोल की तरफ से किसी को भी पैसा लगाने की यहां कभी भी सलाह नहीं दी जाती है।

Small Savings Schemes: शेयर मार्केट में उठा-पटक की टेंशन दूर, 8.2% तक का रिटर्न, पोस्ट ऑफिस की ये स्कीम शानदार

Small Savings Schemes: पिछले कुछ महीनों से स्टॉक मार्केट में काफी उठा-पटक दिख रही है। इससे शॉर्ट टर्म में रिटर्न को लेकर निवेशक परेशान हो गए हैं। हालांकि अधिकतक एक्सपर्ट्स लंबे समय में अच्छा पैसा बनाने के लिए इक्विटी में पैसा लगाने की सलाह देते हैं लेकिन जो निवेशक मार्केट की घबराहट से दूर बिना टेंशन अच्छा पैसा बनाना चाहते हैं, उनके लिए भी मार्केट में विकल्प उपलब्ध हैं। ऐसे निवेशकों के लिए सरकार के सपोर्ट वाली छोटी बचत योजनाएं पोर्टफोलियो का अच्छा हिस्सा बन सकती हैं। इनमें सालाना 8.2% तक का ब्याज मिल रहा है, जिससे मार्केट की उठा-पटक से दूर निवेशकों का क्रेज इन्हें लेकर बढ़ रहा है।

Public Provident Fund (PPF)

लंबे समय से पीपीएफ सैलरीड एंप्लॉयीज और अपना खुद का बिजनेस करने वालों के लिए सबसे पसंदीदा निवेश विकल्पों में शुमार है। अभी इस पर सालाना 7.1% की दर से ब्याज मिल रहा है। इसका मेच्योरिटी पीरियड 15 वर्ष है। पुरानी टैक्स व्यवस्था यानी ओल्ड टैक्स रिजीम के तहत इसमें किए गए निवेश पर इनकम टैक्स के सेक्शन 80C के तहत टैक्स डिडक्शन मिलका है। साथ ही अर्जित ब्याज और मेच्योरिटी पर मिलने वाला पैसा भी टैक्स-फ्री होता है।

National Savings Certificate (NSC)

एनएससी एक फिक्स्ड इनकम योजना है, जिसमें अभी सालाना 7.7% की दर से ब्याज मिल रहा है। इसका मेच्योरिटी पीरियड 5 साल है और इसमें निवेश पर सेक्शन 80सी के तहत टैक्स बेनेफिट्स भी मिलता है।

Kisan Vikas Patra (KVP)

बाजार की उठा-पटक से दूर किसान विकास पत्र (केवीपी) ऐसे निवेशकों के लिए सुरक्षित है जो बिना किसी टेंशन अपने पैसे को अच्छी रफ्तार से बढ़ता हुआ देखना चाहते हैं। अभी इस पर सालाना 7.5% की दर से ब्याज मिल रहा है और इस रफ्तार से 115 महीने में इसमें रखा पैसा डबल हो जाता है।

Sukanya Samriddhi Yojana (SSY)

लड़कियों के भविष्य को सुरक्षित रखने के उद्देश्य से शुरू की गई सुकन्या समृद्धि योजना में अभी सालाना 8.2% की दर से ब्याज मिल रहा है जोकि स्मॉल सेविंग्स स्कीम्स में सबसे अधिक ब्याज देने वाली योजना में से एक है। 10 साल से कम उम्र की लड़की के अभिभावक यह खाता खोल सकते हैं।

Senior Citizens’ Savings Scheme (SCSS)

सीनियर सिटीजंस सेविंग्स स्कीम के तहत अभी सालाना 8.2% की दर से ब्याज मिल रहा है और यह भी अधिक ब्याज देने वाली सरकारी बचत योजनाओं में शुमार है। इसके तहत 60 वर्ष या इससे अधिक उम्र के लोग निवेश कर सकते हैं और ऐसे लोगों के लिए बेहतर है जो नियमित आय चाहते हैं।

Post Office Time Deposits

पोस्ट ऑफिस में बैंकों की तरह एक एफडी है, जिसे सरकार का सपोर्ट मिला हुआ है। इसमें एक साल की जमा पर 6.9%,दो साल की जमा पर 7.0%, तीन साल की जमा पर 7.1% और पांच साल की जमा पर 7.5% की दर से ब्याज मिलेगा। पांच साल की जमा पर सेक्शन 80सी के तहत टैक्स बेनेफिट्स भी मिलेगा।

छोटी बचत योजनाओं पर ब्याज दरें

सरकार हर तिमाही स्मॉल सेविंग्स स्कीम्स यानी छोटी बचत योजनाओं पर ब्याज दरें तय करती हैं और सितंबर तिमाही के लिए ब्याज दरों में कोई बदलाव नहीं किया गया है। यहां पोस्ट ऑफिस से जुड़ी स्कीम्स के लिए ब्याज दर की डिटेल्स दी जा रही है-

स्मॉल सेविंग्स स्कीमब्याज दर
सुकन्या समृद्धि योजना (SSY)8.2%
सीनियर सिटीजंस सेविंग्स स्कीम (SCSS)8.2%
नेशनल सेविंग्स सर्टिफिकेट (NSC)7.7%
किसान विकास पत्र (KVP)7.5%
5 वर्षीय पोस्ट ऑफिस टाइम डिपॉजिट7.5%
पोस्टऑफिस मंथली इनकम स्कीम (POMIS)7.4%
पब्लिक प्रोविडेंट फंड (PPF)7.1%
3 साल का पोस्ट ऑफिस  टाइम डिपॉजिट7.1%
2 साल का पोस्ट ऑफिस डाकघर टाइम डिपॉजिट7.0%
1 साल का पोस्ट ऑफिस  टाइम डिपॉजिट6.9%
पोस्ट ऑफिस आरडी (RD)6.7%
पोस्ट ऑफिस सेविंग्स स्कीम4.0%

SIP Calculator: म्यूचुअल फंड में ₹999 की छोटी SIP से तैयार होगा लाखों का फंड

डिस्क्लेमर: निवेश से जुड़ा कोई भी फैसला लेने से पहले अपने निवेश सलाहकार से जरूर संपर्क करें। मनीकंट्रोल की तरफ से किसी को भी पैसा लगाने की यहां कभी भी सलाह नहीं दी जाती है।