PNB Bank Share Price: पीएसयू बैंक पंजाब नेशनल बैंक (PNB) के शेयर आज 8% उछलकर 7 महीने के उच्चतम स्तर पर पहुंच गए। स्टॉक में यह तेजी कंपनी के तिमाही नतीजों के ऐलान के बाद आई। हालांकि स्टॉक में अच्छी तेजी देखी जा रही है, लेकिन ग्लोबल इन्वेस्टमेंट बैंकिंग फर्मों CLSA और Citi की इस पर अलग-अलग राय है। CLSA इसे लेकर बुलिश है, जबकि Citi ने इस स्टॉक पर Sell की रेटिंग दी है।
कैसे रहे तिमाही नतीजे
PNB ने सितंबर 2024 को समाप्त तिमाही के लिए अपने नेट प्रॉफिट में 145% की बढ़ोतरी की जानकारी दी। सितंबर 2023 की तिमाही में 1756 करोड़ रुपये के मुकाबले, Q2 में नेट प्रॉफिट बढ़कर 4303.5 करोड़ रुपये हो गया। Q2 में ग्रॉस NPA, जून 2024 की तिमाही के 4.98% से घटकर 4.48% रह गए। नेट NPA भी जून 2024 की तिमाही के 0.60% से घटकर 0.46% पर आ गए।
जुलाई-सितंबर तिमाही के दौरान बैंक की नेट इंटरेस्ट इनकम (NII) 5.99% बढ़कर 10,517 करोड़ रुपये हो गई, जबकि पिछले साल की इसी तिमाही में यह 9923 करोड़ रुपये थी। प्रॉफिटेबिलिटी (मुनाफे) का एक अहम पैमाना, नेट इंटरेस्ट मार्जिन (NIM) पिछली तिमाही में 2.92% रहा।
स्टॉक पर क्या है ब्रोकरेज की राय
CLSA
CLSA ने PNB को “आउटपरफॉर्म” रेटिंग दी है और इसका टारगेट प्राइस ₹140 प्रति शेयर तय किया है। यह पिछले क्लोजिंग प्राइस से 20.4% की बढ़त की संभावना दिखाता है। फर्म के अनुसार, बैंक का दूसरी तिमाही का टैक्स के बाद मुनाफा (PAT) अनुमानों से 20% अधिक रहा। इसकी मुख्य वजह नेट इंटरेस्ट इनकम (NII) का बेहतर प्रदर्शन और कुछ विशेष रिकवरी रही, हालांकि अन्य आय (other income) में कमी ने इस बढ़त को कुछ हद तक कम कर दिया।
CLSA ने बताया कि बैंक की लोन ग्रोथ पिछले साल के मुकाबले बढ़कर 16% हो गई है, जबकि कुछ तिमाहियों पहले यह दहाई के निचले स्तर (low double-digits) पर थी। वहीं, डिपॉजिट ग्रोथ पिछले साल के मुकाबले 10% पर स्थिर बनी हुई है।
पंजाब नेशनल बैंक के नेट इंटरेस्ट मार्जिन (NIM) में 8 बेसिस पॉइंट्स का सुधार हुआ है, जो मुख्य रूप से लोन यील्ड (loan yields) और डिपॉजिट कॉस्ट (deposit cost) में बदलाव के कारण हुआ है।
बैंक प्रबंधन ने संकेत दिया है कि NIM में आगे और सुधार हो सकता है। CLSA के अनुसार, बैंक की एसेट क्वालिटी स्थिर रही है और ग्रॉस स्लिपेज रेशियो 0.8% है।
Citi
Citi ने पंजाब नेशनल बैंक के शेयरों पर “Sell” की सलाह दी है। Citi का कहना है कि FCNR इनफ्लो के जरिए होलसेल डिपॉजिट कम होने से डिपॉजिट पर कैश 5 बेसिस पॉइंट्स घट गया। वहीं, रिटेल IBPC और कम रिटर्न देने वाले कॉर्पोरेट एक्सपोजर को कम करने से यील्ड (yields) में 8 बेसिस पॉइंट्स का इजाफा हुआ। सिटी (Citi) के अनुसार, स्टैंडर्ड एसेट प्रोविज़निंग से मिली राशि ने नॉन-परफॉर्मिंग एसेट्स (NPA) और फ्लोटिंग प्रोविज़न बफ़र्स की भरपाई कर दी, जिससे बैंक की क्रेडिट कॉस्ट लगभग शून्य हो गई।
PNB का ‘रिटर्न ऑन एसेट्स’ 1% से ऊपर स्थिर रहा। बैंक के ग्लोबल एडवांसेज (कर्ज) में पिछले साल के मुकाबले 14.7% और पिछली तिमाही के मुकाबले 5.3% की बढ़ोतरी हुई। यह FY27 के लिए तय 12% – 13% के लक्ष्य से भी अधिक है। इसमें FCNR-फंडेड ओवरसीज एक्सपोजर का भी योगदान रहा, जो बैंक की कुल बुक का 1.5% है।
पंजाब नेशनल बैंक (PNB) के शेयर पर नजर रखने वाले 23 एनालिस्ट्स में से 14 ने इसे buy , 3 ने hold करने और 6 ने sell की रेटिंग दी है।
(डिस्क्लेमर: मनीकंट्रोल.कॉम पर दिए गए विचार एक्सपर्ट के अपने निजी विचार होते हैं। वेबसाइट या मैनेजमेंट इसके लिए उत्तरदाई नहीं है। यूजर्स को मनी कंट्रोल की सलाह है कि कोई भी निवेश निर्णय लेने से पहले सार्टिफाइड एक्सपर्ट की सलाह लें।
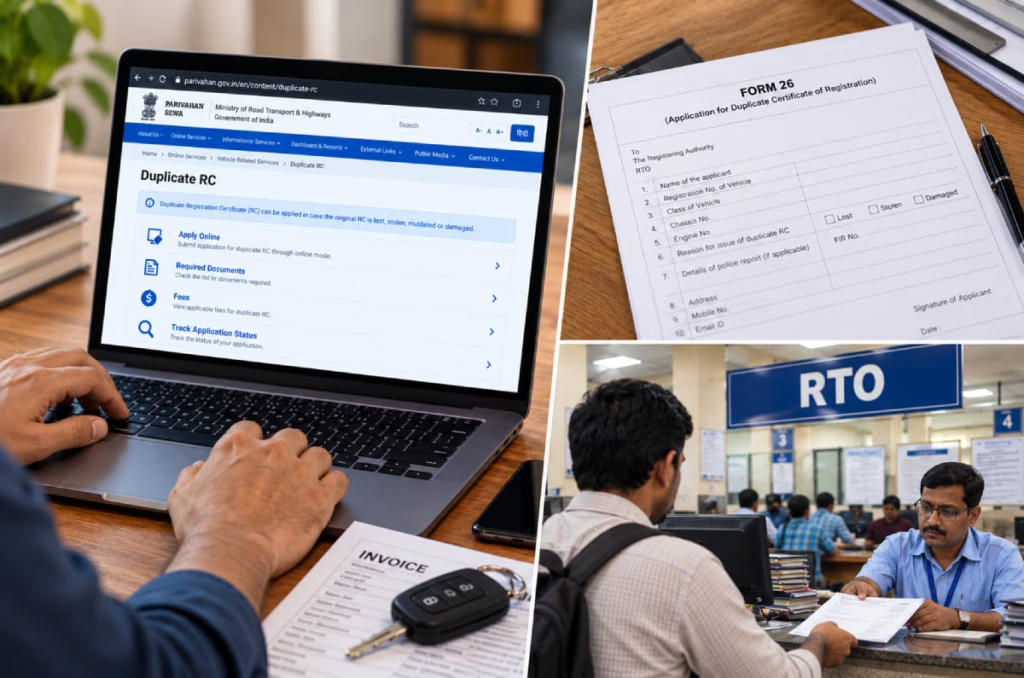
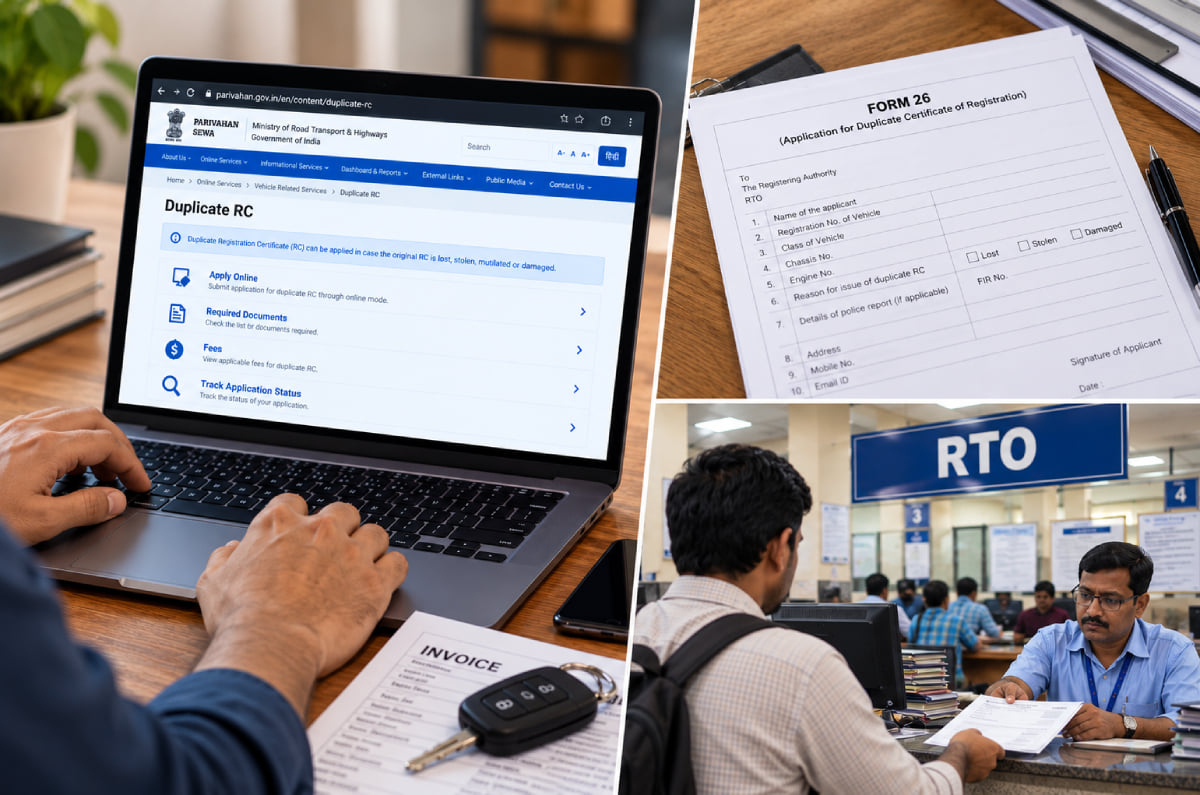
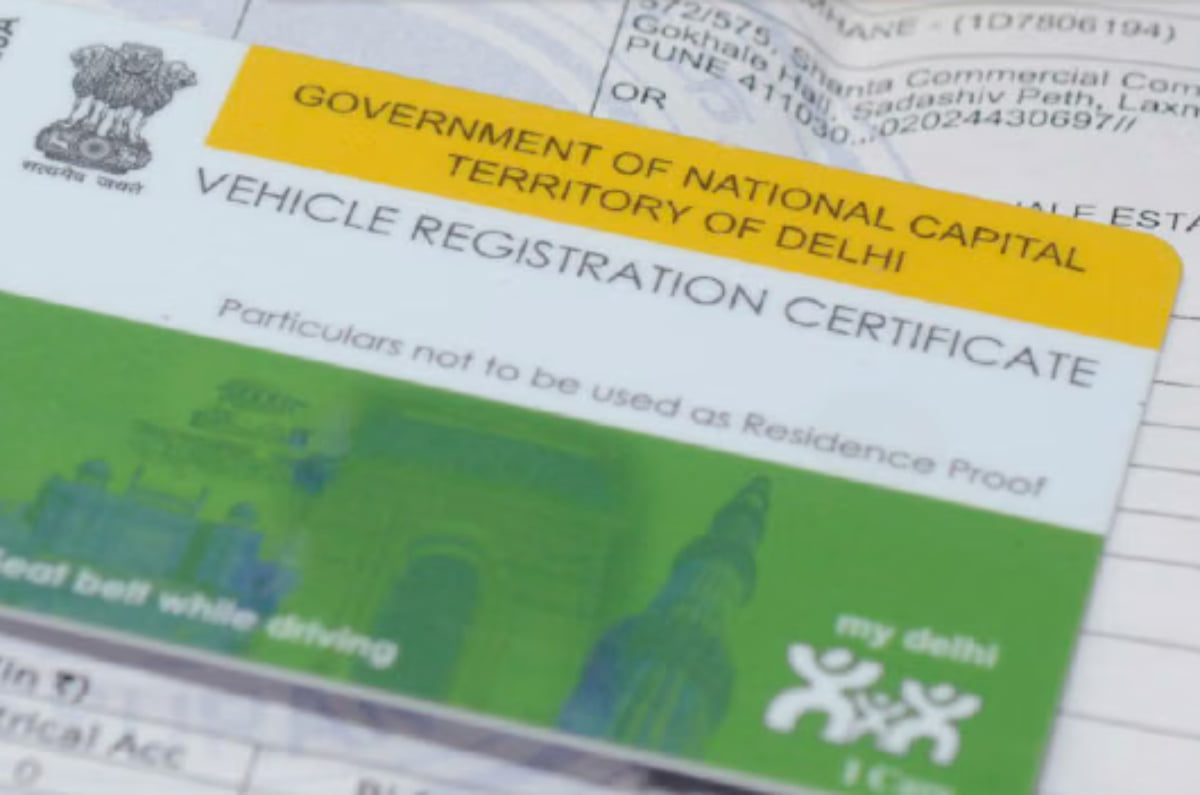
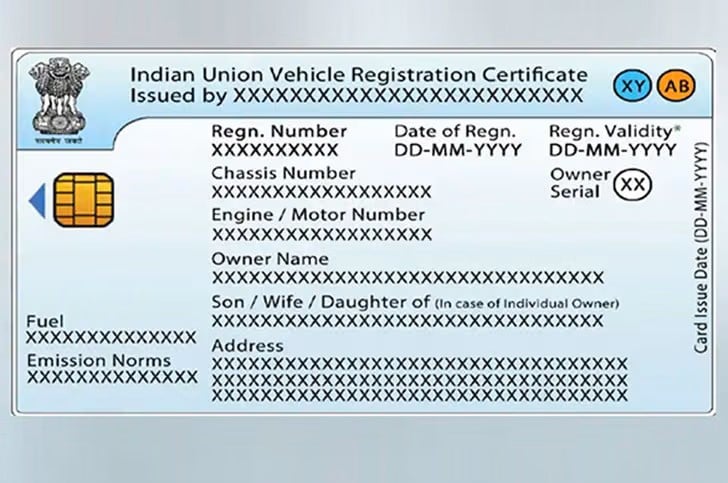
A vehicle’s Registration Certificate (RC) is an official document that records its registration with the Regional Transport Office (RTO). If the original RC is lost, stolen or damaged, owners can apply for a duplicate instead of registering the vehicle again.
The application can be started online through the government’s Parivahan Sewa portal. Depending on the state and RTO, applicants may also need to submit physical documents or visit the RTO for verification. Here’s how to apply for a duplicate RC and what to keep ready.
When do you need a duplicate RC?
You can apply for a duplicate RC if the original certificate has been lost, stolen or damaged to the point that its details are no longer legible. The duplicate replaces the existing certificate; it does not change the vehicle’s registration number.
If the original is damaged, keep it ready to surrender if the RTO requires it. If it is lost or stolen, report the incident to the police and retain the relevant report for the application.
A duplicate RC is different from an RC renewal, which is required when the registration expires.
What documents are required for a duplicate RC?
The main application form is Form 26, which is used to request a duplicate Registration Certificate. Depending on the circumstances and the requirements of the relevant RTO, applicants may need the following documents:
Form 26: The application for a duplicate RC.
Police report or FIR: For a lost or stolen RC, as applicable.
Valid motor insurance: Proof of current vehicle insurance.
Valid PUC certificate: The vehicle’s Pollution Under Control certificate.
Identity and address proof: Such as an Aadhaar card, PAN card or another accepted document.
Affidavit or declaration: If required by the registering authority.
Chassis number imprint: A pencil impression may be required.
Financier’s NOC: If the vehicle is under an active loan or has a hypothecation entry on its RC.
Disclamer: Requirements can vary by state, RTO and vehicle category. Check the applicable document list before submitting the application.
How to apply for a duplicate RC online
Owners can start the application through the Parivahan Sewa portal. The steps may differ slightly depending on the state and the services available for the vehicle.
Step 1: Visit the Parivahan Sewa portal
Go to parivahan.gov.in and open the vehicle-related services section. Select the state in which the vehicle is registered.
Step 2: Enter the vehicle details
Open the relevant vehicle services page and enter the vehicle’s registration number. The portal may ask for the last five digits of the chassis number and OTP verification.
Step 3: Select the duplicate RC service
Choose ‘Duplicate RC’ or the corresponding duplicate Registration Certificate service from the available options.
Step 4: Fill in the application
Enter the requested details and check that the vehicle and owner information is correct. Provide the reason for requesting a duplicate, where prompted.
Step 5: Submit the documents
Upload the required documents if the portal provides that option. Keep the police report or FIR ready for a lost or stolen RC, along with the insurance and PUC certificates and any other documents requested by the RTO.
Step 6: Pay the applicable fee
Review the fee displayed on the portal and complete the payment. Save the receipt and application number for future reference.
Step 7: Complete verification, if required
Depending on the state’s process, the RTO may require physical document submission or an appointment for verification. Follow the instructions shown after submitting the application.
Step 8: Track the application
Use the application number or the relevant status service on Parivahan to check the progress of the request. Once approved, the duplicate RC is processed according to the applicable procedure.
Can you apply for a duplicate RC offline?
Yes. You can apply for a duplicate RC through the RTO where the vehicle is registered. Submit Form 26 along with the required documents, pay the applicable fee and retain the acknowledgement receipt. The RTO may ask for additional documents or verification, depending on the vehicle and the reason for the application.
How much does a duplicate RC cost?
The fee depends on the vehicle category and the applicable charges. Additional amounts may apply for smart card issuance and other services.
The Parivahan portal displays the payable amount during the application process. Check the amount shown for your vehicle and confirm any additional charges with the relevant RTO before making the payment.
How long does it take to get a duplicate RC?
The processing time depends on the RTO, document verification and whether a physical visit is required. Applicants can track the request online using the application number and follow up with the registering authority if there is a delay.
Can you drive if your physical RC is lost?
If your physical RC is lost, a virtual RC available through DigiLocker or the mParivahan app is recognised as a valid document under government rules. You should still apply for a duplicate if the original has been lost, stolen or damaged beyond use.
A police report or application acknowledgement alone does not replace the RC.
What happens if you find the original RC after getting a duplicate?
Once a duplicate RC has been issued, the original should no longer be used. If you find it later, surrender it to the registering authority. The duplicate replaces the original certificate, but the vehicle’s registration number remains unchanged.
How to Buy Home: अपना घर खरीदने का सपना हर कोई देखता है। लेकिन महीने की सैलरी ₹30,000 के आसपास हो, तो लगता है कि आज के जमाने में घर खरीदना शायद मुमकिन नहीं है। किराया, राशन, बिजली का बिल और बच्चों की फीस देने के बाद बचता ही कितना है? ऐसे में होम लोन की EMI चुकाना बड़ी जिम्मेदारी लगती है।
हालांकि, कम सैलरी में भी घर खरीदा जा सकता है। इसके लिए जरूरी है कि आप अपनी कमाई के हिसाब से घर चुनें। बड़ा लोन लेने के बजाय ऐसी EMI रखें, जिसे हर महीने आसानी से चुका सकें। आइए, उदाहरण से समझते हैं कि ₹30,000 की सैलरी में घर खरीदने का प्लान कैसे बना सकते हैं।
₹30,000 की सैलरी पर कितना होम लोन लें?
BASIC Home Loan के CEO और को-फाउंडर अतुल मोंगा का कहना है कि अगर आप ₹10 लाख का होम लोन लेते हैं, तो ब्याज दर और लोन की अवधि के हिसाब से EMI करीब ₹10,000 हो सकती है। मोंगा के मुताबिक, अगर आपकी सैलरी ₹30,000 है, तो घर खरीदना सिर्फ कमाई पर निर्भर नहीं करता। ये भी जरूरी है कि आप घर खरीदने की कितनी अच्छी तैयारी करते हैं। घर
इसे एक उदाहरण से समझते हैं। मान लीजिए कि आपकी सैलरी ₹30,000 है। इसमें से ₹8,000 घर और किराने, ₹3,000 बिजली और दूसरे बिलों, ₹4,000 आने-जाने और ₹5,000 परिवार के अन्य खर्चों में जाते हैं। इस तरह कुल खर्च ₹20,000 हुआ। अब आपके पास ₹10,000 बचते हैं।
सैलरी के हिसाब से खर्च का पूरा हिसाब समझें
महीने का हिसाब
रकम
कुल सैलरी
₹30,000
राशन और घर का खर्च
₹8,000
बिजली, मोबाइल और दूसरे बिल
₹3,000
आने-जाने का खर्च
₹4,000
परिवार के दूसरे खर्च
₹5,000
कुल खर्च
₹20,000
खर्च के बाद बची रकम
₹10,000
ये सिर्फ उदाहरण है। आप अपने परिवार के खर्च के हिसाब से इसमें बदलाव कर सकते हैं। जैसे कि कुछ पैसे बचाकर इमरजेंसी के लिए रख सकते हैं।
डाउन पेमेंट के लिए पैसे कैसे जुटाएं?
बैंक आमतौर पर घर की पूरी कीमत का लोन नहीं देते। घर खरीदते समय आपको भी कुछ पैसा लगाना पड़ता है। इसी को डाउन पेमेंट कहते हैं। इसके अलावा रजिस्ट्री और स्टांप ड्यूटी जैसे खर्च भी हो सकते हैं।
मान लीजिए, आपको ₹15 लाख का घर पसंद आया। बैंक ₹12 लाख का लोन देने को तैयार है। ऐसे में बाकी ₹3 लाख आपको अपनी तरफ से लगाने होंगे। रजिस्ट्री और दूसरे खर्चों के लिए अलग से पैसा भी चाहिए हो सकता है।
इसलिए घर खरीदने से पहले बचत शुरू करें। हर महीने ₹5,000 बचाने पर एक साल में ₹60,000 जमा होंगे। इसी तरह, तीन साल में ब्याज को छोड़कर ₹1.80 लाख जमा हो सकते हैं। अगर परिवार से आर्थिक मदद मिले या बोनस की रकम बचा सकें, तो डाउन पेमेंट का लक्ष्य जल्दी पूरा हो सकता है।
होम लोन लेने से पहले इन बातों का रखें ध्यान
अतुल मोंगा के मुताबिक, होम लोन लेने से पहले सबसे पहले अलग-अलग बैंकों की ब्याज दरें और प्रोसेसिंग फीस देखें। सिर्फ कम ब्याज दर देखकर लोन लेने से बचना चाहिए। लोन की अवधि और दूसरी शर्तें भी समझना जरूरी है।
कमाई और बैंकिंग रिकॉर्ड व्यवस्थित रखने से आवेदन की प्रक्रिया आसान हो सकती है। अगर भविष्य में आपकी कमाई बढ़ती है और आपके पास अतिरिक्त पैसा आता है, तो लोन की कुछ रकम पहले चुकाने पर भी विचार कर सकते हैं। इसे पार्ट-प्रीपेमेंट कहते हैं। इससे बकाया लोन और कुल ब्याज घट सकता है।
मोंगा का कहना है कि आखिरकार मकसद सिर्फ होम लोन लेना नहीं होना चाहिए। जरूरी यह है कि लोन की रकम इतनी हो, जिसकी EMI परिवार लंबे समय तक आसानी से चुका सके। इसके लिए परिवार के दूसरे जरूरी खर्चों और भविष्य के वित्तीय लक्ष्यों से समझौता नहीं करना पड़े।
Disclaimer: यहां दी गई जानकारी सिर्फ सामान्य जागरूकता के लिए है। किसी भी निवेश, लोन, टैक्स, बीमा या दूसरे वित्तीय फैसले लेने से पहले संबंधित एक्सपर्ट्स से सलाह जरूर लें। मनीकंट्रोल किसी भी फाइनेंशियल प्रोडक्ट या सर्विस की सिफारिश नहीं करता।
As part of its festive offers, Classic Legends has announced flexible financing options for its motorcycles. These offers are aimed at making its Jawa, Yezdi and BSA motorcycles more accessible to buyers.
Up to 100 percent funding with zero downpayment plans
Interest rates starting at 5.99 percent with loan tenures up to 72 months
Buy now, pay later and no-hypothecation schemes also available
Jawa Yezdi Motorcycles festive financing offer details
The company has not specified model-wise financing benefits in the announcement
The financing schemes include up to 100 percent funding, zero down payment, interest rates starting at 5.99 percent and repayment tenures of up to 72 months, subject to eligibility, terms and conditions. Eligible customers can choose Buy Now Pay Later (BNPL) schemes, while select financing options offer no-hypothecation benefits. The brand has also introduced specially designed ownership programmes for Mahindra Group employees as well.
These offers cover motorcycles under the Jawa, Yezdi and BSA brands, which are part of the Classic Legends portfolio, though it has not specified model-wise financing benefits in the announcement. The company said the financing options are intended to benefit buyers with different financial requirements and ownership preferences. Customers will need to check the applicable terms, eligibility criteria and availability of offers with authorised dealerships.
Currently Classic Legends offers a wide range of motorcycles under the Jawa, Yezdi, and BSA brand umbrellas. The Jawa lineup comprises models ranging from the All Star 42 OG (Rs 1.87 lakh to Rs 1.90 lakh) to the Jawa 350 (Rs 2.11 lakh to Rs 2.22 lakh). The Yezdi range starts with the base Roadster at Rs 2 lakh and goes up to the tubeless-wheel-equipped Adventure at Rs 2.33 lakh. Rounding out the portfolio are BSA’s 650cc offerings, the Scrambler (Rs 3.25 lakh to Rs 3.41 lakh) and the flagship Gold Star 650 (Rs 3.42 lakh to Rs 3.65 lakh).
Car vs Investment: कार खरीदना कई लोगों का सपना होता है। लेकिन इस फैसले का असर आपकी जेब पर भी पड़ता है। कार खरीदने के बाद उसकी कीमत घटती है। साथ ही पेट्रोल, इंश्योरेंस और मेंटेनेंस पर भी पैसा खर्च होता है। दूसरी तरफ, यही ₹10 लाख निवेश कर दिए जाएं तो 5 साल में अच्छी रकम बन सकती है। ऐसे में सवाल है कि कार खरीदना बेहतर है या पैसे को बढ़ने का मौका देना?
₹10 लाख निवेश करने पर कितना पैसा बनेगा?
मान लीजिए आपके पास ₹10 लाख हैं। आप इस रकम को 5 साल के लिए निवेश करते हैं। अब रिटर्न के अलग-अलग अनुमान से समझते हैं कि आपकी रकम कितनी हो सकती है।
अगर सालाना 8% रिटर्न मिलता है, तो 5 साल बाद ₹10 लाख बढ़कर करीब ₹14.69 लाख हो जाएंगे। इस तरह आपको लगभग ₹4.69 लाख का फायदा होगा।
वहीं, 10% सालाना रिटर्न पर रकम करीब ₹16.11 लाख हो सकती है। यानी ₹6.11 लाख की बढ़त। अगर सालाना रिटर्न 12% रहा, तो 5 साल बाद कुल रकम करीब ₹17.62 लाख हो सकती है। इस स्थिति में मुनाफा लगभग ₹7.62 लाख होगा।
सालाना रिटर्न
शुरुआती निवेश
5 साल बाद कुल रकम
अनुमानित मुनाफा
8%
₹10,00,000
₹14,69,000
₹4,69,000
10%
₹10,00,000
₹16,11,000
₹6,11,000
12%
₹10,00,000
₹17,62,000
₹7,62,000
नोट :यह कैलकुलेशन कंपाउंडिंग के आधार पर है। शेयर बाजार या म्यूचुअल फंड में रिटर्न तय नहीं होता। असल नतीजा निवेश के विकल्प और बाजार के प्रदर्शन पर निर्भर करेगा।
कार खरीदने पर 5 साल में कितना खर्च होगा?
अब कार का हिसाब समझते हैं। मान लीजिए आप ₹10 लाख की कार खरीदते हैं और 5 साल तक उसे चलाते हैं। इस दौरान कार की कीमत घटेगी। इसे डेप्रिसिएशन कहते हैं। इसके अलावा इंश्योरेंस और सर्विस पर भी खर्च होगा।
उदाहरण के लिए, मान लेते हैं कि 5 साल बाद कार की रीसेल वैल्यू ₹5 लाख रह जाती है। यानी उसकी कीमत में ₹5 लाख की कमी आई। इसके अलावा, 5 साल में इंश्योरेंस पर करीब ₹1 लाख और सर्विस व मेंटेनेंस पर ₹75,000 खर्च होते हैं।
₹10 लाख की कार खरीदने पर 5 साल का खर्च
खर्च का हिसाब
अनुमानित रकम
कार की खरीद कीमत
₹10,00,000
5 साल बाद रीसेल वैल्यू
₹5,00,000
कार की कीमत में कमी
₹5,00,000
5 साल का इंश्योरेंस खर्च
₹1,00,000
सर्विस और मेंटेनेंस
₹75,000
5 साल की कुल लागत
₹6,75,000
नोट:ये अनुमानित खर्च और वैल्यू हैं। इसमें पेट्रोल-डीजल, पार्किंग, टोल और लोन का ब्याज शामिल नहीं है।
इस हिसाब से कार रखने की लागत 5 साल में करीब ₹6.75 लाख बैठती है। इसमें पेट्रोल या डीजल, पार्किंग, टोल और लोन का ब्याज शामिल नहीं है। असल खर्च कार के मॉडल और इस्तेमाल के हिसाब से अलग हो सकता है।
दोनों विकल्पों में कितना फर्क पड़ेगा?
अब दोनों की तुलना करते हैं। अगर आप ₹10 लाख निवेश करते हैं और सालाना 10% रिटर्न मिलता है, तो 5 साल बाद रकम करीब ₹16.11 लाख हो सकती है।
दूसरी तरफ, कार खरीदने पर 5 साल बाद उसकी अनुमानित कीमत ₹5 लाख रह जाती है। यानी एक तरफ निवेश की रकम बढ़ रही है, जबकि दूसरी तरफ कार की कीमत घट रही है।
सिर्फ निवेश की रकम और कार की रीसेल वैल्यू देखें, तो दोनों के बीच ₹11.11 लाख का अंतर होगा। कार के इंश्योरेंस और मेंटेनेंस पर खर्च हुए ₹1.75 लाख भी जोड़ दें, तो इस उदाहरण में वित्तीय अंतर करीब ₹12.86 लाख तक पहुंचता है।
लेकिन यह पूरी तरह समान आधार पर की गई तुलना नहीं है। निवेश करने वाले व्यक्ति के पास कार नहीं होगी। उसे आने-जाने के लिए दूसरे साधनों पर खर्च करना पड़ सकता है। वहीं, कार खरीदने वाले को निजी गाड़ी की सुविधा मिलेगी। इसलिए अंतिम फैसला लेते समय इस पहलू को भी देखना जरूरी है।
क्या कार खरीदने के बजाय निवेश करना बेहतर है?
यह आपकी जरूरत पर निर्भर करता है। अगर रोज ऑफिस जाने या परिवार के साथ सफर करने के लिए कार जरूरी है, तो इसे सिर्फ खर्च मानना सही नहीं होगा। कार से समय बचता है और आने-जाने में सुविधा मिलती है।
लेकिन अगर कार खरीदने से आपकी बचत खत्म हो रही है या घर, बच्चों की पढ़ाई और रिटायरमेंट जैसे लक्ष्यों के लिए पैसा कम पड़ सकता है, तो फैसला टालने पर विचार किया जा सकता है। एक विकल्प यह भी है कि आप कम कीमत की कार खरीदें और बाकी रकम निवेश करें। या फिर एकमुश्त 10 लाख आप निवेश कर सकते हैं। और कार लोन ले सकते हैं।
Disclaimer: यहां मुहैया जानकारी सिर्फ सूचना के लिए दी जा रही है। यहां बताना जरूरी है कि मार्केट में निवेश बाजार जोखिमों के अधीन है। निवेशक के तौर पर पैसा लगाने से पहले हमेशा एक्सपर्ट से सलाह लें। मनीकंट्रोल की तरफ से किसी को भी पैसा लगाने की यहां कभी भी सलाह नहीं दी जाती है।
Parag Parikh MF: पराग पारिख फ्लेक्सी कैप फंड ने अपने पास रखी नकदी में बड़ी कटौती की है। एक साल पहले फंड की कैश होल्डिंग करीब 24% थी। अब यह घटकर 9.7% रह गई है। शेयरों की कीमतों में गिरावट के बाद फंड को निवेश के नए मौके दिख रहे हैं। इसलिए उसने बाजार में पैसा लगाना बढ़ा दिया है।
PPFAS Mutual Fund के को-फंड मैनेजर (इक्विटी) और हेड ऑफ रिसर्च रौनक ओंकार ने CNBC-TV18 को एक इंटरव्यू में यह जानकारी दी। उन्होंने कहा कि शेयरों की वैल्यूएशन अब पहले के मुकाबले आकर्षक हो रही है। फंड को कुछ कंपनियों के शेयर कम कीमत पर मिल रहे हैं। इसलिए उसने इन कंपनियों में अच्छी-खासी रकम लगाई है।
ओंकार ने बताया कि फंड ऐसी कंपनियों पर भी नजर रख रहा है, जिनके कारोबार से लगातार कैश आता है। फिलहाल बाजार का ज्यादा ध्यान आर्टिफिशियल इंटेलिजेंस (AI), डेटा सेंटर और सेमीकंडक्टर जैसे क्षेत्रों पर है। इस वजह से कई दूसरी कंपनियों पर निवेशकों का ध्यान कम गया है।
उनके मुताबिक, ऐसी कुछ कंपनियों के शेयर उनकी कमाई और कैश फ्लो के मुकाबले कम वैल्यूएशन पर मिल रहे हैं। इससे मजबूत कारोबार वाली कंपनियों में निवेश का मौका बन रहा है।
DLF में PPFAS क्यों लगा रहा है पैसा?
PPFAS Mutual Fund ने अपने पोर्टफोलियो में रियल एस्टेट कंपनी DLF के शेयर भी शामिल किए हैं। ओंकार ने बताया कि DLF के पास काफी बड़ी जमीन है। कंपनी के पास प्रोजेक्ट पूरे करने की अच्छी क्षमता भी है। इसके अलावा, उसने अपना कर्ज कम किया है। इससे कंपनी की वित्तीय स्थिति मजबूत हुई है।
ओंकार के मुताबिक, अब DLF में निवेश का मौका इस बात में है कि कंपनी अपनी जमीन का इस्तेमाल किस तरह करती है। वह नए प्रोजेक्ट बनाकर कारोबार बढ़ा सकती है। साथ ही, उसके कमर्शियल प्रॉपर्टी से किराये के रूप में लगातार कैश भी आता है।
उन्होंने यह भी कहा कि DLF की बैलेंस शीट पहले से मजबूत है। कर्ज कम होने के कारण कंपनी के पास विस्तार के लिए ज्यादा गुंजाइश है। इससे वह उत्तर भारत के अपने पारंपरिक बाजार से आगे दूसरे क्षेत्रों में भी कारोबार बढ़ा सकती है।
CMS Info Systems पर क्यों है PPFAS की नजर?
PPFAS Mutual Fund ने CMS Info Systems में भी निवेश किया है। इस कंपनी के कारोबार का एक बड़ा हिस्सा कैश से जुड़ा है। ओंकार के मुताबिक, देश की अर्थव्यवस्था में आज भी नकदी का इस्तेमाल हो रहा है। इसलिए बैंकों और दूसरे कैश एक्सेस पॉइंट्स के लिए जरूरी इंफ्रास्ट्रक्चर की जरूरत बनी हुई है।
उन्होंने कहा कि देश में चलन में मौजूद नकदी का स्तर नोटबंदी के समय के मुकाबले ज्यादा है। अर्थव्यवस्था में कई तरह के लेनदेन अब भी कैश से होते हैं। ऐसे में बैंकों और दूसरी जगहों पर नकदी पहुंचाने और उसे संभालने के लिए भरोसेमंद ऑपरेटर जरूरी हैं।
CMS Info Systems इसी तरह के काम से जुड़ी कंपनी है। वह कैश लेनदेन के लिए जरूरी इंफ्रास्ट्रक्चर संभालती है। हालांकि, ओंकार ने यह भी माना कि कंपनी के मुख्य कारोबार में ऑर्गेनिक ग्रोथ बहुत मजबूत नहीं है। इसी वजह से उसके शेयर की वैल्यूएशन भी ज्यादा ऊंची नहीं है।
इसके बावजूद कंपनी का कैश फ्लो मजबूत है। यानी कारोबार से उसके पास लगातार पैसा आता है। कंपनी अपने मौजूदा कारोबार से जुड़े दूसरे क्षेत्रों में भी विस्तार के मौके तलाश रही है।
प्राइवेट बैंकों में 20% निवेश से संतुष्ट है PPFAS
PPFAS Mutual Fund के पोर्टफोलियो का करीब 20% हिस्सा प्राइवेट सेक्टर के बैंकों में लगा है। इसमें HDFC Bank, ICICI Bank, Axis Bank और Kotak Mahindra Bank जैसे शेयर शामिल हैं।
ओंकार ने कहा कि फंड बैंकिंग शेयरों में अपने मौजूदा निवेश से संतुष्ट है। उसे इस सेक्टर में लगातार अपनी हिस्सेदारी बढ़ाने की जरूरत नहीं दिखती। उन्होंने कहा, ‘मुझे नहीं लगता कि इसमें इससे आगे निवेश बढ़ाते रहना सही होगा। आखिर यह बैंकिंग फंड नहीं है। हमने अपने पोर्टफोलियो में बैंकिंग सेक्टर को एक तय हिस्सेदारी दी है।’
ओंकार ने फंड की मौजूदा पसंद के हिसाब से बैंकों की रैंकिंग भी बताई। इसमें HDFC Bank पहले नंबर पर है। इसके बाद ICICI Bank, Axis Bank और Kotak Mahindra Bank का स्थान है।
हालांकि, यह रैंकिंग हमेशा एक जैसी रहेगी, ऐसा नहीं है। ओंकार के मुताबिक, समय के साथ इन बैंकों में निवेश का अनुपात बदल सकता है। यह बाजार की चाल, शेयरों के प्रदर्शन और संबंधित बैंकों के कारोबार की स्थिति पर निर्भर करेगा।
Disclaimer: यहां मुहैया जानकारी सिर्फ सूचना के लिए दी जा रही है। यहां बताना जरूरी है कि मार्केट में निवेश बाजार जोखिमों के अधीन है। निवेशक के तौर पर पैसा लगाने से पहले हमेशा एक्सपर्ट से सलाह लें। मनीकंट्रोल की तरफ से किसी को भी पैसा लगाने की यहां कभी भी सलाह नहीं दी जाती है।
Gold Price Today: सोने और चांदी की कीमतों में सोमवार को गिरावट आई। दिल्ली में सोना 1,400 रुपये सस्ता हो गया। अब 10 ग्राम सोने का भाव 1.53 लाख रुपये रह गया है। अंतरराष्ट्रीय बाजार में कमजोरी और रुपये में मजबूती से सोने की कीमतों पर दबाव पड़ा।
ऑल इंडिया सराफा एसोसिएशन के मुताबिक, 24 कैरेट वाले सोने का भाव शुक्रवार को 1,54,400 रुपये प्रति 10 ग्राम था। सोमवार को यह घटकर 1,53,000 रुपये पर आ गया।
चांदी भी सस्ती हुई। इसकी कीमत 2,000 रुपये गिरकर 2,26,500 रुपये प्रति किलो रह गई। शुक्रवार को यह 2,28,500 रुपये प्रति किलो पर बंद हुई थी।
रुपये की मजबूती से सोने को झटका
HDFC Securities के सीनियर एनालिस्ट सौमिल गांधी ने कहा कि अंतरराष्ट्रीय बाजार से कमजोर संकेत मिले। इसके अलावा, रुपये में मजबूती ने भी सोने और चांदी की कीमतों पर दबाव बढ़ाया।
सोमवार को रुपया डॉलर के मुकाबले 96 पैसे मजबूत होकर 95.75 पर बंद हुआ। छह महीने से ज्यादा समय में रुपये की यह एक दिन की सबसे बड़ी बढ़त थी। इससे पहले भारतीय रिजर्व बैंक (RBI) ने रुपये को संभालने के लिए कई कदम उठाए थे।
गांधी के मुताबिक, घरेलू बाजार में सोने की मांग फिलहाल मिली-जुली है। कीमतें बढ़ने के बाद खरीदारी कमजोर पड़ी है। हालांकि, चीन में छुट्टियों के बाद सोने की मांग बढ़ने की उम्मीद है।
अंतरराष्ट्रीय बाजार में भी गिरा सोना
विदेशी बाजार में भी सोने की कीमत नीचे आई। हाजिर सोना 17.36 डॉलर यानी 0.41% गिरकर 4,176.88 डॉलर प्रति औंस पर आ गया। चांदी भी मामूली गिरावट के साथ 60.66 डॉलर प्रति औंस पर कारोबार कर रही थी।
ब्रोकरेज प्लेटफॉर्म Lemonn के हेड ऑफ रिसर्च गौरव गर्ग ने कहा कि अंतरराष्ट्रीय बाजार में सोना करीब 4,179 डॉलर प्रति औंस पर कारोबार कर रहा था। कच्चे तेल की कीमतों में नरमी के बावजूद अमेरिकी डॉलर इंडेक्स 18 महीने के ऊंचे स्तर के करीब बना हुआ है। इससे सोने की कीमतों में तेजी पर दबाव पड़ रहा है।
उन्होंने बताया कि रूस से ऊर्जा की सप्लाई बढ़ने की उम्मीद से कच्चे तेल की सप्लाई को लेकर चिंता कुछ कम हुई है। हालांकि, पश्चिम एशिया में तनाव और समुद्री रास्तों पर जोखिम के कारण तेल की कीमतों में उतार-चढ़ाव जारी है।
आगे कैसी रहेगी सोने की चाल?
निवेश प्लेटफॉर्म Giottus.com के CEO विक्रम सुब्बुराज के मुताबिक, फिलहाल सोने का आउटलुक चांदी के मुकाबले मजबूत दिख रहा है। वहीं, चांदी की धीमी बढ़त को देखते हुए निवेशकों को सतर्क रहने की जरूरत है।
आने वाले दिनों में बाजार की नजर अमेरिकी डॉलर, बॉन्ड यील्ड और रुपये की चाल पर रहेगी। अमेरिका के महंगाई के आंकड़े भी अहम होंगे। इनसे ब्याज दरों को लेकर संकेत मिल सकते हैं। इसके आधार पर सोने और चांदी की कीमतों में आगे की दिशा तय हो सकती है।
Disclaimer: मनीकंट्रोल.कॉम पर दिए गए सलाह या विचार एक्सपर्ट/ब्रोकरेज फर्म के अपने निजी विचार होते हैं। वेबसाइट या मैनेजमेंट इसके लिए उत्तरदायी नहीं है। यूजर्स को मनीकंट्रोल की सलाह है कि कोई भी निवेश निर्णय लेने से पहले हमेशा सर्टिफाइड एक्सपर्ट की सलाह लें।
Bajaj Finance Home Loan: स्थिर ब्याज दरें त्योहार के मौसम में खरीदारी की योजना बनाना आसान बना सकती हैं, लेकिन फैसला आपकी आर्थिक क्षमता के आधार पर ही होना चाहिए। बुकिंग करने से पहले अपनी ईएमआई, लोन की अवधि और कुल कर्ज लागत की जांच करें।
घर खरीदने का फैसला अक्सर एक योजना के रूप में शुरू होता है और सही समय आने पर यह एक ठोस निर्णय मेंबदल जाता है। कई परिवारों के लिए नवरात्रि ऐसा ही समय होता है, जब त्योहार की खुशी के साथ लंबे समय सेसोची जा रही घर खरीदने की योजना पर आगे बढ़ने का मन बनता है।
वित्तीय स्थिति भी फिलहाल अपेक्षाकृत स्थिर है। भारतीय रिजर्व बैंक (RBI) की मौद्रिक नीति समिति ने अगस्त2026 में रेपो दर 5.25% पर बरकरार रखी, जिससे कर्ज लेने वालों को वित्तीय योजना बनाने के लिए एक स्थिर आधार मिला है। लेकिन शुभ तारीख फैसले का आधार नहीं, सिर्फ उसका एक हिस्सा होनी चाहिए। सबसे महत्वपूर्णयह है कि संपत्ति आपकी बजट सीमा में हो और उसकी मासिक किस्तें चुकाने के बाद आपके पास अन्य जरूरतों केलिए पर्याप्त पैसा बचा रहे।
स्थिर ब्याज दर का माहौल इस फैसले को आसान बना सकता है, क्योंकि इससे मासिक किस्त और कर्ज की लागतका अनुमान लगाना अधिक आसान हो जाता है। घर बुक करने से पहले यह जरूर देखें कि आपको कितना कर्ज लेनाहै, आपकी आर्थिक स्थिति के अनुसार कर्ज की कितनी अवधि सही रहेगी और कुल मिलाकर आप पर कितना वित्तीयबोझ पड़ेगा।
आपके घर की खरीदारी के लिए त्योहारी समय का क्या मतलब है?
नवरात्रि को परंपरागत रूप से बड़ी खरीदारी के लिए शुभ माना जाता है और इसका सांस्कृतिक महत्व भी है। डेवलपरऔर कर्ज देने वाली कंपनियां भी इस दौरान विशेष ऑफर ला सकती हैं। अगर आपको ऐसा कोई ऑफर मिलता है, तो सिर्फ बड़े दावे पर ध्यान देने के बजाय वास्तविक बचत देखें और अंतिम कीमत व शर्तों की तुलना सामान्य कीमतोंसे जरूर करें।
सीधी बात यह है: समय यह तय करने में मदद कर सकता है कि आप खरीदारी कब करें, लेकिन यह तय नहीं कर सकता कि आप इसे खरीदने का खर्च उठा सकते हैं या नहीं।
ब्याज दरें आपकी खरीदारी की क्षमता को कैसे प्रभावित करती हैं?
होम लोन की ब्याज दरेंमासिक किस्त और लोन की पूरी अवधि में चुकाई जाने वाली कुल राशि को प्रभावित करतीहैं। ब्याज दर में मामूली अंतर, जैसे 0.25% कम दर, 20-25 वर्षों में आपकी कुल भुगतान राशि को काफी कम करसकता है।
आपकी खरीदारी के लिए वही ब्याज दर महत्वपूर्ण है, जो आपके लोन पर लागू होती है। बजाज फाइनेंस होम लोनकी ब्याज दरें 7.25%* प्रति वर्ष से शुरू होती हैं, जो आपकी प्रोफाइल और अन्य कारकों पर निर्भर करती हैं।
आपका मासिक बजट कितना खर्च संभाल सकता है?
हर महीने आप जितनी ईएमआई आसानी से चुका सकते हैं, उसके आधार पर आगे की गणना करें। ईएमआई कैलकुलेटर में तीन चीजें डालनी होती हैं: मूलधन, ब्याज दर और लोन की अवधि। इससे आपको मासिक किस्त, लोन की पूरी अवधि में चुकाई जाने वाली कुल राशि और भुगतान की पूरी योजना का अनुमान मिल सकता है।
अपनी अधिकतम पात्रता से शुरुआत करने के बजाय अलग-अलग विकल्पों को आजमाएं। कम राशि को कम अवधिमें लेने की तुलना अधिक राशि को लंबी अवधि में लेने से करें और देखें कि दोनों विकल्प आपके नकदी प्रवाह औरलोन की कुल लागत को कैसे प्रभावित करते हैं।
क्या ईएमआई को प्रबंधीय बनाए रखने के लिए आपको लंबी अवधि चुननी चाहिए?
यह फैसला आपकी मासिक किस्त और लोन की कुल लागत के बीच संतुलन पर निर्भर करता है। कम अवधि कामतलब आम तौर पर ज़्यादा किस्त होता है, लेकिन सालों-साल ब्याज कम देना पड़ता है; वहीं, लंबी अवधि सेमासिक भुगतान कम हो जाता है, लेकिन कुल ब्याज अधिक चुकाना पड़ता है।
सही अवधि आपके नकदी प्रवाह और इस बात पर निर्भर करती है कि आप अतिरिक्त कितना भुगतान कर सकते हैं।लोन की अवधि तय करने से पहले बजाज फाइनेंस की वेबसाइट पर होम लोन ईएमआई कैलकुलेटर का इस्तेमालकरके कई विकल्पों की तुलना करें।
ब्याज दर के अलावा आपको किन बातों की तुलना करनी चाहिए?
मुख्य बताई गई दर महत्वपूर्ण है, लेकिन शुल्क, लचीलापन और अन्य शर्तें कुल लागत को प्रभावित करती हैं। अगरब्याज दर फ्लोटिंग है, तो यह भी समझें कि वह किस बेंचमार्क से जुड़ी है और उसमें बदलाव होने पर आपके भुगतानपर क्या असर पड़ेगा।
क्या देखें
क्या जांचें
प्रोसेसिंग शुल्क
लागू शुल्क और GST की जांच करें और इसे शुरुआती लागत में शामिल करें
ब्याज दर की संरचना
समझें कि यह फ़िक्स्ड, फ़्लोटिंग या बेंचमार्क-लिंक्ड है या नहीं
दर में बदलाव की शर्तें
बेंचमार्क से जुड़े लोन के लिए, देखें कि ब्याज दर में बदलाव कब और कैसे आप परअसर डालेगा
समय से पहले भुगतान की शर्तें
लोन का कुछ हिस्सा पहले चुकाने और पूरा लोन समय से पहले चुकाने की शर्तों को जांचें
अन्य शुल्क
कानूनी, तकनीकी, प्रशासनिक या अन्य संबंधित शुल्कों की जांच करें
बुकिंग करने से पहले फैसला लेने का आसान तरीका
एक बार जब आप किसी संपत्ति को चुन लेते हैं:
1. कुल खरीद लागत तय करें: कीमत, डाउन पेमेंट और उपलब्ध बचत में से सुरक्षित रूप से इस्तेमाल की जासकने वाली राशि की पुष्टि करें।
2. कर्ज की जरूरत तय करें: उपलब्ध धनराशि के बाद आपको कितने कर्ज की जरूरत है, इसका हिसाबलगाएं।
3. ईएमआई की जांच करें:ईएमआई कैलकुलेटर में अनुमानित कर्ज राशि, ब्याज दर और पसंदीदा अवधिडालें, फिर देखें कि क्या किस्त आपकी मौजूदा देनदारियों के हिसाब से ठीक है।
4. कुल लागत की तुलना करें: अलग-अलग समय-सीमा, चुकाए जाने वाले ब्याज, शुल्क और समय से पहलेभुगतान की शर्तों की तुलना करें।
जब ये सभी आंकड़े सही बैठें, तब आप तय कर सकते हैं कि त्योहार का यह समय घर खरीदने के लिए सही है यानहीं।
बजाज फाइनेंस होम लोन आपकी योजना में कैसे फिट हो सकता है?
बजाज फाइनेंस वेतनभोगी आवेदकों के लिए 15 करोड़ रुपये* तक का होम लोन उपलब्ध कराता है, जिसमें ब्याजदरें 7.25%* प्रति वर्ष से शुरू होती हैं और लोन की अवधि 32 साल* तक हो सकती है। पात्र आवेदकों को आवेदनके 48 घंटे* के भीतर मंजूरी मिल सकती है और वे तेजी से प्रोसेसिंग के लिए 5,000 से अधिक स्वीकृत प्रोजेक्ट में सेचुन सकते हैं।
क्या घर खरीदने के फ़ैसले पर त्योहारों के समय का असर पड़ना चाहिए?
यह प्रभावित कर सकता है, लेकिन वित्तीय स्थिति की जांच के बाद ही। अगर संपत्ति आपके बजट में है, डाउन पेमेंटदेने के बाद भी आपकी पर्याप्त बचत बचती है और ईएमआई आपकी मौजूदा आर्थिक जिम्मेदारियों के साथ आसानीसे संभाली जा सकती है, तो आप आगे बढ़ने के लिए तैयार हो सकते हैं। अगर ये बुनियादी बातें पूरी नहीं होती हैं, तोकोई शुभ तारीख घर खरीदना आपके लिए किफायती नहीं बना सकती।
त्योहार का मौसम शुरुआत करने का मौका हो सकता है, लेकिन फैसला लेने की वजह नहीं। प्रॉपर्टी आपके लिएसही है या नहीं, यह आपको बजट, लोन की रकम, लोन की अवधि और बचत से तय करना चाहिए।
आजकल ज्यादा रिटर्न पाने के लिए कई लोग म्यूचुअल फंड में निवेश करते हैं। लेकिन कभी-कभी निवेश के चक्कर में वे अपने कर्ज को नजरअंदाज कर देते हैं। ऐसा ही एक मामला स्टार्टअप CEO आबिद हसन ने सोशल मीडिया पर साझा किया है। वह अपने नाई के साथ बातचीत कर रहे थे, तभी उन्हें पता चला कि वह एक तरफ म्यूचुअल फंड में पैसा लगा रहा है, जबकि दूसरी तरफ उस पर भारी ब्याज वाले कई लोन भी हैं। इस घटना के बाद हसन ने लोगों को निवेश और कर्ज से जुड़ी एक जरूरी सलाह दी।
बाल कटवाते समय सामने आई हैरान करने वाली बात
आबिद हसन ने X पर बताया कि एक दिन उनके नाई ने उनसे अपने म्यूचुअल फंड पोर्टफोलियो के बारे में राय मांगी। इसके बाद हसन ने उसकी आर्थिक स्थिति को समझने की कोशिश की। बातचीत में पता चला कि नाई ने तीन लोन ले रखे थे, जिन पर 20 फीसदी से ज्यादा ब्याज देना पड़ रहा था।
इसके बावजूद वह म्यूचुअल फंड में निवेश कर रहा था। जब हसन ने उससे इसकी वजह पूछी, तो उसने बताया कि उसे अपने निवेश से 30 फीसदी से ज्यादा रिटर्न मिलने की उम्मीद है।
20% ब्याज वाले कर्ज के बीच निवेश करना कितना सही?
हसन ने इस सोच पर सवाल उठाया। उनका कहना था कि शेयर बाजार या म्यूचुअल फंड से हर बार ज्यादा रिटर्न मिलने की गारंटी नहीं होती। बाजार में उतार-चढ़ाव के कारण निवेश की वैल्यू घट भी सकती है। दूसरी तरफ, लोन पर ब्याज चुकाना एक जरूरी जिम्मेदारी है।
उदाहरण के लिए, अगर किसी व्यक्ति को अपने कर्ज पर 20 फीसदी ब्याज देना पड़ रहा है, तो उसके लिए निवेश से लगातार इससे ज्यादा रिटर्न कमाना मुश्किल हो सकता है। ऐसे में बाजार से मुनाफे की उम्मीद करने के बजाय महंगे कर्ज को कम करना ज्यादा फायदेमंद हो सकता है।
10% से ज्यादा ब्याज वाला लोन पहले चुकाने की सलाह
आबिद हसन ने सलाह दी कि अगर किसी व्यक्ति पर 10 फीसदी से ज्यादा ब्याज वाला कर्ज है, तो उसे अतिरिक्त निवेश करने से पहले कर्ज चुकाने पर ध्यान देना चाहिए। इससे ब्याज का बोझ कम हो सकता है और आर्थिक स्थिति मजबूत बनाने में मदद मिल सकती है।
उन्होंने यह भी कहा कि लोन की किस्त समय पर नहीं चुकाने पर पेनल्टी और अतिरिक्त खर्च बढ़ सकते हैं। नौकरी छूटने जैसी स्थिति में कर्ज चुकाना और भी मुश्किल हो सकता है।
कम आमदनी वाले लोगों के लिए भी जरूरी संदेश
हसन ने लोगों से अपील की कि वे यह सलाह घरेलू कामगारों, ब्लू-कॉलर कर्मचारियों और कम अनुभव वाले नौकरीपेशा लोगों तक भी पहुंचाएं। कई बार लोग लोन की असली लागत और ब्याज दर को ठीक से समझ नहीं पाते।
The person who regularly gives me haircuts once told me he invests in MFs, and asked for my feedback on his portfolio. While he was cutting hair, I thought I will do a financial planning exercise for him. I found out that he had like 3 loans exceeling 20% interest. And yet he was investing in MF. I asked him why, he said he expects 30% plus return.
That tells you how grossly wrong the notions of investors have been in the last few years. And how distorted our financial expectations have gotten. There is no way the market would give him more than his interest rate on loans. And this one financial mistake, of investing while still servicing high interest loans, is something we may all have seen often.
So here is a tip: If you have a loan even in excess of 10% interest, please pay that off first. There is no way market gives you more than that in the long run. Worse, if you miss loan payments, you will have higher interest rates and penalities. If you lose your job, debt is what kills you with all this + extortive collection agents
Most of you reading this might not have this problem – so please tell this to others who might. Your domestic helpers, blue collar workers, even some entry level white collar crowd. They are the ones who are hit the most by the loan sharks
Please pay off your high interest debt first. Investing can wait.
हसन की पोस्ट पर कुछ यूजर्स ने कहा कि कई लोग म्यूचुअल फंड को बचत का जरिया मानते हैं और कर्ज को अलग जिम्मेदारी समझते हैं। एक यूजर ने बताया कि उसके दोस्त ने लोन लिया था, जिसकी प्रभावी सालाना ब्याज दर 24 फीसदी से ज्यादा निकली।
(डिस्क्लेमर: यह रिपोर्ट सोशल मीडिया पर यूज़र द्वारा शेयर किए गए कंटेंट पर आधारित है। मनीकंट्रोल इन दावों की न तो स्वतंत्र रूप से पुष्टि नहीं करता है और न ही इनका समर्थन करता है।)
If you are moving to another state or selling your car to someone, you need to transfer the vehicle registration. This updates the registration to the new state if you relocate, or to the new owner if you sell the car. Since each state’s transport department has its own rules, registration certificate (RC) transfer fees, requirements and timelines can differ. So how exactly do you transfer your RC to a new regional transport office (RTO) and what are the documents and fees required in the process? We answer all your questions here.
Disclaimer:This guide is for private vehicles. Commercial vehicles need additional paperwork, such as permit and fitness documents, which are not covered here. The information used here comes from the Parivahan portal. Documents, fees and deadlines vary by state and RTO, and are subject to change. Check with your local RTO before you apply or pay.
What forms are required for an RC transfer?
Form
Purpose
Form 29
The seller’s notice reporting the transfer of ownership.
Form 30
The buyer’s application to register the vehicle in their name.
Form 31
Transfer of the vehicle to the person who succeeds the owner after their death.
Form 32
Transfer of a vehicle bought through a government auction.
Form 28
Application for a No-objection Certificate (NOC).
Form 35
Application to remove loan, lease or hypothecation details from the RC.
The form you need depends on how the vehicle’s ownership is changing. Forms 29 and 30 are the main forms used in a regular used-car sale.
Why should you complete the RC transfer soon after a sale?
If you do not complete the ownership transfer or pay the applicable RTO charges, you may face penalties. You could also be held legally responsible if a car you sold is still registered in your name and is involved in an accident or criminal offence.
For a vehicle transferred within the same state, the buyer should submit the ownership-transfer application within 14 days of the sale. If the vehicle is registered in another state, the buyer should apply within 45 days. The seller should also protect their own interests instead of waiting for the buyer to finish the entire process. Form 29 and the sale intimation should be submitted promptly to create an official record of the handover. State transport departments may charge late fees or impose penalties if the application is submitted after the deadline.
Don’t forget to transfer the insurance policy
Updating the RC does not automatically transfer the motor insurance policy. The buyer should contact the insurer, submit the updated ownership documents and complete a new proposal or endorsement request. The RC and insurance policy should ultimately show the same owner’s name and address.
The seller’s No Claim Bonus (NCB) belongs to the seller. The seller can request an NCB retention certificate and use the eligible discount on another vehicle. The buyer should start the insurance transfer immediately and complete it within 14 days of the ownership transfer. A delay may affect eligibility for an own-damage claim.
What other documents are required for an RC transfer?
The exact list can vary by state and RTO. A regular sale usually requires:
Original RC.
Completed and signed Forms 29 and 30
Valid motor insurance certificate
Valid pollution under control (PUC) certificate
The buyer’s identity and address proof
PAN card or Form 60, where applicable
Passport-sized photographs
Pencil print of the chassis and engine numbers, if required
Sale agreement or delivery note
Applicable tax-clearance proof
Fee-payment receipt
Financier’s NOC and Form 35, if a loan is recorded
RTO NOC for an interstate transfer
Some states allow Aadhaar-based authentication and digital document submission. Others may require physical copies or verification at the RTO.
How to transfer an RC online?
You can usually start the ownership transfer through the Parivahan vehicle-services portal.
Step 1: Open vehicle-related services
Go to the vehicle-related services section on Parivahan and select the state where the vehicle is registered.
Step 2: Enter the vehicle details
Enter the registration number and open the online services section. For authentication, you may need the last five digits of the chassis number and an OTP sent to the registered mobile number.
The mobile number linked to the RC must be active. If it is outdated, the registered owner may need to update it before continuing.
Step 3: Select transfer of ownership
Choose the transfer-of-ownership service. In some states, the seller must start the application before the buyer can enter the remaining details.
Step 4: Enter the buyer and sale details
Enter the sale date, the buyer’s address and identity details, and any other information requested. Make sure all entries match the supporting documents.
Step 5: Upload the documents
Upload the signed forms and supporting documents where online uploads are available. Make sure the images are clear, and all signatures can be seen.
Step 6: Pay the applicable fee
Check the fee details and pay online. Save the payment receipt and application number.
Step 7: Complete verification
Depending on the state, verification may be completed through Aadhaar authentication, faceless verification or a physical visit to the RTO.
For a physical verification, you may need to bring the original RC, signed forms and identity documents.
Step 8: Track the application
Use the application number or vehicle registration details to check the status on the Parivahan portal. After approval, the updated RC may be available digitally through DigiLocker or mParivahan before the physical card arrives.
How to transfer an RC offline?
You can also complete the transfer by visiting the RTO. The seller and buyer should fill in and sign Forms 29 and 30. The buyer then submits the forms, original RC, insurance, PUC, identity documents and other required papers to the appropriate registering authority.
After the fee is paid, the RTO checks the application and updates the registration record. It may ask for a physical vehicle inspection, especially for interstate transfers, address mismatches or document discrepancies. Always collect an acknowledgement or receipt when you submit the application.
How to transfer an RC within the same state?
A transfer within the same state is usually simpler because the vehicle keeps its existing registration number. The buyer generally submits Forms 29 and 30 along with the RC, insurance, PUC and personal documents. A separate NOC for an interstate transfer is normally not required. However, the process can differ if the seller and buyer come under different RTO jurisdictions within the same state. The online portal will usually direct the application to the relevant authority.
How to transfer an RC between states?
An interstate sale may involve two related processes:
Ownership transfer
Re-assignment of the registration mark in the buyer’s state
The seller should get an NOC from the original RTO using Form 28. The buyer then submits the ownership-transfer documents and pays the applicable road tax in the destination state, whether it be from Haryana, Maharashtra or Tamil Nadu. We will explain this process in the following FAQs.
The documents may include:
Original RC
Forms 29 and 30
RTO NOC
Insurance and PUC certificates
The buyer’s local address proof
Tax-payment documents
Pencil print of the chassis and engine numbers
Vehicle inspection report, if required
If the vehicle is moved to another state for more than 12 months, the owner may also need to apply for a new registration mark.
A road-tax refund from the original state is handled separately and depends on that state’s rules. The owner may need to provide proof of re-registration and tax payment in the new state.
How to get an NOC?
There are two ways to apply for an NOC – offline and online. The first method requires you fill out a copy of the Form 28. After that, attach the other required documents which are mentioned above, pay the applicable fee and submit the application at your RTO. Before starting, make sure there are no pending challans, unpaid toll dues, or vehicle tax payments, as the RTO will not issue an NOC if any dues remain. This process can also be done online by visiting the Parivahan portal – parivahan.gov.in. An NOC is valid for six months from the date of issue.
How to transfer the RC of a car with an active loan?
Check the RC for a hypothecation entry that names the bank or finance company. A vehicle with an active loan generally cannot be transferred without the financier’s consent. The seller should first close the loan or obtain the required approval. After the dues are cleared, the lender provides a loan-closure or no-dues certificate and signs Form 35. The owner can then apply to remove the hypothecation entry from the RC. In some states, you can request hypothecation removal and ownership transfer at the same time. Completing the loan-removal process first can reduce the risk of rejection.
How to transfer the RC of a car after the registered owner’s death?
When the registered owner dies, the person who succeeds to the vehicle should inform the registering authority and apply to transfer ownership using Form 31. The successor may use the vehicle for up to three months if the registering authority is informed within 30 days of the owner’s death.
The application usually requires:
Form 31
Original RC
Insurance and PUC certificates
Death certificate
Proof of succession or legal-heir documents
Declarations from other legal heirs
The applicant’s address and identity proof
Vehicle-verification documents, if required
Requirements can differ if there is a will, more than one legal heir or a dispute over ownership.
How to transfer the RC of a car bought at a government auction?
If you buy a vehicle through an auction held by or on behalf of the Central or a state government, you should apply using Form 32 within 30 days of taking possession. The buyer must submit the auction certificate or sale order, the government authorisation for the auction, the available vehicle documents and the applicable fee. Auction vehicles may have incomplete records, repairs that are still needed or unusual registration histories. Check the documents before bidding.
How much does an RC transfer cost?
RC transfer charges depend on the vehicle category, state, smart-card fee, postal charge, any outstanding tax and whether extra services are needed. The Parivahan portal shows the amount payable before you make an online payment. Under Rule 81 of the Central Motor Vehicles Rules, the RC transfer fee is half the standard registration fee. This may amount to Rs 150 for a motorcycle and Rs 300 for a private car. Delays can attract a late fee of Rs 300 per month for motorcycles and Rs 500 per month for cars. Some states may also impose a penalty if the application is not submitted within 14 days of purchase. Road tax is charged separately, and is applicable if the vehicle is being re-registered in another state.